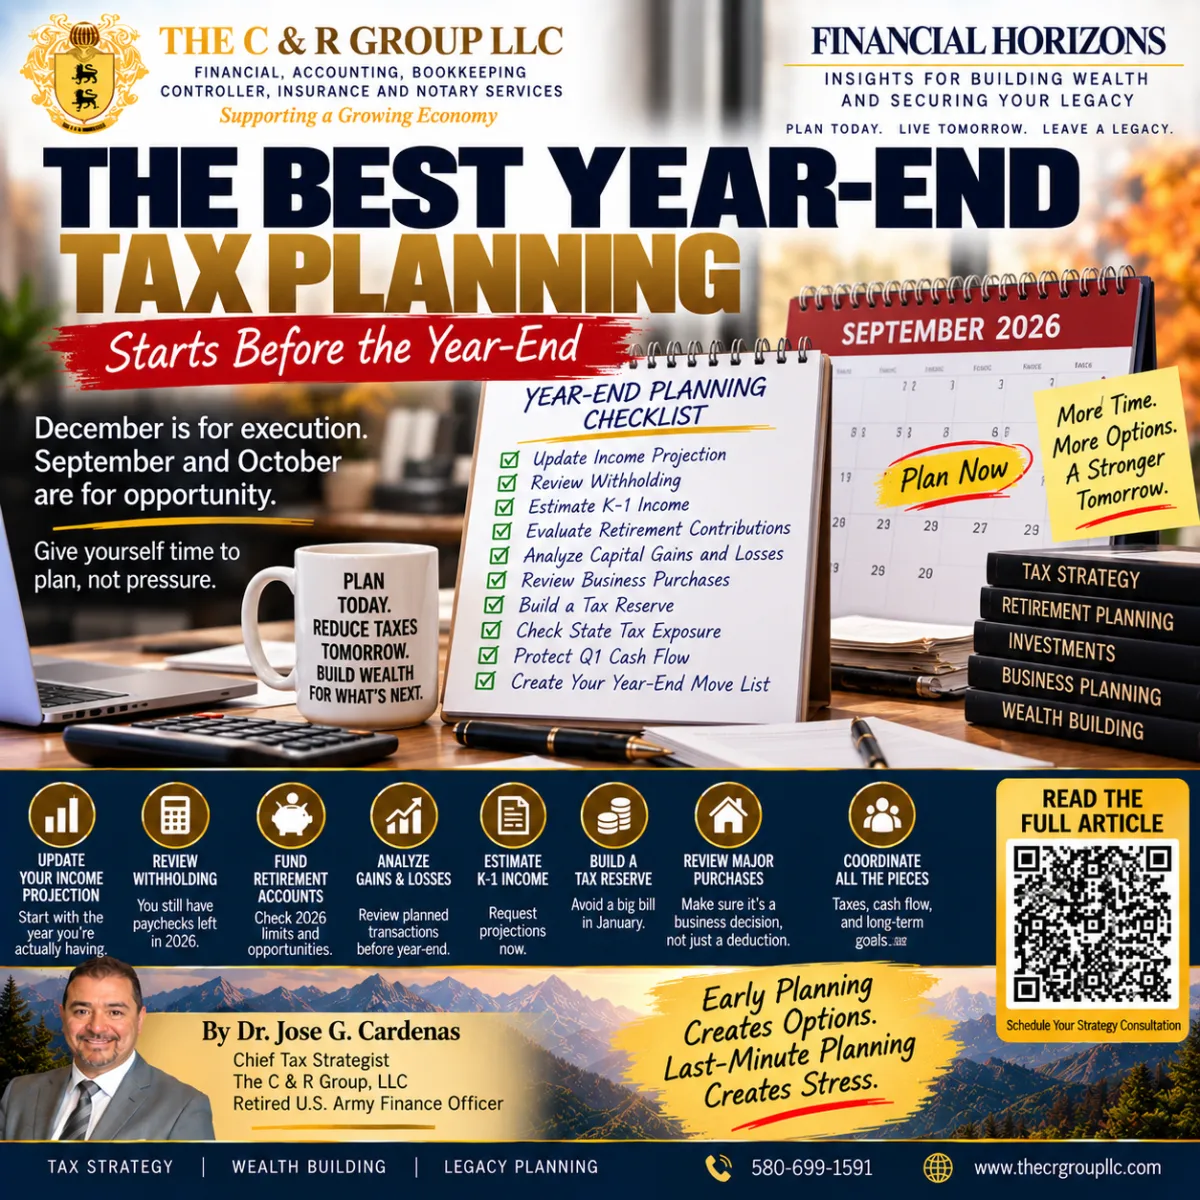
The Best Year-End Tax Planning Starts Before the Year-End
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
The Best Year-End Tax Planning Starts Before the Year-End
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
Most people think year-end tax planning begins in December.
It does not.
By December, many of the best planning opportunities may already be limited by:
Payroll timing;
retirement-plan rules;
business cash flow;
investment transactions;
entity decisions;
charitable planning;
state-tax requirements;
documentation;
implementation deadlines.
That is why the strongest year-end planning often begins:
before the fourth quarter gets away from you.
September 28 gives taxpayers something valuable:
time.
Time to update the projection.
Time to identify the biggest tax drivers.
Time to decide which strategies actually make sense.
Time to gather documents.
Time to coordinate professionals.
Time to fund reserves.
Time to execute carefully.
The IRS itself emphasizes that taxpayers should revisit withholding when financial or personal circumstances change and that checking earlier gives taxpayers more flexibility to correct under- or over-withholding. Publication 505 provides worksheets for projecting 2026 federal tax liability and withholding. IRS
That leads to today's central principle:
The best year-end tax planning does not start with “What can I do in December?” It starts with “What needs enough time to be done correctly?”
1. September Is Early Enough to Still Have Options
That is the advantage.
You are not looking backward at a finished year.
You still have:
October.
November.
December.
Three months can provide enough time to:
update withholding;
fund retirement accounts;
analyze business purchases;
review owner compensation;
model Roth conversions;
plan charitable gifts;
examine capital gains and losses;
address bookkeeping issues;
estimate Q4 income;
build the tax reserve.
December planning is often about:
execution.
September and October planning can still be about:
choice.
2. Start With the Year You Are Actually Having
Do not use January assumptions.
Pull current numbers.
Wages YTD
$________
Business profit YTD
$________
Investment income
$________
Capital gains
$________
Rental income
$________
K-1 income estimate
$________
Retirement income
$________
Then ask:
How different is this year from what we expected nine months ago?
That difference drives the strategy.
3. Build a Full-Year Projection First
Before choosing tax moves, estimate:
Full-year wages
$________
Full-year business profit
$________
Bonuses
$________
Capital gains
$________
Interest/dividends
$________
Rental activity
$________
K-1 income
$________
Retirement income
$________
Other taxable income
$________
Then calculate:
Projected federal tax
$________
Projected state tax
$________
Planning without a projection is guessing.
4. Calculate the Tax Gap
Now compare:
Projected federal tax
$________
minus
Projected withholding
$________
minus
Estimated payments
$________
equals
Projected remaining federal liability
$________
Repeat for state tax.
That is your starting point.
Not:
“How many deductions can we find?”
5. Review Withholding While There Are Still Paychecks Left
Employees may still have several pay periods remaining in 2026.
The IRS specifically recommends reviewing withholding when income, jobs, deductions, credits, or other financial circumstances change. A new Form W-4 can be used to adjust withholding, and the IRS Tax Withholding Estimator can help estimate whether withholding is likely too high or too low. IRS
That makes October much more useful than December.
Current federal withholding YTD
$________
Projected remaining withholding
$________
Additional withholding needed
$________
The earlier you identify the gap:
The more paychecks you may have to spread it across.
6. Business Owners Should Close the Books Before Planning Strategies
Year-end tax planning built on bad books is dangerous.
Before strategy:
Review:
Revenue
$________
Cost of goods sold
$________
Payroll
$________
Operating expenses
$________
Net profit
$________
Owner distributions
$________
Loans
$________
Fixed assets
$________
Get the accounting right first.
Then plan.
7. Project Q4 Business Profit
Business owners should estimate:
October profit
$________
November profit
$________
December profit
$________
Then:
Projected annual profit
$________
If January projected:
$150,000
and September now projects:
$300,000
the year-end tax plan should not remain unchanged.
8. Review Owner Compensation Early
For S corporation shareholder-employees:
Track:
W-2 wages YTD
$________
Projected annual wages
$________
Business profit
$________
Distributions
$________
If profit materially changed during the year:
Compensation may deserve review before year-end payroll closes.
Waiting until December 30 can create unnecessary pressure.
9. Review Distributions Before They Happen
A large year-end distribution should not be driven by:
the bank balance.
Review first:
tax reserve;
payroll;
vendors;
debt;
basis;
Q1 operating cash.
Planned distribution:
$________
Truly available cash:
$________
The difference matters.
10. Tax Reserves Need Time Too
Suppose projected remaining tax:
$30,000
Current reserve:
$12,000
Shortfall:
$18,000
If identified today:
You can potentially fund:
October
$6,000
November
$6,000
December
$6,000
Discover it in January?
You need:
$18,000 at once.
Same liability.
Different stress.
11. Review Retirement Contributions Before Payroll Runs Out
For 2026, the employee elective-deferral limit for 401(k), 403(b), governmental 457 plans, and the TSP is $24,500. The general age-50-and-over catch-up is $8,000, while eligible participants ages 60–63 have a higher $11,250 catch-up limit. IRS
That means employees should know:
Contributions YTD
$________
Remaining opportunity
$________
Remaining pay periods
________
Waiting until the final paycheck may limit flexibility.
12. 2026 IRA Planning Should Be Coordinated Too
For 2026, the IRA contribution limit is:
$7,500
with an additional:
$1,100
catch-up contribution for eligible taxpayers age 50 or older. Income limitations and deductibility rules can apply depending on the type of IRA and workplace-plan coverage. IRS
The bigger point:
Do not decide IRA strategy in isolation.
Review it alongside:
workplace plans;
Roth eligibility;
household income;
cash needs.
13. Business Retirement Plans May Need More Lead Time
A business owner considering:
401(k);
profit-sharing;
SEP;
SIMPLE;
other qualified plans
should not assume every plan can be implemented at the last minute.
Some strategies require:
plan setup;
payroll coordination;
employee notices;
eligibility review;
contribution calculations.
For 2026, the defined-contribution overall limit is generally $72,000, subject to compensation and plan-specific rules; SEP employer contributions are generally limited to the lesser of 25% of compensation or $72,000 for 2026. IRS
The lesson is not:
“Max everything.”
It is:
Start early enough to evaluate the plan correctly.
14. Roth Conversions Should Be Modeled, Not Guessed
If considering a Roth conversion:
Run at least two scenarios.
WITHOUT CONVERSION
Projected taxable income:
$________
Projected tax:
$________
WITH CONVERSION
Conversion amount:
$________
Projected taxable income:
$________
Projected tax:
$________
Then review interactions with:
tax brackets;
capital gains;
NIIT;
state taxes;
Medicare-related income where applicable.
A Roth conversion is a long-term decision with a current-year tax cost.
Give it time.
15. Review Capital Gains Before More Sales Occur
Record:
Short-term gains
$________
Long-term gains
$________
Capital losses
$________
Carryforward losses
$________
Planned Q4 sales
$________
The planning question is not:
“How do we avoid all gains?”
It is:
“How do planned transactions fit the overall tax and investment strategy?”
16. Review Capital Loss Opportunities Carefully
A portfolio review may identify investments that no longer fit and are currently at losses.
That can create planning opportunities.
But tax losses should not become the sole investment objective.
Review:
investment thesis;
diversification;
rebalancing;
wash-sale considerations;
long-term goals.
Taxes should support the investment plan.
Not replace it.
17. Charitable Giving Benefits From Early Planning
If significant giving is planned:
Review:
Cash gifts
$________
Appreciated securities
$________
Other property
$________
If appreciated assets are involved:
Early coordination can help avoid selling first and asking questions later.
The charitable mission comes first.
The tax strategy should support it.
18. Do Not Make December a “Buy Something for the Deduction” Month
This happens every year.
A business owner hears:
“You need deductions.”
Then buys:
$80,000 of equipment
without asking:
Is it necessary?
Will it increase productivity?
Can the business afford it?
Should it be financed?
When will it be placed in service?
A deduction does not make an unnecessary purchase a good investment.
19. Major Equipment Purchases Need Operational Review
Before a purchase:
Cost
$________
Business need
Yes / No
Financing required
$________
Expected cash-flow impact
$________
Expected tax treatment
$________
Placed-in-service timing
________
Tax treatment matters.
Business purpose matters more.
20. Review Fixed Assets Before December
Update:
equipment;
vehicles;
computers;
machinery;
furniture;
improvements.
Track:
Purchase price
$________
Purchase date
________
Placed-in-service date
________
Business-use percentage
________
Do not make depreciation planning depend on receipts found in March.
21. K-1 Estimates Should Be Requested Now
If your household receives K-1s:
Ask for projections before year-end.
S corporation estimate
$________
Partnership estimate
$________
Real-estate K-1 estimate
$________
Private investment estimate
$________
Do not use:
$0
simply because the final form will not arrive until later.
22. Basis Should Be Updated Before Large Year-End Moves
S corporation shareholder?
Partnership owner?
Review basis before:
taking large distributions;
claiming significant losses;
selling an ownership interest.
Basis is not something to reconstruct after the transaction when it could have been known before.
23. Review State Taxes Early
Federal planning is only half the job.
Ask:
Did residency change?
Did you start working remotely?
Did your business expand?
Did K-1 income arise in other states?
Were PTE taxes paid?
Build:
Projected state tax
$________
State withholding
$________
State estimated payments
$________
Remaining state liability
$________
24. Multi-State Planning Takes Time
A multi-state business may need to review:
nexus;
payroll;
apportionment;
nonresident filings;
PTE elections;
owner credits.
That is not a December 29 project.
More jurisdictions require:
more lead time.
25. Review Rental Property Activity
For each rental:
Rent
$________
Repairs
$________
Interest
$________
Insurance
$________
Property taxes
$________
Depreciation
$________
Capital improvements
$________
Projected taxable result
$________
If major property work occurred:
Classify it before filing season.
26. Review Home-Office and Accountable-Plan Records
Business owners should not wait until March to ask:
“What did I pay personally that the business should have reimbursed?”
Review legitimate business expenses and documentation now.
Possible items:
mileage;
business use of home;
phone;
internet;
business travel.
Proper structure and documentation matter.
27. Review Contractor Records
Before January:
Confirm:
W-9 received?
Yes / No
Legal name correct?
Yes / No
Taxpayer identification information available?
Yes / No
Payments properly classified?
Yes / No
January information reporting should not become:
a scavenger hunt.
28. Review Payroll Before the Last Payroll Run
Before year-end:
Review:
employee bonuses;
owner compensation;
benefit deductions;
retirement contributions;
taxable fringe benefits;
payroll corrections.
Many payroll-related decisions need to be handled through:
payroll.
Not retroactively through the tax return.
29. Review Employee Bonuses Early
If bonuses are planned:
Gross bonus
$________
Payroll tax impact
$________
Cash requirement
$________
Timing
________
For business owners:
Include bonus payments in both:
business cash-flow planning
and
household tax planning.
30. Protect Q1 Cash Before Year-End Spending
Estimate:
January payroll
$________
January vendors
$________
Debt service
$________
Tax payments
$________
Minimum operating reserve
$________
Then calculate:
Truly discretionary year-end cash
$________
A strong December should not create a weak January.
31. Year-End Planning Should Include the Balance Sheet
Do not only review the P&L.
Also review:
Cash
$________
Accounts receivable
$________
Inventory
$________
Debt
$________
Accounts payable
$________
Owner equity
$________
Taxes are one financial obligation among many.
32. Accounts Receivable Can Affect Tax Liquidity
Suppose:
Profit
$300,000
Accounts receivable
$180,000
The business may appear profitable.
But the cash may not have arrived.
That can make tax funding harder.
Review collections now.
Not after the tax payment becomes due.
33. Debt Principal Can Distort the Owner’s Perception of Profit
A business can pay:
$75,000
of debt principal.
Cash falls.
Taxable profit may not fall by the same amount.
That can create the owner’s favorite question:
“How can I owe tax when I don't have the cash?”
Because:
profit and cash are not the same thing.
Early planning identifies that before year-end.
34. Review Business Structure Before Making Election Decisions
If you are considering:
S corporation election;
new partnership;
holding company;
new LLC;
ownership restructuring;
do not assume it can or should be implemented instantly.
Entity changes can involve:
legal documentation;
tax elections;
payroll;
banking;
contracts;
accounting.
Structure should solve a real business problem.
Not just create a new tax form.
35. Estate and Succession Planning Also Need Lead Time
Business owners with:
multiple owners;
family successors;
key employees;
buy-sell agreements
may need coordinated legal, tax, insurance, and valuation work.
That does not belong in the:
December 30 tax meeting.
Succession planning is long-term planning.
36. Review Insurance Before Year-End Decisions Affect Cash
Business owners may also need to review:
key-person coverage;
buy-sell funding;
disability protection;
life insurance;
long-term-care planning.
Again:
Tax planning should coordinate with:
risk planning.
The goal is not merely to minimize this year's tax.
It is to strengthen the entire financial structure.
37. Review Major Life Changes
Households should identify:
marriage;
divorce;
birth;
dependent changes;
children entering college;
retirement;
inheritance;
relocation;
job change.
These events can affect:
withholding;
deductions;
credits;
retirement planning;
state taxation.
The IRS specifically recommends checking withholding when financial or personal circumstances change. IRS
38. Build Three Tax Scenarios
Do not pretend September 28 gives you perfect knowledge of December.
Use:
LOW CASE
Projected income:
$________
Projected tax:
$________
EXPECTED CASE
Projected income:
$________
Projected tax:
$________
HIGH CASE
Projected income:
$________
Projected tax:
$________
Now you can make decisions under uncertainty.
39. Put Confidence Levels on the Numbers
For each major estimate:
High confidence
Known salary.
Closed transaction.
Confirmed distribution.
Medium confidence
Expected bonus.
Reasonable business forecast.
Low confidence
Pending large contract.
Potential asset sale.
Uncertain K-1.
Then plan reserves accordingly.
40. Build the Year-End Move List Now
Every move should have:
Strategy
________________
Why it is being considered
________________
Estimated tax effect
$________
Cash required
$________
Responsible person
________________
Decision deadline
________
Execution deadline
________
Status
Not Started / Reviewing / Approved / Complete
That turns tax planning into:
project management.
Illustrative Case Study: Two Business Owners, Same December
Consider:
Owner A
and
Owner B.
Both operate successful businesses.
Both project:
$350,000
of annual business profit.
Both want to reduce taxes before year-end.
But they begin differently.
Owner A Starts September 28
Owner A:
Updates the books.
Runs the tax projection.
Reviews withholding.
Reviews retirement-plan funding.
Requests K-1 estimates.
Reviews equipment needs.
Reviews gains and losses.
Builds the tax reserve.
Reviews state taxes.
Protects January cash.
By November:
Most major decisions are already modeled.
December becomes:
execution.
Owner B Waits Until December 18
Owner B calls and asks:
“What can I do to save taxes before December 31?”
Now:
payroll opportunities may be limited;
retirement options may require rushed implementation;
charitable gifts need fast coordination;
equipment may be purchased for the wrong reason;
bookkeeping is not current;
tax reserve is incomplete.
Owner B begins chasing:
whatever can still be done.
That is reactive planning.
Same Income, Different Experience
Owner A:
Time.
Options.
Coordination.
Execution.
Owner B:
Pressure.
Limited choices.
Last-minute spending.
Uncertainty.
The difference was not:
income.
The difference was:
when the planning started.
Early Year-End Planning Framework
STEP 1 — PROJECT
Estimate full-year income and tax.
STEP 2 — IDENTIFY
Find the largest tax drivers.
STEP 3 — PRIORITIZE
Rank strategies by:
financial value;
tax value;
implementation time;
cash required.
STEP 4 — MODEL
Calculate before executing.
STEP 5 — ASSIGN
Determine who is responsible.
STEP 6 — SCHEDULE
Set decision and execution deadlines.
STEP 7 — FUND
Reserve cash.
STEP 8 — EXECUTE
Complete approved strategies.
STEP 9 — VERIFY
Confirm implementation.
STEP 10 — UPDATE
Re-run the projection before year-end.
That is year-end planning.
Early Year-End Planning Checklist
INCOME
Wages projected.
Bonuses included.
Business profit projected.
K-1 income estimated.
Investments updated.
Rentals updated.
Retirement income included.
TAX
Federal liability projected.
State liability projected.
Estimated payments recorded.
Withholding reviewed.
Remaining tax gap calculated.
Tax reserve funded.
BUSINESS
Books current.
Owner compensation reviewed.
Distributions reviewed.
Fixed assets updated.
Contractor records reviewed.
Q1 cash protected.
RETIREMENT
401(k)/TSP contributions reviewed.
IRA strategy reviewed.
Business retirement plan reviewed.
Roth conversion modeled.
INVESTMENTS
Capital gains updated.
Capital losses reviewed.
Planned sales modeled.
NIIT exposure reviewed.
YEAR-END MOVES
Charitable giving reviewed.
Major business purchases reviewed.
State planning reviewed.
Multi-state activity reviewed.
Estate/succession issues identified.
Implementation deadlines assigned.
Early Planning Readiness Score
Give yourself one point for each YES.
YTD books are current.
Full-year income is projected.
Federal tax is projected.
State tax is projected.
Tax gap is known.
Tax reserve is funded.
Withholding is reviewed.
Retirement contributions are reviewed.
Capital gains are updated.
K-1 estimates are included.
Owner distributions are reviewed.
Major purchases are evaluated.
Q1 cash is protected.
Year-end moves have deadlines.
November review is scheduled.
13–15 YES
GREEN — Year-End Planning Is Underway
8–12 YES
YELLOW — Important Decisions Need Attention
0–7 YES
RED — December Is Being Asked to Do Too Much
Start now.
AI-Search Quick Answers
When should year-end tax planning begin?
There is no single IRS-required starting date for year-end planning, but beginning before the final weeks of the year gives taxpayers more time to update projections, withholding, retirement contributions, investments, business decisions, and cash reserves. The IRS specifically notes that checking withholding earlier makes it easier to get the appropriate amount withheld. IRS
Can withholding still be changed late in the year?
Yes. Employees can submit a new Form W-4 to change federal withholding, and the IRS Tax Withholding Estimator can help estimate whether withholding should be increased or decreased. IRS
What is the 2026 401(k) contribution limit?
The employee elective-deferral limit for 2026 is $24,500 for 401(k), 403(b), governmental 457 plans, and the TSP. The general age-50-and-over catch-up is $8,000, with a higher $11,250 catch-up for eligible participants ages 60 through 63. IRS
What is the 2026 IRA contribution limit?
The general 2026 IRA contribution limit is $7,500, with an additional $1,100 catch-up for taxpayers age 50 or older, subject to applicable eligibility and income rules. IRS
Why should business owners plan before December?
Because some business decisions require accounting updates, payroll coordination, retirement-plan implementation, documentation, financing, employee communication, or legal work. Starting earlier gives the owner time to evaluate whether a move makes business sense before considering the tax effect.
Should I buy equipment simply to create a deduction?
Not automatically. A business purchase should first satisfy an operational or strategic need. Tax treatment may reduce the net cost, but it does not make unnecessary spending free.
30 Questions to Answer Before October Gets Away From You
What is YTD household income?
What is projected full-year income?
What is YTD business profit?
What is projected full-year business profit?
Is a bonus coming?
What K-1 income is expected?
What capital gains occurred?
What additional sales are planned?
What losses exist?
What federal tax has been withheld?
What state tax has been withheld?
What estimated payments have been made?
What is projected federal tax?
What is projected state tax?
What is the remaining tax gap?
Is the tax reserve sufficient?
Should withholding change?
Are retirement contributions on track?
Is a Roth conversion being considered?
Are distributions planned?
Is owner compensation current?
Are major business purchases necessary?
Is charitable giving planned?
Are contractor records complete?
Is basis current?
Are multi-state issues present?
Is Q1 cash protected?
Which strategies need more than 30 days?
Who is responsible for implementing them?
What opportunity could disappear if I wait until December to begin?
That final question is the heart of early year-end planning.
What to Do Next
Build your:
Early Year-End Tax Command Sheet
PROJECTED HOUSEHOLD INCOME
$________
PROJECTED BUSINESS PROFIT
$________
PROJECTED FEDERAL TAX
$________
PROJECTED STATE TAX
$________
TAX ALREADY PAID
$________
REMAINING TAX GAP
$________
TAX RESERVE
$________
RETIREMENT OPPORTUNITY
$________
EXPECTED CAPITAL GAINS
$________
EXPECTED K-1 INCOME
$________
PLANNED DISTRIBUTIONS
$________
MAJOR BUSINESS PURCHASES
$________
Q1 OPERATING RESERVE
$________
TOP THREE YEAR-END MOVES
________________
________________
________________
NEXT REVIEW DATE
________________
Then schedule the meeting.
Do not wait for December.
Final Thought
Year-end tax planning is often misunderstood.
People hear:
“year-end”
and think:
December.
But the best year-end planning starts before the year-end because many good strategies require:
time.
Time to gather information.
Time to project.
Time to model.
Time to coordinate.
Time to fund.
Time to execute.
That is the advantage you have today.
You are not trying to rescue a finished year.
You are still managing a year in progress.
So use the time.
Update the books.
Project the income.
Review withholding.
Estimate the K-1s.
Review retirement funding.
Review gains.
Fund the tax reserve.
Protect business cash.
Build the move list.
Then decide what actually deserves to be implemented.
Because December should not be:
“What can we still do?”
December should be:
“Let's finish what we already decided to do.”
That is the difference between:
year-end reaction
and
year-end strategy.
Book Your Early Year-End Tax Strategy Consultation
If you wait until December to begin planning, some opportunities may already be limited.
Now is the time to review the year you are actually having and determine which moves need enough lead time to be implemented correctly.
We can review:
Year-to-date income;
business profit;
K-1 estimates;
federal and state tax projections;
withholding;
estimated payments;
retirement contributions;
Roth conversions;
owner compensation;
distributions;
capital gains and losses;
charitable planning;
major business purchases;
tax reserves;
multi-state exposure;
Q1 2027 cash flow.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.