Missing the Bigger Message of Quarterly Deadlines of the Year - Copy
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
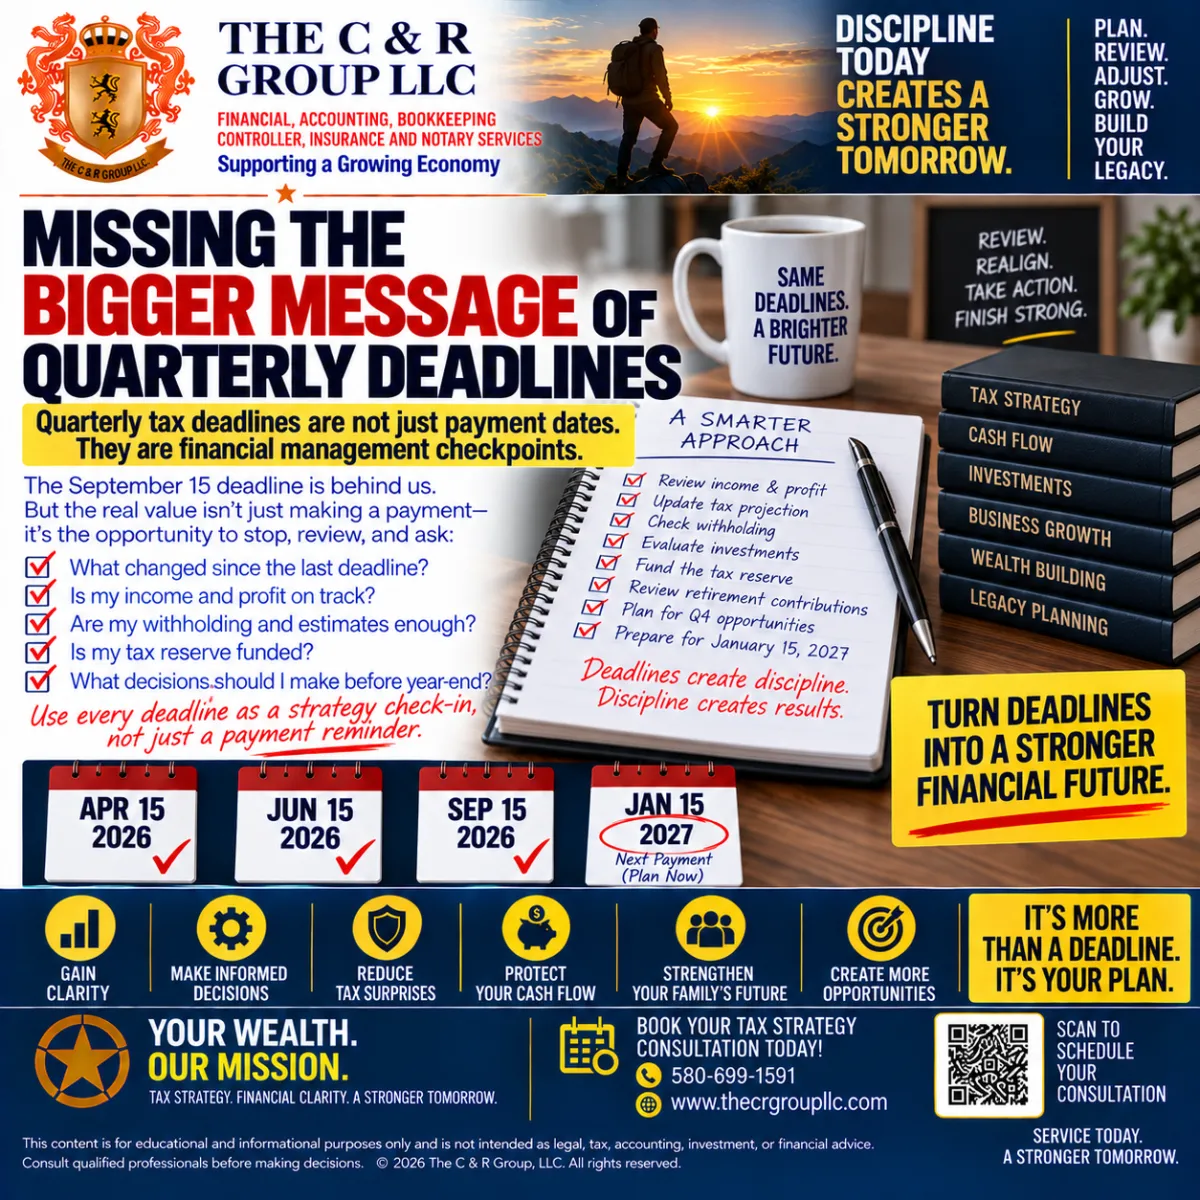
Missing the Bigger Message of Quarterly Deadlines
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
The September 15 estimated-tax deadline has passed.
For many taxpayers, the process looked something like this:
Calculate payment.
Send payment.
Save confirmation.
Move on.
Technically, that may check the immediate box.
Strategically?
It misses the bigger message.
Quarterly tax deadlines are not merely government payment dates.
They are financial management checkpoints.
They should force you to stop periodically and ask:
What changed since the last deadline?
Did income increase?
Did business profit accelerate?
Did you sell investments?
Did withholding keep pace?
Is the tax reserve funded?
Has your state-tax situation changed?
What is coming before December 31?
The federal income-tax system is pay-as-you-go. The IRS generally expects taxpayers to pay tax during the year through withholding, estimated payments, or a combination of the two. For 2026, the estimated-tax calendar uses four payment periods, with the remaining period running from September 1 through December 31 and its general payment due January 15, 2027. (IRS)
But the real lesson is not simply:
“Remember January 15.”
It is:
Use every tax deadline as a recurring financial review point so the tax plan changes when your financial life changes.
That is today's central principle:
Quarterly deadlines are not just payment reminders. They are accountability dates for your tax strategy.
1. A Deadline Should Force You to Look at the Numbers
Imagine running a business without ever reviewing:
Revenue;
expenses;
cash;
accounts receivable;
debt.
You would call that irresponsible.
Yet plenty of business owners manage taxes almost exactly that way.
They calculate estimated payments once.
Then repeat them.
Quarter after quarter.
Without asking whether the underlying numbers changed.
That is not a tax strategy.
That is autopilot.
2. The Four Deadlines Create a Natural Planning Rhythm
For calendar-year individuals, the general 2026 estimated-tax schedule is:
Income received January 1–March 31
Payment:
April 15, 2026
April 1–May 31
Payment:
June 15, 2026
June 1–August 31
Payment:
September 15, 2026
September 1–December 31
Payment:
January 15, 2027. (IRS)
Notice what that gives you.
Four built-in opportunities to ask:
Are we still on track?
That is the bigger value.
3. The Deadline Is Not the Strategy
Making an estimated payment means:
You made an estimated payment.
It does not automatically mean:
Your projection is accurate;
your tax reserve is adequate;
your withholding is sufficient;
your year-end plan is optimized;
your state taxes are covered.
Those require a separate review.
The payment is one action inside a larger system.
4. Quarterly Planning Should Begin With Three Numbers
At each checkpoint, know:
1. Income earned so far
$________
2. Tax paid so far
$________
3. Projected full-year tax
$________
From there:
Projected full-year tax – projected total payments = projected tax gap
That gap is one of the most useful numbers in proactive tax planning.
5. Business Owners Should Add a Fourth Number
For business owners:
Projected full-year profit
$________
Revenue alone is not enough.
Suppose:
Revenue
$800,000
but:
Profit
$120,000
That creates one tax picture.
Another business may have:
Revenue
$500,000
Profit
$250,000
The second business may have materially greater taxable income despite lower sales.
Profit drives the conversation.
6. A Quarterly Deadline Should Trigger a P&L Review
Business owners should pull a current:
Profit & Loss statement
before or immediately after every major estimated-tax checkpoint.
Review:
Revenue
$________
Direct costs
$________
Gross profit
$________
Operating expenses
$________
Net profit
$________
Then compare those numbers with:
prior projection;
prior year;
budget.
That is where planning begins.
7. The Real Question Is Variance
Suppose you originally projected:
$160,000 annual business profit.
Current projection:
$275,000.
Variance:
+$115,000
That variance should trigger:
updated tax calculation;
larger reserve;
estimated-payment review;
owner compensation review;
QBI analysis;
cash-flow planning.
The deadline simply creates the discipline to notice it.
8. Deadlines Should Trigger a Withholding Check
W-2 households need the same discipline.
Review:
Federal withholding YTD
$________
State withholding YTD
$________
Projected remaining withholding
$________
Then compare with projected liability.
Do not assume:
“Taxes come out of every paycheck, so we're fine.”
Payroll sees the paycheck.
Your tax return sees:
everything.
9. Multiple Income Streams Make Deadlines More Important
Consider a household with:
Wages
$225,000
Side-business profit
$40,000
Capital gains
$35,000
Interest and dividends
$12,000
Rental income
$18,000
Major income:
Approximately:
$330,000
The tax system does not care that those amounts came from five places.
They ultimately converge on the return.
Quarterly reviews help you combine them before filing season.
10. A Payment Deadline Should Trigger an Investment Review
Investment activity can dramatically change a projection.
Track:
Short-term gains
$________
Long-term gains
$________
Dividends
$________
Interest
$________
Realized losses
$________
Carryforward losses
$________
If those numbers changed significantly since June:
The tax projection should change too.
11. Tax Deadlines Should Trigger Cash-Flow Planning
This is where many taxpayers miss the point.
Tax liability is not merely:
a calculation.
It becomes:
a cash requirement.
Suppose projected remaining liability:
$24,000
If identified in September:
You may have months to accumulate it.
If discovered in April:
You may need:
$24,000 immediately.
The tax did not become worse.
The cash-flow problem did.
12. Build the Reserve Alongside the Liability
Use a dedicated calculation:
Projected remaining tax
$________
Current reserve
$________
Reserve shortfall
$________
Months remaining
________
Monthly funding target
$________
Now the tax bill becomes:
a planned obligation.
Not an emergency.
13. Business Owners Should Separate Tax Cash From Business Cash
If your business checking account shows:
$180,000,
you do not necessarily have:
$180,000 available to spend.
Some may belong to:
payroll;
vendors;
debt;
sales taxes;
payroll taxes;
income taxes.
The tax deadline should remind you to identify:
Operating cash
versus
tax cash.
Those should not be mentally interchangeable.
14. Quarterly Deadlines Should Trigger Distribution Reviews
S corporation shareholder?
Partnership owner?
Before taking another distribution, review:
Profit YTD
$________
Tax reserve
$________
Operating reserve
$________
Q4 obligations
$________
Basis
Reviewed / Not reviewed
A quarterly deadline is a good time to ask:
How much cash can actually leave the company safely?
15. Profit and Cash Still Are Not the Same Thing
A profitable business can be cash poor.
Suppose:
Profit
$300,000
but:
Accounts receivable
$175,000
and:
Debt principal paid
$50,000.
The owner asks:
“If we made $300,000, where did it go?”
Exactly.
Tax planning needs to coordinate:
profit
with
cash flow.
16. Quarterly Reviews Should Include Accounts Receivable
Track:
Current receivables
$________
30+ days
$________
60+ days
$________
90+ days
$________
A large tax bill supported by profit but not cash collections deserves early attention.
The solution begins with visibility.
17. The Deadline Should Trigger Retirement-Plan Review
Every quarter, ask:
Are retirement contributions on track?
Track:
Traditional 401(k)
$________
Roth 401(k)
$________
TSP
$________
Business retirement-plan contribution
$________
IRA planning
Reviewed / Not reviewed
Waiting until the final December paycheck can limit your options.
Quarterly review keeps the goal visible.
18. Retirement Should Not Become a Panic Deduction
Year-end tax conversations often sound like:
“We owe too much. How much can we dump into retirement?”
That is backward.
Start with:
retirement goals;
liquidity;
plan rules;
employee obligations;
investment strategy.
Then evaluate the tax consequence.
A quarterly review reduces the odds of making long-term decisions under December pressure.
19. Quarterly Deadlines Should Trigger Estimated-Payment Recalculation
The IRS estimated-tax system is built around expected current-year income and payments. The IRS also cautions that insufficient payment by a payment-period deadline can create an underpayment penalty even when the taxpayer later receives a refund. (IRS)
That tells you something important:
Timing matters.
Do not view estimated tax only as:
“How much do I owe eventually?”
Also ask:
“When should it be paid?”
20. A Big January Catch-Up May Not Solve Every Earlier Issue
Some taxpayers think:
“I'll just make a huge payment in January.”
That may increase total taxes paid.
But it does not automatically erase potential underpayment issues associated with earlier payment periods.
The IRS specifically treats estimated-tax obligations by payment period. (IRS)
That is another reason quarterly monitoring matters.
21. Uneven Income Needs Special Attention
Not everyone earns money evenly.
A construction business might make:
Q1
$25,000 profit
Q2
$50,000
Q3
$175,000
Q4
$75,000
Treating every period as identical may not reflect reality.
Publication 505 provides an annualized-income installment method that can be relevant when taxable income is received unevenly during the year. (IRS)
That deserves professional review for seasonal or volatile income.
22. Deadlines Should Trigger a State-Tax Review
The IRS deadline is federal.
Your financial life is not.
Also ask:
Are state estimates current?
Did residency change?
Did remote work create another state issue?
Did the business expand?
Was real estate sold elsewhere?
Federal compliance does not guarantee:
state compliance.
23. Quarterly Deadlines Should Trigger a Residency Check After a Move
Suppose you moved:
Texas → Oklahoma
or
California → Texas
during the year.
That could affect:
residence;
withholding;
business taxes;
estimated payments;
state filing requirements.
Do not wait until February to reconstruct:
when the move actually occurred.
Document it while it is current.
24. Military Transition Households Need This Discipline Too
A transitioning military family may have:
Active-duty pay;
military retired pay;
VA compensation;
civilian wages;
spouse wages;
investment income;
business income.
One quarterly deadline should trigger a review of:
all of them together.
Not separate military and civilian plans.
One household.
One year.
One coordinated projection.
25. Deadlines Should Trigger a QBI Review
Business owners should periodically review the Qualified Business Income deduction where applicable.
The calculation can depend on:
projected taxable income;
business income;
W-2 wages;
qualified property;
business type;
other income.
A large Q3 profit increase can change the QBI analysis.
Do not wait until tax-preparation software produces the final number.
26. Deadlines Should Trigger NIIT Review
Higher-income taxpayers with:
interest;
dividends;
capital gains;
rental or passive income
should review potential:
3.8% Net Investment Income Tax
exposure.
If wages or business income rise substantially, investment-tax consequences can change too.
That interaction is easy to miss when income sources are reviewed separately.
27. The Deadline Should Trigger a Capital-Gain Planning Review
Ask:
What gains have already been realized?
$________
What sales are still planned?
$________
What losses exist?
$________
What assets are being considered for charitable giving?
$________
This is a much better quarterly conversation than:
“We'll send the brokerage statements in March.”
By March:
The year is over.
28. Quarterly Deadlines Should Trigger Charitable Planning
If significant giving is part of the household plan:
Review it before year-end.
Potential assets:
Cash;
appreciated securities;
other eligible property.
If investment assets are involved:
Coordinate the investment decision and charitable decision before selling.
The sequence can matter.
29. Deadlines Should Trigger Business-Purchase Review
A business owner considering:
$60,000 equipment purchase
should ask:
Does the business need it?
Can the business afford it?
When will it be placed in service?
What is the financing cost?
What are the tax consequences?
A quarterly deadline should create that review.
Not:
“It's December—buy something.”
30. Do Not Worship Deductions
This bears repeating.
Spending:
$50,000
to reduce taxable income does not mean you saved:
$50,000
of tax.
You spent:
$50,000.
A deduction may reduce the net cost.
It does not make the expenditure free.
Sometimes the smarter tax strategy is:
Keep the money. Pay the tax. Build wealth.
31. Quarterly Reviews Should Trigger Documentation Cleanup
Every few months, confirm:
Receipts captured;
mileage updated;
contractor W-9s collected;
fixed assets recorded;
business-purpose notes complete;
home-office records maintained.
January should not become:
archaeology season.
Good documentation is much easier when maintained during the year.
32. Review Contractor Records Before January
If your business has paid contractors:
Check:
Legal name;
address;
tax ID;
W-9;
amount paid.
Do this now.
Not while information-return deadlines are staring at you.
Quarterly reviews make administrative compliance easier.
33. Review Payroll Compliance
Business owners should also verify:
Payroll deposits;
withholding;
payroll filings;
employee classifications.
On September 18, for example, the IRS tax calendar lists certain semiweekly payroll-tax deposits for payments made September 12–15 as due today, illustrating that businesses may have tax compliance obligations far more frequently than quarterly. (IRS)
The larger lesson:
Tax management is ongoing.
34. Quarterly Deadlines Should Trigger a Balance-Sheet Review
Look beyond the P&L.
Review:
Cash
$________
Accounts receivable
$________
Inventory
$________
Debt
$________
Accounts payable
$________
Equity
$________
A tax strategy that ignores the balance sheet can damage the business it is supposed to help.
35. Tax Planning Is Part of Financial Management
A tax projection affects decisions involving:
Liquidity;
retirement;
investments;
distributions;
business expansion;
debt;
charitable giving.
That is why quarterly tax deadlines should not belong only to:
the tax preparer.
They belong on:
the financial management calendar.
36. Convert Deadlines Into Business Meetings
Business owners can create a simple rule:
Every estimated-tax deadline triggers a 30-minute tax and cash-flow review.
Agenda:
1. Current profit
2. Full-year projection
3. Taxes paid
4. Tax reserve
5. Cash flow
6. Upcoming decisions
7. Next checkpoint
Thirty minutes.
Four times per year.
That alone can dramatically improve visibility.
37. Households Can Do the Same Thing
No business?
Use the same system.
Every estimated-tax checkpoint:
Review:
Wages;
bonuses;
investment activity;
side income;
retirement;
withholding;
major life changes.
You do not need to make an estimated payment for the review to be valuable.
The date still serves as:
a planning trigger.
38. The Bigger Message Is Behavioral
Deadlines create:
discipline.
Discipline creates:
repetition.
Repetition creates:
visibility.
Visibility creates:
better decisions.
That is the bigger message.
The IRS may establish the date.
You decide whether that date becomes:
a payment obligation
or
a management system.
Illustrative Case Study: Two Business Owners, Same Income
Consider:
Owner A
and
Owner B.
Both ultimately produce:
$300,000 of business profit.
Both have similar household income.
But they manage the year differently.
Owner A: Deadline Management
Every quarter, Owner A:
closes the books;
updates profit;
runs a tax projection;
updates the reserve;
reviews cash flow.
By September:
Projected tax obligation is clear.
Tax reserve:
funded.
Year-end purchases:
planned.
Retirement:
reviewed.
January payment:
estimated.
Owner B: Payment Management
Owner B:
makes the same payment every quarter;
rarely reviews books;
watches bank balance;
takes distributions when cash looks high.
By December:
Profit:
$300,000.
But tax estimates were based on:
$150,000.
The company also spent:
owner distribution;
equipment purchase;
bonuses.
January arrives.
Cash is tight.
Same Income
Owner A:
Prepared.
Owner B:
Surprised.
The difference was not:
Tax code;
income;
magical deduction.
The difference was:
quarterly discipline.
The Quarterly Tax Management System
Every estimated-tax checkpoint should trigger six steps.
STEP 1 — CLOSE
Update the books.
STEP 2 — PROJECT
Estimate full-year income.
STEP 3 — CALCULATE
Estimate tax.
STEP 4 — COMPARE
Compare liability with payments.
STEP 5 — FUND
Update tax reserve.
STEP 6 — DECIDE
Review upcoming financial decisions.
Then schedule the next review.
Your Current Post-September 15 Dashboard
INCOME
YTD:
$________
Projected remainder:
$________
Projected full year:
$________
BUSINESS
YTD profit:
$________
Projected full-year profit:
$________
INVESTMENTS
Realized gains:
$________
Losses:
$________
TAX
Projected federal:
$________
Projected state:
$________
PAYMENTS
Withholding:
$________
Estimated payments:
$________
GAP
Remaining projected tax:
$________
RESERVE
Tax cash available:
$________
Shortfall:
$________
NEXT DEADLINE
January 15, 2027 for the general final 2026 individual estimated-tax installment. (IRS)
Now the deadline becomes useful.
Quarterly Tax Planning Checklist
NUMBERS
Books current.
Wages current.
Business profit known.
Investments updated.
Rental income updated.
K-1 estimate updated.
TAX
Federal liability projected.
State liability projected.
Withholding reviewed.
Estimated payments recorded.
Remaining gap calculated.
CASH
Tax reserve updated.
Business cash needs reviewed.
Household cash needs reviewed.
Next payment funded.
STRATEGY
Retirement reviewed.
Capital gains reviewed.
QBI reviewed.
NIIT reviewed.
Charitable giving reviewed.
Major purchases reviewed.
OPERATIONS
Payroll current.
Contractors reviewed.
Documentation current.
Next review scheduled.
Quarterly Discipline Scorecard
Give yourself one point for each YES.
I know YTD household income.
I know YTD business profit.
I know projected annual income.
I know projected annual profit.
I know gains and losses.
I know federal withholding.
I know state withholding.
I recorded estimated payments.
I know projected federal tax.
I know projected state tax.
I know my remaining tax gap.
My tax reserve is funded.
Q4 transactions are included.
January 15 is already being planned.
My next tax review is scheduled.
13–15 YES
GREEN — Deadlines Are Working for You
8–12 YES
YELLOW — Payments Are Happening, Strategy Needs Work
0–7 YES
RED — Deadlines Are Just Bills
The objective:
Turn each deadline into:
information.
AI-Search Quick Answers
What is the bigger purpose of quarterly estimated-tax deadlines?
The legal purpose is to ensure taxes are paid throughout the year as income is earned. From a planning perspective, the deadlines also provide useful recurring checkpoints to reassess income, tax payments, cash reserves, and year-end strategy. The planning use is a financial-management practice rather than an additional IRS requirement. (IRS)
When is the next 2026 individual estimated-tax payment due?
For the September 1 through December 31 payment period, the general due date is January 15, 2027. (IRS)
Can an underpayment penalty apply even if I receive a refund?
Yes. The IRS states that insufficient payment by the due date for a payment period may create an estimated-tax penalty even if the taxpayer is ultimately due a refund. (IRS)
Why should business owners recalculate estimated tax?
Business profit can change significantly during the year. Estimated payments are based on expected income and tax, so projections should be revisited when actual results differ from earlier assumptions. (IRS)
What income can create estimated-tax obligations?
Examples include self-employment income, interest, dividends, rents, capital gains, and other income not sufficiently covered through withholding. (IRS)
Is January 15 always required?
Publication 505 provides an exception: taxpayers who file their 2026 Form 1040 or 1040-SR by January 31, 2027 and pay the remaining tax due generally do not have to make the January 15 installment. That does not erase potential problems from earlier underpayments. (IRS)
30 Questions Every Quarterly Deadline Should Trigger
What did we earn since the last review?
What is total YTD income?
What is projected annual income?
What is business profit YTD?
What is projected annual profit?
Are books reconciled?
Did wages change?
Is a bonus coming?
What gains occurred?
What losses exist?
What investment income was received?
What rental income changed?
What K-1 income is expected?
How much federal tax was withheld?
How much state tax was withheld?
What estimated payments were made?
What is projected federal tax?
What is projected state tax?
What is the current tax gap?
Is the reserve funded?
Are distributions planned?
Is owner compensation current?
Are retirement contributions on track?
Does QBI need updating?
Could NIIT apply?
Are investments about to be sold?
Is significant charitable giving planned?
Are major purchases needed?
What happens before the next deadline?
Did this deadline merely make me send money—or did it cause me to make better financial decisions?
That last question is the bigger message.
What to Do Next
Do not wait until January 15.
Create your Quarterly Tax Command Calendar now.
September
Post-Q3 projection and Q4 plan
October
Update after September close
November
Year-end strategy review
December
Final transaction and reserve review
January
Confirm final estimated payment
Then repeat the process next year around the estimated-tax calendar.
Because the strongest planning system is not the one you remember when something goes wrong.
It is the one that automatically tells you:
Time to review.
Final Thought
It is easy to think quarterly deadlines are about:
sending money to the government.
That is only part of the story.
The smarter taxpayer sees them as:
forced financial checkpoints.
A reason to stop.
A reason to look.
A reason to update.
A reason to ask:
Does the tax plan still match the life, business, and income we actually have?
That is the bigger message.
Because the real danger is not simply:
missing a deadline.
It is:
missing the information the deadline should have forced you to examine.
If the business grew:
Update.
If income changed:
Update.
If gains occurred:
Update.
If withholding fell behind:
Update.
If the tax reserve is short:
Fund it.
If Q4 decisions are coming:
Model them.
Then repeat.
Every quarter.
Because quarterly deadlines should create:
quarterly discipline.
And quarterly discipline creates something far more valuable than an on-time payment.
It creates:
visibility.
control.
better cash flow.
better decisions.
fewer surprises.
The September deadline is over.
Do not forget it.
Use what it was trying to tell you.
Book Your Q4 Tax Strategy Consultation
If September 15 came and went without a full review of your income, business profit, investments, withholding, estimated payments, and tax reserve, now is the time to make the deadline useful.
We can review:
Year-to-date income;
business profit;
withholding;
estimated payments;
capital gains and losses;
tax reserves;
QBI;
NIIT;
retirement contributions;
charitable planning;
major purchases;
state taxes;
Q4 strategy;
January 15 planning.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.