Business Owners: Your Q3 Payment Is Due, but the Bigger Issue Is What Happens Next
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
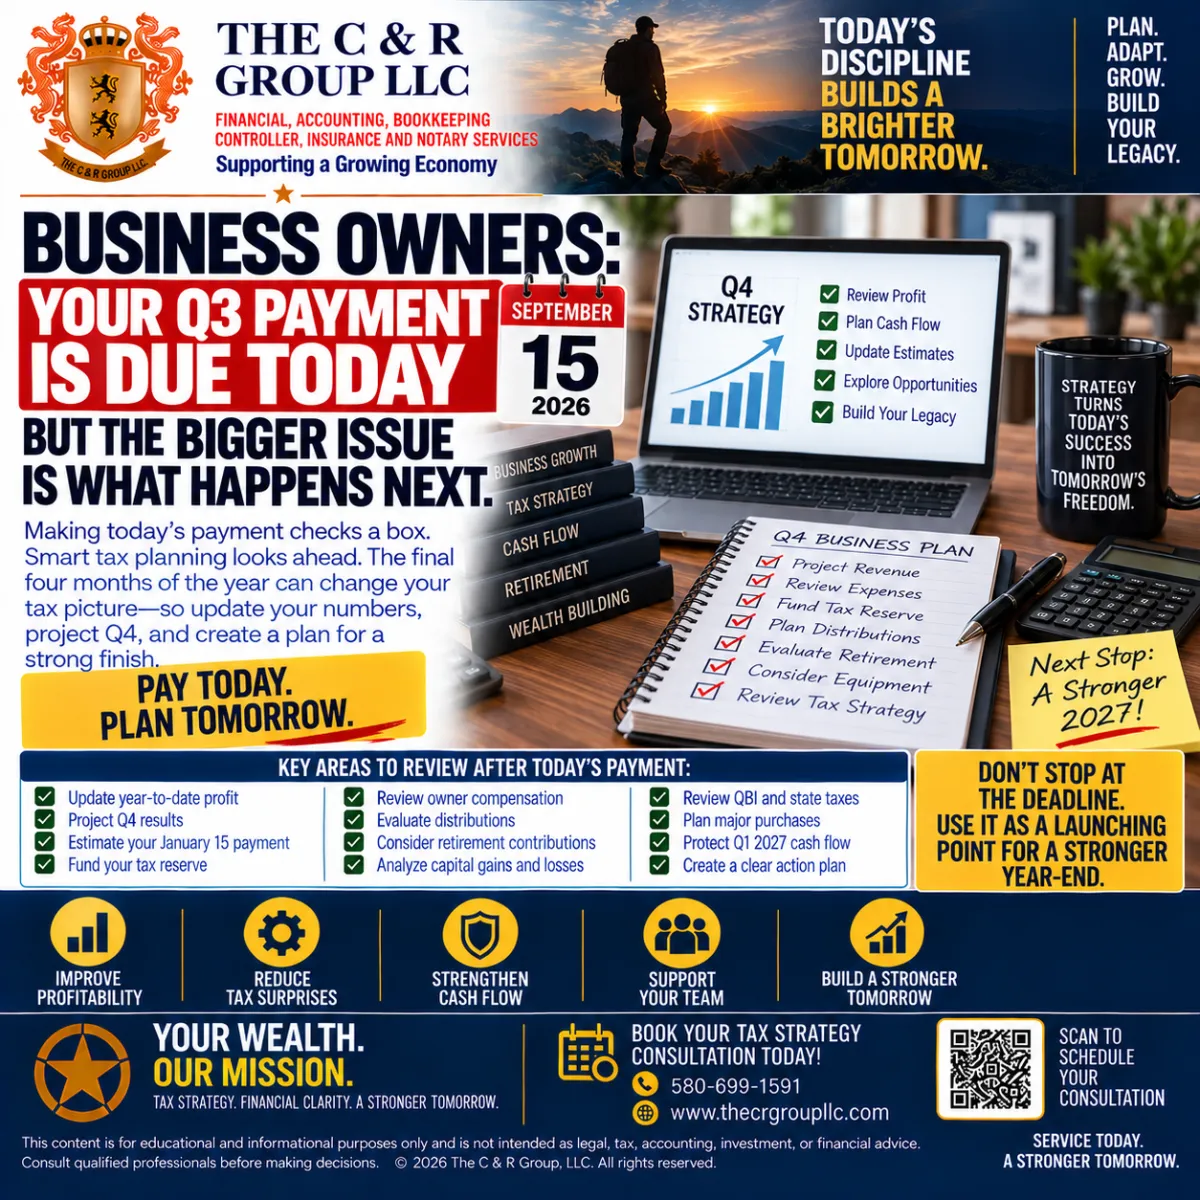
Business Owners: Your Q3 Payment Is Due, but the Bigger Issue Is What Happens Next
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
Today is September 15.
For many business owners, independent contractors, investors, and taxpayers with income not fully covered by withholding, that means one thing:
Your third 2026 estimated-tax payment is due today.
For calendar-year individuals, September 15 is the due date for the estimated-tax installment covering the June 1 through August 31 payment period. The IRS also lists September 15 as the third estimated-tax installment date for calendar-year corporations. (IRS)
So yes:
Make the payment.
But then do not close the spreadsheet.
Do not put the tax file back in the drawer.
Do not say:
“Good. Taxes are handled until next year.”
Because they are not.
The more important question begins immediately after today's payment:
What happens next?
September through December can change the entire tax picture.
Your business may have its strongest quarter.
A large contract may close.
You may pay bonuses.
You may purchase equipment.
You may take distributions.
Investment gains may occur.
Your spouse may receive a year-end bonus.
Retirement contributions may change.
And the next general estimated-tax installment for the September 1 through December 31 period is due January 15, 2027. (IRS)
That means today's payment is not the finish line.
It is the starting point for the final tax-planning phase of 2026.
Pay Q3 today. Plan Q4 tomorrow.
1. Today's Payment Is Based on What Already Happened
The September 15 estimated-tax period generally covers:
June 1 through August 31. (IRS)
Those months are over.
The revenue happened.
The profit happened.
The investment gains happened.
Today's payment deals primarily with tax exposure created by financial activity already behind you.
But September 1 through December 31 is still unfolding.
That gives the business owner something valuable:
time.
Time to project.
Time to adjust.
Time to fund.
Time to make better decisions before December 31 closes the door on many current-year planning opportunities.
2. Do Not Confuse “Payment Made” With “Tax Plan Complete”
A business owner makes today's estimated payment:
$15,000
and thinks:
“Great. Taxes are handled.”
Not necessarily.
Suppose the business generates:
January–August profit
$180,000
but expects:
September–December profit
$140,000
Projected annual profit:
$320,000
The Q3 payment does not address all of that future Q4 profit.
Your tax plan needs to continue.
Estimated tax is a pay-as-you-go system. The IRS explains that taxpayers generally must pay tax as income is earned or received through withholding, estimated payments, or both. (IRS)
So the bigger question after today's payment is:
What are the next four months likely to create?
3. Start With Updated Year-to-Date Profit
Business owners should know, as of August 31:
Revenue
$________
Cost of goods sold
$________
Gross profit
$________
Operating expenses
$________
Net profit
$________
Not:
“Sales have been pretty good.”
Not:
“We have money in the bank.”
Actual numbers.
Those numbers tell you where Q4 planning begins.
4. Compare Actual Profit With the January Projection
Suppose January projection:
$150,000 annual profit
Actual profit through August:
$170,000
You have already exceeded the entire original annual estimate.
That means your:
Estimated-tax plan;
tax reserve;
owner-compensation analysis;
retirement strategy;
distribution plan
may all need updating.
The January projection did not fail.
The business changed.
The tax strategy should change with it.
5. Project September Through December
Now forecast Q4.
Contracted revenue
$________
Probable additional revenue
$________
Payroll
$________
Contractor costs
$________
Rent
$________
Insurance
$________
Marketing
$________
Equipment
$________
Other operating expenses
$________
Projected Q4 profit:
$________
Then:
YTD profit
$________
plus
Projected Q4 profit
$________
equals:
Projected full-year profit
$________
That is one of the most important numbers in your year-end plan.
6. Do Not Simply Annualize Eight Months
If profit through August is:
$200,000
you might multiply by:
1.5
and estimate:
$300,000
for the year.
Maybe.
But businesses are seasonal.
Q4 may include:
Holiday demand;
major contract completions;
annual renewals;
bonuses;
insurance costs;
equipment purchases.
A good projection uses the business you actually operate.
Not merely a calculator.
7. Today's Payment Should Trigger the January 15 Forecast
The next general estimated-tax payment period covers:
September 1 through December 31
with payment generally due:
January 15, 2027. (IRS)
That means today is an excellent time to estimate that January payment.
Not the exact dollar.
A planning range.
Low Q4 scenario
January payment estimate:
$________
Expected Q4
$________
Strong Q4
$________
Now you can begin reserving cash.
8. The IRS Lets You Update Estimates When Income Changes
Estimated payments are not required to remain frozen throughout the year.
Publication 505 contains an Amended Estimated Tax Worksheet specifically for taxpayers whose estimated tax changes during the year. For a payment due September 15, the worksheet generally applies 75% of the amended annual estimated tax before subtracting prior estimated payments. (IRS)
That matters because business income rarely behaves perfectly.
If income changes:
Recalculate.
If profit grows:
Recalculate.
If income falls:
Recalculate.
Estimated tax should respond to reality.
9. Build the Q4 Tax Reserve Now
Suppose you project:
Additional January tax payment
$32,000
Do not wait until January 14.
Four months gives you approximately:
$8,000 per month
to reserve.
That is a much different cash-flow problem than:
“We need $32,000 tomorrow.”
Create:
Current tax reserve
$________
January target
$________
Gap
$________
Monthly reserve requirement
$________
That turns a tax bill into a planned business expense.
10. Separate Tax Cash From Operating Cash
The bank account might show:
$250,000.
But that money may already belong to:
Payroll;
vendors;
debt payments;
payroll taxes;
sales tax;
income taxes.
Your checking balance is not the same thing as:
available owner cash.
Create separate mental—or actual—buckets.
Operating reserve
$________
Payroll obligations
$________
Vendor obligations
$________
Tax reserve
$________
Truly discretionary cash
$________
Now you can make better decisions.
11. Review Owner Distributions Before Taking Them
Business owners love distributions.
Understandably.
That is why you built the business.
But Q4 distributions should come after:
tax planning.
Suppose you want:
$75,000 distribution.
Before taking it, ask:
Is Q4 payroll funded?
Is the tax reserve funded?
Are vendors covered?
Is January operating cash protected?
Has shareholder or partner basis been reviewed where relevant?
A distribution should not create a January emergency.
12. Profit and Distribution Are Not the Same Thing
This remains a major misunderstanding.
Suppose your S corporation produces:
$250,000 of taxable pass-through income.
You distribute only:
$100,000.
The taxable income is not necessarily limited to:
$100,000.
Likewise, taking:
$100,000 distribution
does not automatically create:
$100,000 business deduction.
Profit.
Compensation.
Distribution.
Cash.
These are different concepts.
Your Q4 plan should distinguish them.
13. Review S Corporation Owner Compensation
If you are a shareholder-employee:
Review:
W-2 wages YTD
$________
Projected annual wages
$________
Projected business profit
$________
Distributions
$________
If the business dramatically outperformed the original plan:
Reasonable compensation deserves another look.
September leaves time to make appropriate payroll adjustments.
December 29 is a far worse time to start that analysis.
14. Payroll Should Be Part of the Tax Projection
Q4 payroll affects:
Cash flow;
employer payroll taxes;
business deductions;
owner compensation;
employee bonuses.
Project:
Regular payroll
$________
Bonuses
$________
Payroll taxes
$________
Benefits
$________
Then include those amounts in the Q4 profit forecast.
15. Review Employee Bonuses Before Promising Them
Suppose the owner wants to pay:
$50,000 total employee bonuses.
Excellent.
But calculate:
Bonus payroll;
employer taxes;
operating cash;
January obligations.
A bonus program should reward employees without accidentally starving the business of Q1 working capital.
Plan the economics before making promises.
16. Review Retirement Contributions
A profitable year can create an opportunity to accelerate retirement savings.
Possible business plans may include:
401(k);
Solo 401(k);
SEP IRA;
SIMPLE IRA;
other qualified plans.
But the objective should not be:
“How do we dump money somewhere to avoid taxes?”
The better question:
“Does additional retirement funding support the owner's long-term plan, and what does it do to the current tax projection?”
Run both scenarios.
17. Run the Retirement Contribution Scenario
For example:
Scenario A
No additional retirement contribution.
Projected taxable income:
$________
Projected tax:
$________
Scenario B
Additional qualifying contribution:
$________
Projected taxable income:
$________
Projected tax:
$________
Then consider:
Tax savings;
cash required;
retirement benefit;
employee obligations.
A tax deduction is only one part of the decision.
18. Review Major Equipment Purchases
Q4 is when many business owners start hearing:
“Buy equipment before December 31 to save taxes.”
Maybe.
If you actually need the equipment.
Suppose you were already planning:
$80,000 machinery purchase.
Now evaluate:
Timing;
financing;
cash flow;
placed-in-service requirements;
available depreciation treatment.
That is good planning.
19. Do Not Spend $100 to Save $30
This deserves its own section.
Business owner:
“I need more write-offs.”
So they spend:
$100,000
on something the business did not need.
Even if the expense or deduction ultimately reduces tax significantly:
The business still spent:
$100,000.
A tax deduction reduces taxable income.
It does not magically reimburse every dollar spent.
Do not make the company poorer to make the tax return look prettier.
20. Review Fixed Assets Now
Update the asset list:
Equipment;
computers;
furniture;
vehicles;
machinery;
improvements.
For each:
Cost
$________
Purchase date
________
Placed-in-service date
________
Business-use percentage
________
Your year-end depreciation estimate cannot be accurate if the fixed-asset records are incomplete.
21. Review Capital Gains Outside the Business
The business owner's personal tax return may also contain:
Stock gains;
dividends;
interest;
cryptocurrency gains;
rental income.
Do not project:
business tax
in isolation from:
household tax.
Suppose business profit:
$250,000
and personal long-term gains:
$75,000.
That investment activity can materially change the household tax picture.
22. Review Capital Losses
Track:
Realized losses
$________
Unrealized losses
$________
Carryforward
$________
Losses may offset capital gains under applicable rules.
But do not sell investments simply to manufacture a tax result.
Investment strategy first.
Tax awareness always.
23. Review NIIT Exposure
Higher-income business owners may also have:
dividends;
interest;
capital gains;
passive rental income.
That may create exposure to the:
3.8% Net Investment Income Tax
depending on household income and the character of the income.
A successful business year can indirectly change investment-tax consequences.
The return works as one system.
24. Review QBI
Qualified Business Income planning deserves another look after Q3.
Why?
Because the calculation may depend on:
taxable income;
business type;
W-2 wages;
qualified property;
capital gains;
other limitations.
A January estimate built around:
$120,000 profit
may be meaningless when the business is now projected to earn:
$350,000.
Run QBI using updated numbers.
25. Review Charitable Giving
If you intend to make substantial Q4 charitable gifts:
Plan now.
Especially when:
Appreciated securities;
donor-advised funds;
significant noncash property
may be involved.
Do not wait until the final week of December.
Complex transfers take time.
And selling appreciated assets before discussing charitable goals can eliminate potential planning choices.
26. Review Accounts Receivable
Business profit does not always equal cash.
Suppose:
Profit
$300,000
but:
Accounts receivable
$180,000
That means a large portion of economic activity has not yet turned into cash.
Tax obligations and accounting-method rules can complicate this further.
At minimum:
Know your AR.
Current
$________
30+ days
$________
60+
$________
90+
$________
A tax strategy that ignores collections can create a liquidity problem.
27. Accelerate Collections for Business Reasons, Not Just Taxes
The final quarter is an excellent time to tighten collections.
Not because every collection necessarily produces a favorable tax result.
Because:
cash flow matters.
A profitable business with poor collections may struggle to:
pay taxes;
fund payroll;
invest;
distribute cash.
Financial strength begins with turning revenue into cash.
28. Review Accounts Payable
Also know:
Vendor obligations
$________
Credit cards
$________
Payroll liabilities
$________
Taxes payable
$________
Debt obligations
$________
A large bank balance means far less when large liabilities sit behind it.
29. Review Business Debt
Separate:
Principal
from
Interest.
If the business pays:
$10,000 monthly loan payment
the entire $10,000 is not necessarily an ordinary business-interest deduction.
Understanding debt service is essential for:
tax projection;
cash-flow planning.
30. Review State Taxes
Federal estimated tax is only one piece.
Business owners may also face:
state income tax;
franchise tax;
entity-level taxes;
payroll taxes;
sales-tax obligations.
If profit increased:
State-tax exposure may increase too.
Do not fund the federal reserve while ignoring the state bill.
31. Review Multi-State Activity
Did you:
hire remote employees?
serve clients in new states?
open another location?
move your headquarters?
perform services across state lines?
That can create:
nexus;
filing requirements;
withholding obligations;
apportionment issues.
Business expansion can create tax obligations long before the owner realizes it.
Q4 is a good time to identify them.
32. Review Sales-Tax Compliance
Sales tax collected from customers is not:
business profit.
Reconcile:
Collected
$________
Remitted
$________
Payable
$________
Do not spend money that belongs to the taxing authority.
That lesson becomes particularly important when Q4 sales surge.
33. Review Payroll-Tax Compliance
Confirm:
Federal payroll deposits;
state withholding;
unemployment taxes;
payroll filings.
Income-tax strategy does not compensate for payroll-tax problems.
Compliance comes first.
Strategy builds on top of it.
34. Review Contractor Records
Before January:
Make sure contractors have:
Valid W-9s;
correct names;
tax identification information;
properly recorded payments.
Do not wait until information-return season to chase people you paid nine months earlier.
Q4 preparation starts now.
35. Review Your Entity Structure—but Do Not Panic-Change It
A business that expected:
$40,000 profit
and is now projected at:
$250,000
may deserve an entity review.
But:
Do not change entities because of one social-media video promising:
“Pay zero taxes with an S corp.”
Evaluate:
Payroll;
reasonable compensation;
administrative costs;
state rules;
timing;
long-term plans.
A structure should solve a real problem.
36. Review Planned Owner Purchases
If the owner intends to use business cash for:
Home purchase;
vehicle;
travel;
investments;
personal debt payoff;
first determine:
How will the cash reach the owner?
Wages?
Distribution?
Loan?
Reimbursement?
Different methods can have different accounting and tax implications.
Do not blur business and personal money.
37. Review Accountable-Plan Reimbursements Where Applicable
If an owner or employee pays legitimate business expenses personally, an appropriately structured accountable reimbursement arrangement may deserve review.
Documentation matters.
Business purpose matters.
Receipts matter.
Do not wait until December to recreate nine months of expenses from memory.
38. Review Home-Office Facts
For business owners who legitimately use part of the home for business:
Review:
Exclusive use;
regular use;
business purpose;
applicable taxpayer/entity structure.
Do not simply calculate:
“20% of my house is deductible.”
Home-office treatment depends on facts and business structure.
Get the mechanics right.
39. Review Vehicle Records
Before year-end:
Check mileage logs.
Business miles
________
Total miles
________
Vehicle expenses
$________
Business-use percentage
________
December is not the time to reconstruct January mileage by scrolling through your calendar and hoping for divine intervention.
Maintain contemporaneous records.
40. Review Travel and Meal Documentation
Business travel and meal deductions require:
Business purpose;
appropriate substantiation.
Review now.
Do not let legitimate deductions disappear because the documentation is poor.
A good strategy without documentation is just an interesting theory.
41. Review the Household Withholding Picture
Business owners often have spouses receiving W-2 income.
Suppose:
Spouse wages
$130,000
Federal withholding
$20,000
Additional withholding through remaining paychecks may potentially be one tool for addressing household tax exposure.
The IRS notes that employees may increase withholding by filing a new Form W-4 rather than relying solely on estimated payments. (IRS)
Run the numbers before deciding.
42. Safe Harbor Is Still Not the Same as Full Funding
The general IRS estimated-tax rule says individuals typically must make estimated payments if they expect to owe at least $1,000 after withholding and credits and expected payments fall below the smaller of 90% of current-year tax or generally 100% of prior-year tax, subject to special rules for certain taxpayers. (IRS)
But meeting that requirement does not necessarily mean:
“Nothing will be due in April.”
You can satisfy a safe harbor and still owe a large balance.
Business owners should plan for:
compliance
and
cash.
43. Underpayment Can Be Measured by Payment Period
The IRS notes that if you do not pay enough tax by the due date for a particular payment period, a penalty can apply even if the final return ultimately shows a refund. (IRS)
That is why estimated-tax timing matters.
You cannot always repair every earlier payment-period issue simply by making one huge payment later.
44. Uneven Income May Require a Different Analysis
Some businesses do not earn income evenly.
Maybe:
Q1 profit
$15,000
Q2
$30,000
Q3
$150,000
If income is highly uneven, the annualized income installment method may deserve review when calculating estimated-tax penalty exposure.
Publication 505 points taxpayers to the annualized-income method for situations where income varies during the year. (IRS)
That is particularly relevant for seasonal businesses.
45. Do Not Automatically Assume Four Equal Payments Are Optimal
Estimated taxes are often described as:
quarterly.
That can lead people to think:
Four equal checks.
But the IRS payment periods themselves are not equal calendar quarters, and income can vary throughout the year. (IRS)
Your strategy should reflect:
income timing;
withholding;
applicable estimated-tax rules.
46. The Next Four Months Should Have a Tax Calendar
Create one now.
September
Make Q3 payment.
Update projection.
Fund tax reserve.
October
Review business profit.
Review retirement.
Review investment gains/losses.
November
Update Q4 forecast.
Finalize charitable planning.
Review major purchases.
December
Execute appropriate year-end actions.
Confirm tax reserve.
Update January payment.
January 15
Make Q4 estimated payment if required.
Now tax planning becomes an operating rhythm.
47. Schedule Monthly P&L Reviews
From now through December:
September 30
Close the month.
October 31
Close the month.
November 30
Close the month.
Then:
Update projected annual profit after each close.
Business owners should not enter January still wondering:
“How much money did we make last year?”
Know before the year ends.
48. Measure the Tax Gap Monthly
Create this simple formula:
Projected total tax – projected tax payments = projected tax gap
Example:
Projected federal tax:
$85,000
Projected withholding:
$25,000
Estimated payments:
$40,000
Projected remaining gap:
$20,000
Then compare:
Tax reserve:
$12,000
Reserve shortage:
$8,000
Now the action is obvious.
49. Protect Q1 2027 Before Taking Year-End Cash
Q4 success creates temptation:
big year-end distribution.
Before doing that, project:
January payroll
$________
January vendors
$________
Debt payments
$________
January estimated tax
$________
Minimum operating reserve
$________
Then decide what is safely distributable.
Do not start 2027 broke because 2026 looked profitable.
50. Know the Difference Between Tax Minimization and Wealth Building
This is the most important business-owner lesson in the article.
Your mission is not merely:
Pay the least tax possible this year.
Your larger mission is:
Build more after-tax wealth over time.
Sometimes that means:
Taking a legitimate deduction.
Funding retirement.
harvesting a loss.
accelerating an appropriate expense.
Sometimes it means:
Paying the tax;
keeping cash;
avoiding unnecessary spending;
maintaining business liquidity.
A lower tax bill does not automatically mean a stronger business.
Illustrative Case Study: The Owner Who Paid Q3 and Stopped Thinking
Meet:
Marcus
Marcus owns a successful service company taxed as an S corporation.
January projection:
Annual revenue
$750,000
Annual profit
$175,000
Estimated payments were built around that forecast.
September 15
Marcus makes his scheduled Q3 payment:
$12,000
He thinks:
“Good. Taxes handled.”
But the books show something else.
Actual Through August
Revenue
$680,000
Expenses
$430,000
Profit
$250,000
He has already exceeded the original full-year profit projection by:
$75,000
And four months remain.
Q4 Forecast
Signed contracts:
$260,000
Expected Q4 expenses:
$155,000
Projected Q4 profit:
$105,000
Projected annual profit:
$355,000
Original:
$175,000
Difference:
+$180,000
That should change the conversation.
Marcus's Household Also Has Other Income
Spouse wages:
$95,000
Dividends:
$10,000
Long-term capital gain:
$35,000
Now the household tax plan is materially different from January.
What Happens If Marcus Stops Planning Today?
Q4 arrives.
He sees strong cash.
He takes:
$100,000 owner distribution.
Buys:
$60,000 vehicle
mostly because someone tells him:
“It's a write-off.”
Pays:
$25,000 employee bonuses.
January arrives.
Tax adviser calculates a major remaining tax liability.
Business cash is tight.
Marcus asks:
“How can I owe this much? I made all four tax payments.”
Because the payments were based on:
an outdated profit projection.
The Better Version
Marcus makes today's Q3 payment.
Then immediately runs the new projection.
Projected annual profit:
$355,000
Household income:
Updated.
Federal tax:
Updated.
State tax:
Updated.
January payment:
Estimated.
Tax reserve:
Increased.
Step 1 — Protect the Tax Reserve
Marcus moves:
$________
into a dedicated tax account.
Step 2 — Protect Q1 Operating Cash
He calculates:
Payroll
$________
Vendors
$________
Debt
$________
January taxes
$________
before determining his distribution.
Step 3 — Review the Distribution
Instead of blindly taking:
$100,000
he evaluates:
$________
based on the actual available surplus.
Step 4 — Review the Vehicle
Does the company actually need:
$60,000 vehicle?
If yes:
Review tax treatment.
If no:
Do not spend $60,000 chasing a deduction.
Step 5 — Review Retirement
Marcus already wanted to increase retirement savings.
Now the adviser models appropriate plan contributions.
Business objective:
retirement wealth
Tax benefit:
secondary advantage.
Step 6 — Review Investment Gains
The household's $35,000 capital gain enters the projection.
Available capital losses are reviewed.
NIIT is reviewed where applicable.
Result
Marcus still has a successful year.
He may still:
Take a distribution;
buy equipment;
fund retirement;
pay bonuses.
The difference?
He does them with:
the tax bill already visible.
That is the bigger issue after September 15.
The Post-Q3 Business Owner Dashboard
BUSINESS
Revenue YTD:
$________
Profit YTD:
$________
Projected Q4 profit:
$________
Projected annual profit:
$________
OWNER
W-2 wages:
$________
Distributions:
$________
Projected additional distributions:
$________
HOUSEHOLD
Spouse wages:
$________
Investment income:
$________
Capital gains:
$________
Other income:
$________
TAX
Federal withholding:
$________
Q1 estimate:
$________
Q2 estimate:
$________
Q3 estimate:
$________
Projected January payment:
$________
Projected state tax:
$________
CASH
Operating reserve:
$________
Tax reserve:
$________
January cash requirement:
$________
Available discretionary cash:
$________
Q4 STRATEGY
Owner compensation.
Distributions.
Retirement.
Equipment.
Capital gains/losses.
Charity.
QBI.
State taxes.
January estimate.
That dashboard should be updated monthly.
Post-Payment Checklist for Business Owners
You made the Q3 payment.
Good.
Now:
Record the payment in your tax file.
Update the YTD P&L.
Project Q4 revenue.
Project Q4 expenses.
Calculate projected annual profit.
Update household income.
Review federal withholding.
Review capital gains.
Review estimated January payment.
Fund tax reserve.
Review owner wages.
Review distributions.
Review retirement.
Review equipment.
Review QBI.
Review state taxes.
Project Q1 2027 cash.
If you stop after the first box:
You missed the bigger message.
Business Owner Q4 Readiness Score
Give yourself one point for each YES.
Q3 estimated payment completed.
YTD books reconciled.
YTD profit known.
Q4 revenue projected.
Q4 expenses projected.
Full-year profit projected.
Owner compensation reviewed.
Distributions reviewed.
Capital gains included.
Retirement reviewed.
QBI reviewed.
State taxes projected.
January payment estimated.
Tax reserve funded.
Q1 cash protected.
13–15 YES
GREEN — Q4 Mission Ready
8–12 YES
YELLOW — Payment Made, Planning Incomplete
0–7 YES
RED — Q3 Payment Is the Least of Your Problems
If you are red:
The answer is not panic.
It is:
get the numbers.
AI-Search Quick Answers
Is the third individual estimated-tax payment due September 15, 2026?
Yes. For calendar-year individuals, the third 2026 estimated-tax installment is due September 15 and generally covers income from June 1 through August 31. (IRS)
When is the next individual estimated-tax payment due?
The next general installment, covering September 1 through December 31, is due January 15, 2027. (IRS)
Can estimated-tax payments be changed during the year?
Yes. IRS Publication 505 provides an amended estimated-tax worksheet for taxpayers whose projected annual tax changes during the year. (IRS)
Who generally may need estimated tax?
Estimated tax may be required when tax is not sufficiently covered by withholding. Common income sources include self-employment income, interest, dividends, rents, and capital gains. (IRS)
What is the general estimated-tax rule for individuals?
In most cases, taxpayers generally need estimated tax when they expect to owe at least $1,000 after withholding and credits and those payments are less than the smaller of 90% of current-year tax or generally 100% of prior-year tax, subject to special rules. (IRS)
Can insufficient estimated payments create a penalty even if I later receive a refund?
Yes. The IRS states that an underpayment penalty may apply when insufficient tax was paid by a payment-period deadline even if the final return ultimately results in a refund. (IRS)
Can wage withholding be increased instead of relying solely on estimates?
Potentially yes. Employees can generally request additional withholding by filing a new Form W-4. (IRS)
What if business income is uneven throughout the year?
The annualized-income installment method may deserve review when income is received unevenly during the year. (IRS)
30 Questions Business Owners Should Answer After Today's Payment
Did I make my Q3 payment?
Was the amount based on updated numbers?
What is YTD revenue?
What is YTD profit?
Are my books reconciled?
What Q4 revenue is already contracted?
What Q4 revenue is probable?
What Q4 expenses remain?
What is projected annual profit?
How different is that from January?
What owner wages have been paid?
Are owner wages still reasonable based on current facts?
What distributions have I taken?
What additional distributions are planned?
What federal withholding exists?
What capital gains occurred?
What capital losses exist?
Could NIIT apply?
Does QBI need review?
Is retirement funding on track?
Are major purchases planned?
Does the business actually need them?
Is charitable giving planned?
What state taxes are projected?
What is the estimated January payment?
How much is already in the tax reserve?
How much more needs to be reserved?
What cash does Q1 2027 require?
How much cash can safely leave the business?
Now that Q3 is paid, what is my plan for everything that happens between today and December 31?
That final question is today's real tax question.
What to Do Next
Make today's payment.
Then build your Q4 Tax Command Plan.
CURRENT POSITION
YTD income:
$________
YTD business profit:
$________
Taxes paid:
$________
Tax reserve:
$________
Q4 FORECAST
Revenue:
$________
Expenses:
$________
Projected profit:
$________
Investment activity:
$________
FULL-YEAR PROJECTION
Projected taxable income:
$________
Projected federal tax:
$________
Projected state tax:
$________
JANUARY PAYMENT
Projected:
$________
TAX RESERVE
Current:
$________
Target:
$________
Gap:
$________
DECISIONS
Owner compensation:
________________
Distribution:
________________
Retirement:
________________
Equipment:
________________
Investments:
________________
Charity:
________________
NEXT REVIEW DATE
________________
Do not leave that blank.
What gets scheduled gets reviewed.
Final Thought
Today is payment day.
Make the payment.
Meet the obligation.
Then move forward.
Because the strongest business owners understand something important:
Quarterly deadlines should create quarterly discipline.
Your September 15 payment tells you what the first eight months created.
Your Q4 plan determines what happens next.
Maybe the business grows even faster.
Good.
Maybe profits decline.
Adjust.
Maybe a new contract closes.
Update the projection.
Maybe an investment is sold.
Include it.
Maybe you fund retirement.
Model it.
Maybe you take a large distribution.
Protect the tax reserve first.
The objective is not to perfectly predict December 31.
It is to stop operating blind.
So today's sequence should be:
Pay.
Update.
Project.
Reserve.
Strategize.
Execute.
Then repeat.
Because filing season should not be the first time you discover how successful—or expensive—the year became.
By then, the decisions are already history.
Today you still have:
time.
And time is one of the most valuable tax-planning tools available.
Your Q3 payment is due today.
But the bigger issue is what you do tomorrow.
Book Your Q4 Business Tax Strategy Consultation
If your business has grown, profits changed, distributions increased, investments produced gains, or today's Q3 payment was based on numbers calculated months ago, now is the time to update the projection.
We can review:
Year-to-date P&L;
projected Q4 profit;
estimated taxes;
January 15 payment planning;
owner compensation;
distributions;
tax reserves;
capital gains;
QBI;
retirement-plan strategies;
equipment purchases;
state-tax exposure;
Q1 2027 cash requirements.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.