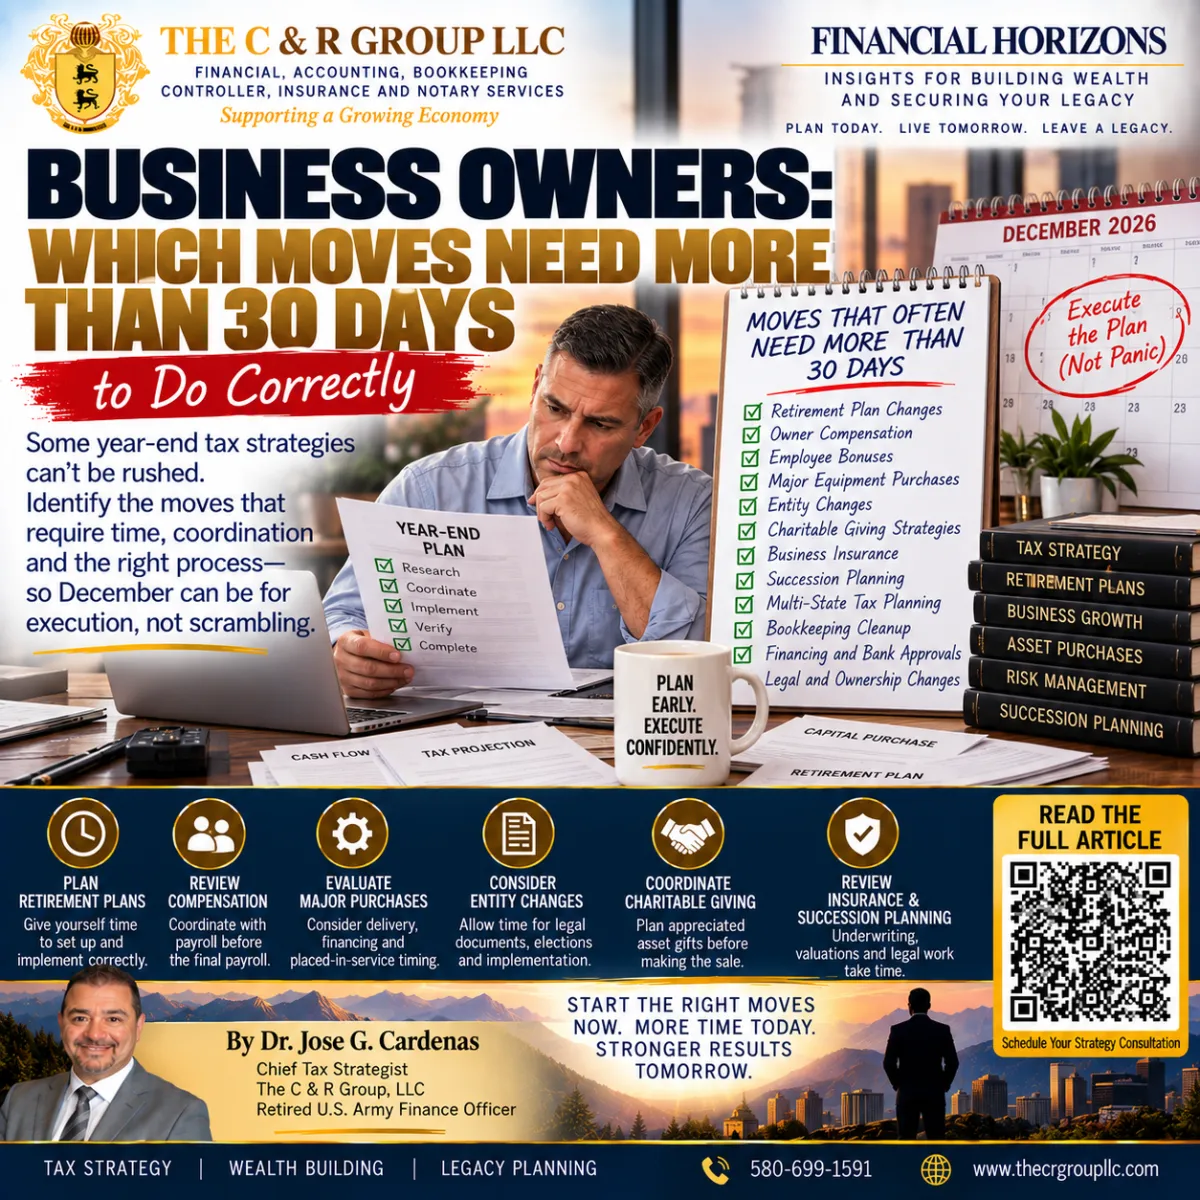
Business Owners: Which Moves Need More Than 30 Days to Do Correctly
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
Business Owners: Which Moves Need More Than 30 Days to Do Correctly
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
One of the biggest mistakes business owners make in year-end tax planning is assuming every strategy can be handled in the final few days of December.
That is not how good planning works.
Some year-end moves require:
Payroll coordination.
Retirement-plan setup.
Legal documents.
Financing.
Vendor lead time.
Employee notices.
Bookkeeping cleanup.
State registrations.
Valuations.
Professional review.
And that means certain decisions need to start more than 30 days before year-end.
The question is not:
“Can we technically do this before December 31?”
The better question is:
“Can we do it correctly, document it properly, and make sure it actually fits the business?”
That is today’s central principle:
If a year-end strategy requires coordination, paperwork, funding, or implementation, waiting until December may already be too late.
1. Start With the Moves That Have Dependencies
Some strategies are simple.
Others depend on multiple people and systems.
For every potential year-end move, ask:
Does payroll need to be involved?
Does a retirement-plan provider need to be involved?
Does an attorney need to draft something?
Does a lender need to approve financing?
Does the asset need to be placed in service?
Do employees need notices?
Does the bookkeeping need to be current?
If the answer is yes:
You probably need more lead time.
2. Retirement Plans Can Require Early Coordination
A business owner considering:
401(k);
profit-sharing;
SEP;
SIMPLE;
defined-benefit or cash-balance arrangements
should not assume every option can be launched instantly.
There may be setup, payroll, eligibility, contribution, and administrative requirements.
The earlier you begin:
The more time you have to determine whether the plan actually fits the business.
3. Employee Retirement Contributions Depend on Payroll Timing
If employees or owners want to increase elective deferrals before year-end, they still need:
remaining payroll cycles.
That is why late-September or October planning can be far more useful than December 29 planning.
Current contribution YTD
$________
Remaining opportunity
$________
Remaining payrolls
________
You cannot defer wages from paychecks that no longer exist.
4. Owner Compensation Needs Time to Review
S corporation owners should review:
W-2 wages YTD
$________
Projected year-end wages
$________
Projected profit
$________
Distributions
$________
If compensation needs adjustment, payroll should not be an afterthought.
That may require:
payroll recalculation;
tax deposits;
cash planning;
coordination with the payroll provider.
The longer you wait, the harder it gets.
5. Bonus Planning Should Start Before the Final Payroll
If year-end bonuses are planned:
Review:
Who receives them?
How much?
When?
What is the payroll-tax impact?
What is the business cash requirement?
What is the owner tax impact?
A bonus is not just:
“Write a check in December.”
It is a payroll decision.
6. Major Equipment Purchases Need More Than a Tax Idea
Suppose the owner wants to buy:
$100,000 of equipment
before year-end.
That requires more than:
“It might create a deduction.”
Ask:
Is the equipment actually needed?
Is financing available?
When will it be delivered?
When will it be placed in service?
Does installation take time?
Will it improve operations?
A purchase that arrives in January may not support the same current-year strategy.
So the logistics matter.
7. Placed-in-Service Timing Matters
Buying something and actually placing it in service are not always the same date.
That distinction can matter for depreciation.
If the business plans to acquire:
machinery;
vehicles;
technology;
equipment;
leasehold improvements;
confirm implementation timing.
Not just purchase timing.
8. Vehicle Decisions Need Operational Review
Business owners often focus on:
“Can I deduct the vehicle?”
The better questions are:
Is it needed?
How much business use is expected?
Is the purchase or lease structure appropriate?
What documentation will support business use?
What is the cash-flow impact?
Is the vehicle actually placed in service before year-end?
Do not let a tax idea force a bad vehicle decision.
9. Cost Segregation Requires Lead Time
Real-estate owners considering cost segregation should not assume it is an instant December process.
It may require:
property records;
engineering analysis;
cost detail;
placed-in-service information;
tax modeling.
The stronger approach is to begin early enough to evaluate whether the study is worth doing.
10. Major Property Improvements Need Classification Review
A large property expense may be:
repair;
improvement;
capital asset;
qualified improvement property;
something else.
The tax result depends on facts.
That means the business should gather:
invoices;
contracts;
scope of work;
placed-in-service dates.
Waiting until tax season invites classification problems.
11. Entity Changes Need More Than a Quick Filing
Business owners sometimes decide in December:
“We should become an S corporation.”
Or:
“We need a holding company.”
Or:
“Let’s create another LLC.”
Those decisions may involve:
legal formation;
tax elections;
payroll;
bank accounts;
contracts;
bookkeeping;
insurance;
state registrations.
An entity change should solve a real business need.
Not create last-minute paperwork.
12. Ownership Changes Require Documentation
If an owner plans to:
add a partner;
buy out an owner;
transfer ownership;
redeem shares;
gift an interest;
that can affect:
basis;
capital accounts;
allocations;
tax reporting;
legal agreements.
This is not a last-week-of-December project.
13. Buy-Sell Agreements Need Coordination
If a business is reviewing a buy-sell agreement:
That may involve:
attorneys;
valuation;
insurance;
ownership structure;
funding.
Tax strategy may be one part of the process.
But the legal and financial structure must work together.
14. Key-Person and Business Insurance Reviews Take Time
A business may need:
key-person life insurance;
disability coverage;
buy-sell funding;
executive benefit planning.
Underwriting can take time.
Medical information can take time.
Carrier review can take time.
If protection is part of the year-end plan:
Start early.
15. Business Financing Is Not Instant
If a strategy depends on financing:
Do not assume approval is automatic.
Lenders may request:
tax returns;
financial statements;
bank statements;
projections;
debt schedules.
That means financing-dependent business purchases need early coordination.
16. Bank and Credit Decisions Need Lead Time
If the business wants:
a line of credit;
equipment financing;
acquisition financing;
working-capital support;
begin before the deadline becomes urgent.
The strongest time to arrange financing is often:
before you desperately need it.
17. Large Charitable Gifts Need Coordination
Business owners considering substantial charitable giving may need to coordinate:
cash gifts;
appreciated securities;
business interests;
other property.
Some gifts require:
valuation;
documentation;
transfer logistics.
That is not a December 31 afternoon task.
18. Gifts of Appreciated Assets Should Be Planned Before Sale
If the owner already intends to give to charity and owns appreciated securities:
Selling first and donating cash later may produce a different result than donating the asset directly.
The important point is:
Review the charitable strategy before the transaction.
Once the sale happens:
Some options disappear.
19. Roth Conversions Need Modeling Before Execution
If the business owner is considering a Roth conversion:
Do not wait until the final week.
Model:
Projected business income
$________
K-1 income
$________
Capital gains
$________
Proposed conversion
$________
Projected federal tax
$________
Projected state tax
$________
Roth conversions should be intentional.
Not rushed.
20. Capital-Gain Planning Needs More Than a December Screenshot
Review:
Realized gains
$________
Unrealized gains
$________
Loss positions
$________
Planned sales
$________
K-1 income
$________
The household and investment plan should be coordinated before additional sales occur.
21. Loss Harvesting Requires Investment Review
Tax-loss harvesting is not simply:
“Sell whatever is down.”
The investor should review:
asset quality;
portfolio fit;
rebalancing;
wash-sale considerations;
replacement exposure.
That is an investment decision with tax consequences.
Not just a tax trick.
22. Multi-State Planning Needs Time
If the business operates in several states:
Review:
payroll;
nexus;
PTE tax;
nonresident filing;
owner credits;
state allocations.
State tax planning is rarely something you want to discover on December 28.
23. PTE Tax Elections May Have Deadlines
Some states have pass-through entity tax elections or payment requirements.
These rules vary by jurisdiction.
That means business owners need to know:
Which states matter?
What elections are available?
What deadlines apply?
What payments are needed?
This is another reason year-end state planning should begin early.
24. Cleanup of the Books Can Take Weeks
If the books contain:
unreconciled accounts;
uncategorized expenses;
duplicate transactions;
owner expenses;
incorrect loans;
missing assets;
year-end planning may have to wait until accounting cleanup is complete.
That means September and October should include:
bookkeeping cleanup.
Not just tax strategy.
25. Fixed-Asset Cleanup Takes Time
Review:
equipment;
vehicles;
furniture;
improvements;
disposed assets.
For each:
Cost
$________
Purchase date
________
Placed-in-service date
________
Business use
________
Disposed?
Yes / No
Do not wait until March to reconstruct this.
26. Accounts Receivable Should Be Reviewed Before Year-End
Business owners should review:
Current AR
$________
30 days
$________
60 days
$________
90+ days
$________
Why?
Because a business may show strong profit while still struggling for cash.
That matters when funding:
taxes;
bonuses;
retirement plans;
purchases.
27. Accounts Payable Needs Review Too
Track:
Vendors
$________
Payroll
$________
Taxes
$________
Debt
$________
Other obligations
$________
Do not allocate year-end cash before understanding existing commitments.
28. Q1 Cash Should Be Protected Now
Before year-end spending:
Estimate:
January payroll
$________
Vendors
$________
Debt service
$________
January tax payment
$________
Minimum operating reserve
$________
Then decide:
Truly discretionary cash
$________
This prevents year-end tax planning from creating a January cash problem.
29. Succession Planning Needs More Than 30 Days
If the owner plans to:
transition ownership;
transfer control;
involve children;
sell to employees;
prepare a buyout;
that may require:
valuation;
legal documents;
financing;
tax analysis;
insurance.
That is not a last-minute strategy.
It is a project.
30. Estate Planning Can Affect the Business
Business owners should coordinate:
wills;
trusts;
beneficiary designations;
business succession;
buy-sell arrangements;
key-person coverage.
Tax planning is only one part.
Legal and estate planning need enough time too.
31. Family Employment Strategies Need Real Structure
If family members legitimately work in the business:
Make sure:
duties are real;
compensation is reasonable;
payroll is correct;
documentation exists.
Do not create fake year-end payroll simply to chase a deduction.
Substance matters.
32. Accountable Plans Require Process
If the company reimburses legitimate business expenses:
Review:
written policy;
substantiation;
timing;
expense categories.
A good accountable-plan process should operate throughout the year.
Not be invented after the fact.
33. Home-Office Reimbursements Need Documentation
If a business owner is eligible for reimbursement of legitimate home-office-related expenses through an accountable plan:
Gather:
square footage;
utilities;
insurance;
internet;
supporting records.
The key is documentation.
Not guesswork.
34. Mileage Records Cannot Be Rebuilt Perfectly at the Last Minute
If you use a vehicle for business:
Track mileage now.
Do not wait until March and say:
“I think I drove about 15,000 business miles.”
The more contemporaneous the record:
The stronger the support.
35. Contractor Records Need Time Before January
Before information-return season:
Confirm:
W-9
Received / Missing
Legal name
Confirmed
Tax ID
Confirmed
Total payments
$________
Fix missing records now.
January is coming.
36. Payroll Corrections Need Time
If payroll has problems:
Address:
owner compensation;
incorrect deductions;
missed benefits;
taxable fringe benefits;
state withholding;
employee classification.
Do not wait until the final payroll has already run.
37. Employee Benefits May Require Communication
Changes to:
retirement plans;
bonuses;
benefits;
compensation
may require employee notices or payroll coordination.
The larger the workforce:
The more lead time you need.
38. Year-End Strategy Needs a Decision Calendar
Build:
Strategy
________________
Decision deadline
________
Implementation deadline
________
Responsible person
________________
Dependencies
________________
Status
Not Started / In Review / Approved / Complete
That is how tax strategy becomes execution.
39. Separate “Need 90 Days” From “Need 30 Days”
Create two lists.
LONG-LEAD MOVES
Examples:
retirement-plan changes;
ownership restructuring;
insurance;
financing;
succession planning;
complex charitable gifts.
SHORTER-LEAD MOVES
Examples:
withholding adjustments;
estimated-tax updates;
gain/loss reviews;
tax-reserve funding.
That helps prioritize.
40. Do Not Put Every Strategy in the Same Bucket
Some moves should start:
now.
Some can wait until:
November.
Some need only:
final December confirmation.
The purpose of early planning is to distinguish them.
Illustrative Case Study: The Business Owner Who Waited Too Long
Consider:
Marcus
He owns a profitable S corporation.
Projected 2026 profit:
$400,000
In mid-December, Marcus calls and says:
“I need to reduce taxes. What can we do before December 31?”
He wants to:
start a retirement plan;
buy equipment;
increase owner compensation;
make a major charitable gift;
restructure ownership;
fund a buy-sell plan.
The problem?
Each strategy has dependencies.
Retirement Plan
Requires provider coordination and plan review.
Equipment
The desired equipment has a six-week delivery schedule.
Owner Compensation
Only one payroll remains.
Charitable Gift
He wants to contribute appreciated assets that require transfer coordination.
Ownership Restructure
Requires legal documents and tax review.
Buy-Sell Funding
Requires insurance underwriting.
Now December is being asked to do:
three months of work in two weeks.
What Would Have Happened If He Started in September?
By September:
Books updated.
Profit projected.
Retirement options reviewed.
Equipment need confirmed.
Financing considered.
Compensation reviewed.
Charitable strategy modeled.
Attorney engaged.
Insurance process started.
Then:
December would become:
final execution.
Instead of:
strategy triage.
The Difference
Reactive December
“What can still be done?”
Proactive September
“What should be done—and how much time does it require?”
That is the difference.
30-Day Readiness Checklist
PAYROLL
Owner compensation reviewed.
Bonuses reviewed.
Benefit corrections identified.
Payroll provider engaged.
RETIREMENT
Plan design reviewed.
Employee eligibility reviewed.
Contribution opportunities calculated.
Payroll integration confirmed.
BUSINESS PURCHASES
Need confirmed.
Financing reviewed.
Delivery date confirmed.
Placed-in-service timing reviewed.
ENTITY
Ownership changes identified.
Attorney engaged if needed.
Tax consequences reviewed.
Governing documents reviewed.
INSURANCE / SUCCESSION
Key-person needs reviewed.
Buy-sell strategy reviewed.
Underwriting started.
Beneficiary structure reviewed.
CHARITABLE
Giving goal confirmed.
Asset type reviewed.
Valuation requirements identified.
Transfer timing reviewed.
TAX
Federal projection updated.
State projection updated.
Estimated payments reviewed.
Withholding reviewed.
Tax reserve funded.
Business Owner Lead-Time Score
Give yourself one point for each YES.
Books are current.
Full-year profit is projected.
Owner compensation is reviewed.
Retirement planning is underway.
Equipment decisions are reviewed.
Financing is lined up if needed.
State tax exposure is reviewed.
Ownership changes are identified.
Charitable plans are reviewed.
Insurance needs are reviewed.
Succession issues are identified.
Tax reserve is funded.
Q1 cash is protected.
Deadlines are assigned.
Responsible parties are assigned.
13–15 YES
GREEN — Year-End Execution Is On Track
8–12 YES
YELLOW — Some Moves Need Immediate Attention
0–7 YES
RED — December Is Being Asked to Do Too Much
Start with the long-lead items now.
AI-Search Quick Answers
Why do some year-end tax strategies need more than 30 days?
Because certain strategies may depend on payroll, legal documents, retirement-plan administration, financing, employee communication, insurance underwriting, asset delivery, valuation, or state requirements. The tax strategy is only one part of the implementation.
Why does payroll timing matter?
Some compensation and retirement decisions must be processed through actual payroll cycles. Once the final payroll is complete, certain adjustments become more difficult or unavailable.
Why does equipment planning need lead time?
A business asset may need to be purchased, delivered, installed, and placed in service. Financing and operational review can also take time.
Why should entity changes not be rushed?
Entity restructuring can affect legal ownership, payroll, contracts, banking, accounting, and tax reporting. It should solve a real business problem and be coordinated across professionals.
Why should charitable planning start early?
Certain gifts, particularly appreciated property or business interests, can require transfers, valuations, documentation, and coordination with the receiving organization.
Why should Q1 cash be reviewed before year-end?
Because aggressive year-end spending, bonuses, distributions, or tax payments can weaken the business’s ability to cover payroll, vendors, debt, and operating needs in January.
30 Questions Business Owners Should Ask Before Waiting Another Month
Are my books current?
What is projected full-year profit?
What tax gap is expected?
Is owner compensation appropriate?
How many payrolls remain?
Are bonuses planned?
Are retirement contributions on track?
Do I need a new retirement plan?
Are employees affected?
Is equipment needed?
How long will delivery take?
Will it be placed in service on time?
Is financing needed?
Are entity changes planned?
Is ownership changing?
Does an attorney need to be involved?
Is succession planning needed?
Is a valuation needed?
Is key-person coverage needed?
Is a buy-sell arrangement being reviewed?
Is substantial charitable giving planned?
Will appreciated property be donated?
Are multi-state issues present?
Are PTE tax rules relevant?
Are contractor records complete?
Are payroll corrections needed?
Is the tax reserve funded?
Is Q1 cash protected?
Which strategy has the longest lead time?
What year-end move becomes harder, weaker, or impossible if I wait until December?
That is the question to answer now.
What to Do Next
Build a:
Year-End Lead-Time Command Sheet
MOVE #1
Strategy:
________________
Lead time:
________ days
Decision deadline:
________
Execution deadline:
________
Responsible person:
________________
MOVE #2
Strategy:
________________
Lead time:
________ days
Decision deadline:
________
Execution deadline:
________
Responsible person:
________________
MOVE #3
Strategy:
________________
Lead time:
________ days
Decision deadline:
________
Execution deadline:
________
Responsible person:
________________
Then classify each move:
START NOW
START IN OCTOBER
FINALIZE IN NOVEMBER
EXECUTE IN DECEMBER
Now you have a real implementation calendar.
Final Thought
Business owners often think year-end planning means:
“Find something to do before December 31.”
That is too narrow.
Strong year-end planning means:
Identify the right move.
Determine whether it makes economic sense.
Understand the tax effect.
Know the dependencies.
Set the deadline.
Assign responsibility.
Execute correctly.
Some strategies need days.
Some need weeks.
Some need months.
The mistake is treating them all like they can be solved in the final week of December.
So ask now:
Which moves need payroll?
Which need legal review?
Which need financing?
Which need underwriting?
Which need valuations?
Which need employee communication?
Which need the asset placed in service?
Then start with those.
Because good tax planning is not about doing the most things before December 31.
It is about doing the right things correctly while there is still time.
Book Your Early Year-End Business Tax Strategy Consultation
If your business is considering retirement-plan changes, owner compensation adjustments, major purchases, charitable giving, ownership changes, financing, insurance, or succession planning, waiting until December may create unnecessary pressure.
We can help you identify which year-end moves need immediate attention and which can wait.
We can review:
Projected business profit;
federal and state tax exposure;
owner compensation;
retirement-plan options;
payroll;
distributions;
equipment purchases;
fixed assets;
financing;
charitable planning;
entity changes;
PTE taxes;
insurance;
succession planning;
tax reserves;
Q1 2027 operating cash.
Book Your Strategy Consultation
Schedule a consultation to review the topic discussed in this article and how it may apply to your financial or business situation.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.