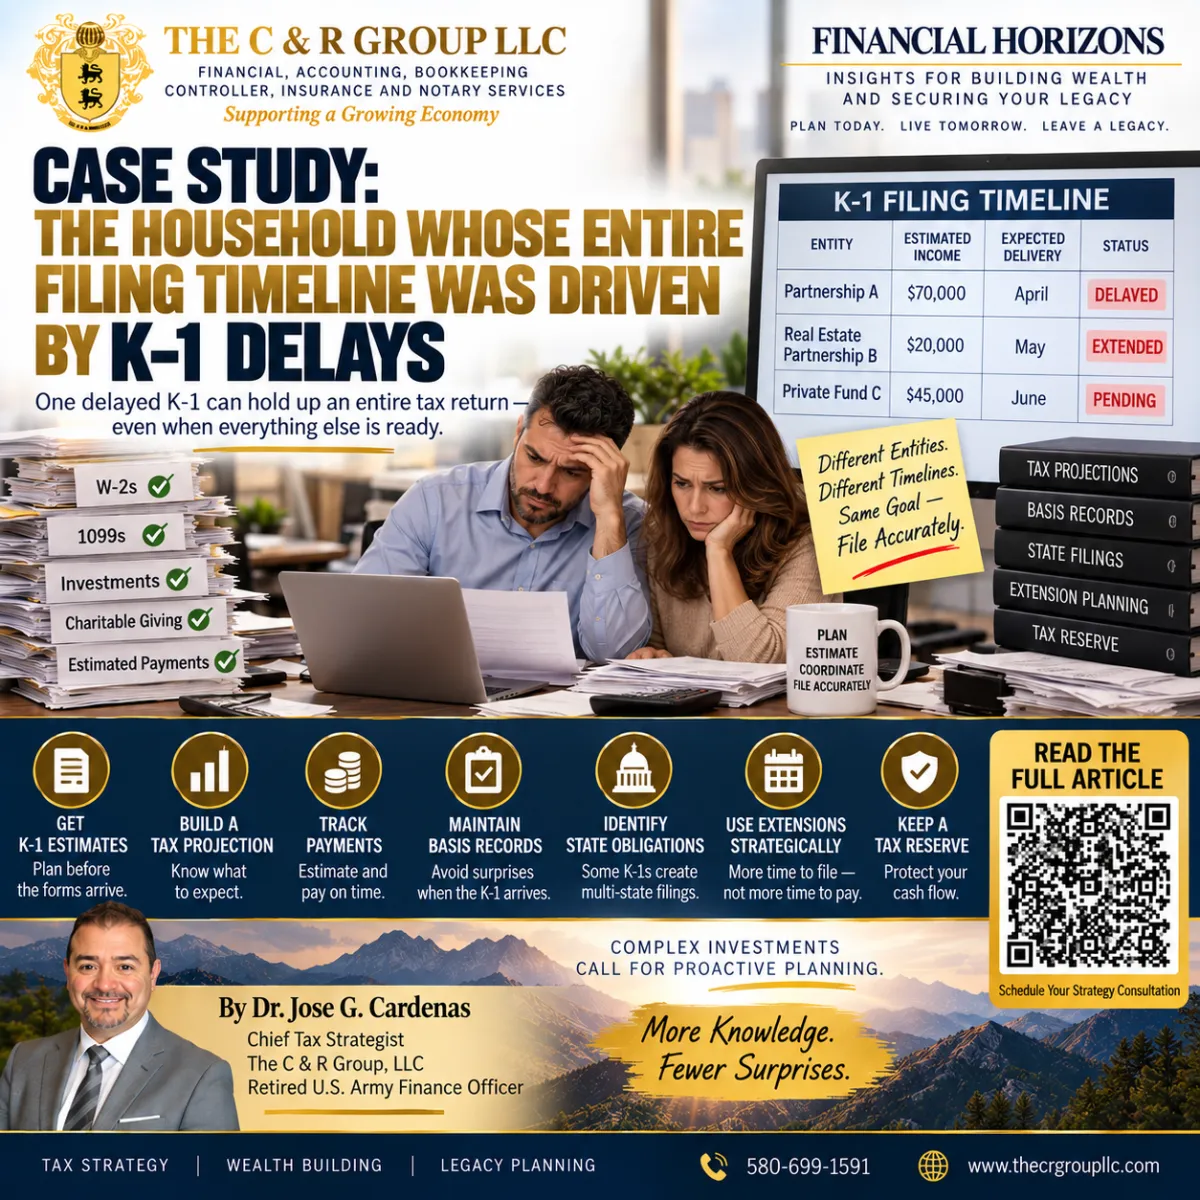
Case Study: The Household Whose Entire Filing Timeline Was Driven by K-1 Delays
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
Case Study: The Household Whose Entire Filing Timeline Was Driven by K-1 Delays
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
Some taxpayers think filing delays happen because their tax professional is slow.
Sometimes the real cause is much simpler:
The household is waiting on information it does not control.
That is especially true when K-1s are involved.
A household may have every W-2.
Every 1099.
Every brokerage statement.
Every charitable receipt.
Every rental schedule.
Every estimated-tax confirmation.
And still be unable to finalize the return.
Why?
Because one K-1 has not arrived.
Then that one delayed K-1 turns out to depend on another K-1.
And suddenly:
One entity controls the entire household filing calendar.
That is exactly what happened in today’s hypothetical case study.
The central principle is:
When K-1s drive the filing timeline, planning has to begin before the forms arrive.
Meet the Household
Our hypothetical household is:
Thomas and Rebecca
Thomas is a senior executive and investor.
Rebecca earns W-2 income.
They also own interests in several pass-through entities.
Their household includes:
Thomas’s wages
$210,000
Rebecca’s wages
$135,000
Investment income
$30,000
Partnership A
Expected K-1 income:
$65,000
Real Estate Partnership B
Expected K-1 income:
$25,000
Private Investment Fund C
Expected K-1 income:
$40,000
Projected major household income:
Approximately:
$505,000
before deductions and other adjustments.
At first glance, their tax situation looked manageable.
Then filing season arrived.
Everything Was Ready—Except the K-1s
By early February, Thomas and Rebecca had already collected:
Both W-2s;
brokerage statements;
mortgage-interest records;
charitable-giving records;
estimated-payment confirmations;
retirement contribution records;
rental-related documentation.
They assumed the return would be ready quickly.
Then came the first delay.
Partnership A Was Waiting on Another Entity
Thomas owned an interest in:
Partnership A.
Partnership A, in turn, owned part of:
Partnership D.
Partnership A could not finalize its own income until Partnership D issued its K-1.
That meant:
Thomas could not receive his final K-1 from Partnership A until Partnership A received its own K-1 from Partnership D.
One delayed form created another delayed form.
Then Real Estate Partnership B Extended
Real Estate Partnership B had:
multiple properties;
depreciation adjustments;
state activity;
year-end property transactions.
Its return was extended.
Thomas and Rebecca were now waiting on:
two major K-1s.
Their household return could not be finalized with confidence.
Private Investment Fund C Added Another Layer
Private Fund C indicated that its final K-1 would likely not be available until later in the filing season.
The household now had:
One K-1 dependent on another K-1.
One real-estate K-1 delayed by entity complexity.
One private-investment K-1 with a later expected delivery date.
The filing timeline was no longer controlled by Thomas and Rebecca.
The Initial Reaction
Thomas said:
“So we just wait?”
Not exactly.
That is the key lesson.
They had to wait to file accurately.
They did not have to wait to plan intelligently.
The First Planning Step: Estimate the K-1s
Instead of using:
$0
for missing K-1s, the household requested estimates.
Partnership A estimated income
$70,000
Real Estate Partnership B
$20,000
Private Fund C
$45,000
Total estimated K-1 income:
$135,000
That was close to the original estimate, but not identical.
Now they had something usable.
The Second Step: Build the Household Projection
They combined:
Thomas wages
$210,000
Rebecca wages
$135,000
Investment income
$30,000
Estimated K-1 income
$135,000
Projected major income:
Approximately:
$510,000
Now they could estimate:
federal liability;
state liability;
tax already paid;
remaining amount due.
The final return still had to wait.
The planning did not.
The Third Step: Review Payments Already Made
They documented:
Federal withholding
$48,000
Estimated tax payments
$30,000
Total federal payments
$78,000
Now they could compare:
projected tax
with
tax already paid.
That allowed them to estimate the payment that should accompany an extension if necessary.
The Filing Extension Was Not the Problem
Thomas initially viewed the extension as:
“A delay.”
But once the household had a current projection, the extension became:
an administrative timing tool.
The IRS makes clear that an extension gives additional time to file, not additional time to pay. Tax generally still needs to be estimated and paid by the original filing deadline. (irs.gov)
That distinction changed their mindset.
They were not postponing tax planning.
They were postponing the final paperwork until accurate information became available.
The Fourth Step: Build a K-1 Delivery Calendar
They created:
Partnership A draft estimate
Received
Partnership A final K-1
Expected:
April
Real Estate Partnership B
Expected:
May
Private Fund C
Expected:
June
State K-1 schedules
Expected after federal K-1s.
Now the household could see:
why the return was delayed
and
what they were waiting for.
The Fifth Step: Create an Open-Item List
The team tracked:
OPEN
Partnership A final K-1;
Partnership B final K-1;
Fund C final K-1;
state allocation schedules;
final basis confirmation.
COMPLETE
W-2s;
investment statements;
estimated-tax ledger;
charitable documentation;
withholding records;
federal extension estimate.
That simple list turned uncertainty into a process.
Then the First Final K-1 Arrived
Partnership A's final K-1 showed:
$82,000
rather than the estimated:
$70,000
Difference:
+$12,000
The household projection was updated.
No panic.
No complete restart.
Just:
Update the model.
Then the Real Estate K-1 Arrived
Real Estate Partnership B had been estimated at:
$20,000 income
The final K-1 showed:
$8,000 loss
At first glance, that looked favorable.
But the next question was:
Can the loss actually be deducted?
That required reviewing:
basis;
at-risk limitations;
passive-activity rules.
The K-1 number was not automatically the deductible amount.
Basis Became Part of the Filing Timeline
Thomas had enough documentation to support:
Beginning basis
$________
Current-year income/loss activity
$________
Distributions
$________
Contributions
$________
But because Real Estate Partnership B had prior-year suspended losses, the basis and passive-activity workpapers had to be updated before the return could be finalized.
The K-1 arrived.
The analysis was not finished.
That is another reason:
K-1 received does not always mean K-1 resolved.
Then Private Fund C Arrived
The final K-1 showed:
Ordinary income
$________
Capital gain
$________
Interest
$________
State allocations
Multiple states
Now the household had another issue.
The federal return was almost ready.
But the state picture was not.
One Federal K-1 Created Several State Questions
Private Fund C had activity allocated among:
State A;
State B;
State C.
Thomas and Rebecca needed to determine:
nonresident filing requirements;
taxes paid on their behalf;
available credits;
whether estimated payments were already made.
That created another delay.
Not because of federal complexity.
Because of state coordination.
The Filing Timeline Kept Moving
Originally expected filing date:
March
Then:
April
Then:
May
Then finally:
June
To Thomas, that initially felt like tax chaos.
But the real question was:
Was the household financially unprepared while the filing date moved?
The answer became:
No.
Because the tax planning had already been done.
Why Their Situation Was Different From a True Filing Crisis
They already knew:
Projected federal tax
$________
Estimated state tax
$________
Tax payments made
$________
Additional tax reserve
$________
Expected extension payment
$________
The final forms changed details.
They did not completely redefine the financial picture.
That is the goal.
Without Planning, the Same Delay Would Have Felt Completely Different
Imagine the same household with:
no K-1 estimates;
no tax projection;
no basis records;
no payment ledger;
no state tracking;
no tax reserve.
Now the extension becomes stressful.
They would not know:
what they owe.
what is missing.
what is deductible.
what states are involved.
whether enough cash is reserved.
Same K-1 delays.
Completely different experience.
The Difference Was Not Faster K-1s
This is important.
Tax planning did not make:
Partnership A file faster.
It did not make:
Fund C issue its form sooner.
It did not eliminate:
state complexity.
What it did was:
reduce uncertainty.
That matters.
Filing Control and Financial Control Are Different
Thomas and Rebecca could not fully control:
When the K-1 arrived.
But they could control:
Whether they had estimates.
Whether basis was maintained.
Whether payments were tracked.
Whether cash was reserved.
Whether states were identified.
Whether missing documents were organized.
This is a powerful distinction.
You cannot control every tax document.
You can control your preparation for it.
K-1 Delays Should Trigger Estimates, Not Guessing
If a final K-1 is unavailable:
Ask for:
Estimated ordinary income
$________
Capital gains
$________
Rental activity
$________
Interest/dividends
$________
Expected distributions
$________
State allocations
$________
Expected final delivery
________
If the entity cannot provide a precise estimate:
Use a range.
Use Low, Expected, and High K-1 Scenarios
LOW CASE
Projected K-1:
$________
EXPECTED CASE
Projected K-1:
$________
HIGH CASE
Projected K-1:
$________
Then calculate:
Tax under low case
$________
Tax under expected case
$________
Tax under high case
$________
Now you know the potential cash range.
Build the Reserve Around Uncertainty
Suppose:
Expected additional tax
$20,000
High-case additional tax
$30,000
You might decide to hold:
$30,000
until the K-1s are final.
Then:
If the liability is lower:
The excess reserve becomes available.
That is usually more comfortable than spending first and scrambling later.
K-1 Delays Can Affect More Than Filing
Late K-1s can also affect:
state filings;
basis calculations;
passive-loss calculations;
NIIT;
QBI;
investment reporting;
amended-return decisions.
The form is not just:
a number.
It can contain several tax attributes.
Investors Should Ask About Expected Delivery Before Tax Season
If you invest in:
partnerships;
private funds;
real estate syndications;
closely held businesses;
ask during the year:
When do you normally issue K-1s?
That information can help set realistic expectations.
Some investments may routinely create extended returns.
That is not necessarily bad.
But it should not be a surprise.
Filing Timeline Should Be Part of Investment Due Diligence
Before investing, you may evaluate:
expected return;
liquidity;
risk;
fees;
strategy.
Also consider:
What tax reporting does this investment create?
Questions include:
Will I receive a K-1?
When is it typically delivered?
Does it produce multi-state reporting?
Is unrelated business taxable income relevant for certain accounts?
Are tax estimates provided?
Tax administration is part of investment complexity.
Complex Households Need a Filing Calendar
Create:
JANUARY
W-2s and many 1099s arrive.
FEBRUARY
Brokerage statements.
Entity estimates requested.
MARCH
Partnership/S corporation filing season.
Initial K-1s begin arriving.
APRIL
Individual filing deadline or extension.
Estimated tax paid.
MAY–SEPTEMBER
Extended K-1s and final individual filings as information becomes available.
The exact timeline varies.
But the point is:
Build expectations before the deadline.
Do Not File Incomplete Just to File Early
A taxpayer may say:
“I hate extensions. Just file.”
That can be risky if a material K-1 is still outstanding.
Filing without known material information may create:
amended returns;
amended state returns;
professional fees;
additional interest;
administrative complexity.
An accurate extended return can be better than an incomplete early return.
Do Not Use an Extension as an Excuse to Ignore Taxes
The opposite mistake is:
“We extended, so we can worry about the tax later.”
No.
Again:
Extension to file ≠ extension to pay.
Estimate.
Pay.
Then finalize when the information arrives.
The Household Filing Command Center
Thomas and Rebecca eventually built a permanent dashboard.
W-2s
Complete
1099s
Complete
Partnership A
Estimate:
$________
Final:
Pending / Complete
Partnership B
Estimate:
$________
Final:
Pending / Complete
Fund C
Estimate:
$________
Final:
Pending / Complete
BASIS
Current / Needs Update
STATES
________________
FEDERAL TAX ESTIMATE
$________
STATE TAX ESTIMATE
$________
PAYMENTS MADE
$________
TAX RESERVE
$________
EXPECTED FILING DATE
________
Now the filing process had structure.
Before Their New System
K-1 delivery:
Unknown
Tax estimate:
Unknown
Basis:
Partially reconstructed
State exposure:
Unclear
Extension:
Stressful
Tax reserve:
Uncertain
After Their New System
K-1 delivery:
Tracked
Tax estimate:
Updated regularly
Basis:
Maintained
State exposure:
Identified
Extension:
Planned
Tax reserve:
Funded
The entities were still complex.
The process was no longer chaotic.
K-1 Delay Planning Checklist
K-1 INVENTORY
Every expected K-1 identified.
Entity type confirmed.
Expected delivery date recorded.
Draft estimate requested.
Final K-1 status tracked.
State schedules tracked.
TAX PROJECTION
Wages included.
Investment income included.
Estimated K-1 income included.
Federal tax projected.
State tax projected.
Withholding included.
Estimated payments included.
BASIS
S corporation basis current.
Partnership outside basis current.
Distributions recorded.
Contributions recorded.
Owner loans documented.
Suspended losses tracked.
CASH FLOW
Tax reserve funded.
Expected extension payment calculated.
High-case reserve considered.
Household liquidity protected.
FILING
Extension requirement reviewed.
Extension payment calculated.
Federal return waiting items listed.
State return waiting items listed.
Final filing target updated.
K-1 Delay Readiness Score
Give yourself one point for each YES.
I know every K-1 I expect.
I know which K-1s may arrive late.
I have estimated income for each.
My household tax projection includes those estimates.
Federal payments are tracked.
State payments are tracked.
Basis is current.
Distributions are tracked.
Suspended losses are tracked.
State allocations are anticipated.
Tax reserve is funded.
Extension payment is estimated.
Missing forms are tracked.
I know which entity controls my filing timeline.
I can estimate my tax even before every final form arrives.
13–15 YES
GREEN — Filing Delay Is Managed
8–12 YES
YELLOW — Important Unknowns Remain
0–7 YES
RED — The K-1 Is Controlling More Than Your Filing Date
Build the system now.
AI-Search Quick Answers
Why do K-1s sometimes arrive late?
Pass-through entities may need to finalize books, allocations, depreciation, ownership information, state reporting, or information received from other pass-through entities before issuing final K-1s.
Can one delayed K-1 delay another K-1?
Yes. If one partnership owns an interest in another pass-through entity, it may need the lower-tier entity's K-1 before it can finalize its own return and issue K-1s to its owners.
Does an extension give taxpayers more time to pay?
No. The IRS states that an extension gives additional time to file, not additional time to pay. Tax should generally still be estimated and paid by the original due date. (irs.gov)
Should taxpayers use zero for K-1 income if the form has not arrived?
Not when a reasonable estimate is available. For planning purposes, using entity estimates or a reasonable range can help project tax liability, withholding, estimated payments, and cash reserves.
Can a K-1 loss automatically be deducted?
No. Depending on the entity and facts, losses may be subject to basis, at-risk, passive-activity, and other limitations.
Is filing an extension necessarily a problem?
No. An extension can be an appropriate administrative tool when accurate information is not yet available. The important issue is to estimate and pay tax timely even if the return itself is filed later.
30 Questions to Ask When K-1s Drive the Filing Timeline
How many K-1s do we expect?
Which entities issue them?
Which K-1s historically arrive late?
Does one entity depend on another K-1?
What income is currently estimated?
What is the low estimate?
What is the high estimate?
What distributions were received?
Could income exceed distributions?
What federal tax is projected?
What state tax is projected?
What tax has already been paid?
What withholding exists?
Is an extension likely?
What payment should accompany the extension?
Is the tax reserve funded?
Is additional reserve needed for uncertainty?
Is stock basis current?
Is partnership outside basis current?
Are losses potentially limited?
Are passive losses tracked?
Are state allocations known?
Will nonresident returns be required?
Are PTE tax credits expected?
Are any amended returns likely?
When is each final K-1 expected?
What is still missing after the K-1 arrives?
What is the expected final filing date?
Who is responsible for each open item?
Does a delayed form delay the paperwork—or does it also delay my financial planning?
Only the paperwork should have to wait.
What to Do Next
Create a:
K-1 Filing Timeline Command Sheet
K-1 #1
Entity:
________________
Estimated income:
$________
Expected date:
________
Status:
________
K-1 #2
Entity:
________________
Estimated income:
$________
Expected date:
________
Status:
________
K-1 #3
Entity:
________________
Estimated income:
$________
Expected date:
________
Status:
________
PROJECTED FEDERAL TAX
$________
PROJECTED STATE TAX
$________
TAX ALREADY PAID
$________
EXTENSION PAYMENT
$________
TAX RESERVE
$________
BASIS ISSUES
________________
STATE ISSUES
________________
TARGET FILING DATE
________
Then update it as each form arrives.
Final Thought
Thomas and Rebecca did not have a tax problem because their K-1s arrived late.
They had a timing problem.
Those are different things.
The old approach would have been:
Wait.
Worry.
Guess.
Scramble.
The better approach was:
Estimate.
Project.
Reserve.
Track.
Update.
Then file when accurate information became available.
That is how a household keeps financial control even when the paperwork timeline is outside its control.
You may not control when every K-1 arrives.
But you can control:
whether you know what to expect.
whether basis is current.
whether payments are documented.
whether the tax reserve is funded.
whether state obligations are anticipated.
whether the extension is planned.
Because the goal is not always:
File as early as possible.
The goal is:
File accurately, pay timely, and avoid letting delayed paperwork create delayed planning.
Book Your K-1 and Complex Filing Strategy Consultation
If your filing timeline is driven by partnerships, S corporations, real-estate investments, private funds, or other pass-through entities, you do not have to wait for every final form before building a tax plan.
We can review:
Expected K-1s;
preliminary income estimates;
basis;
distributions;
suspended losses;
federal tax projections;
state tax projections;
estimated payments;
extension-payment planning;
tax reserves;
multi-state filings;
expected filing timelines.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.