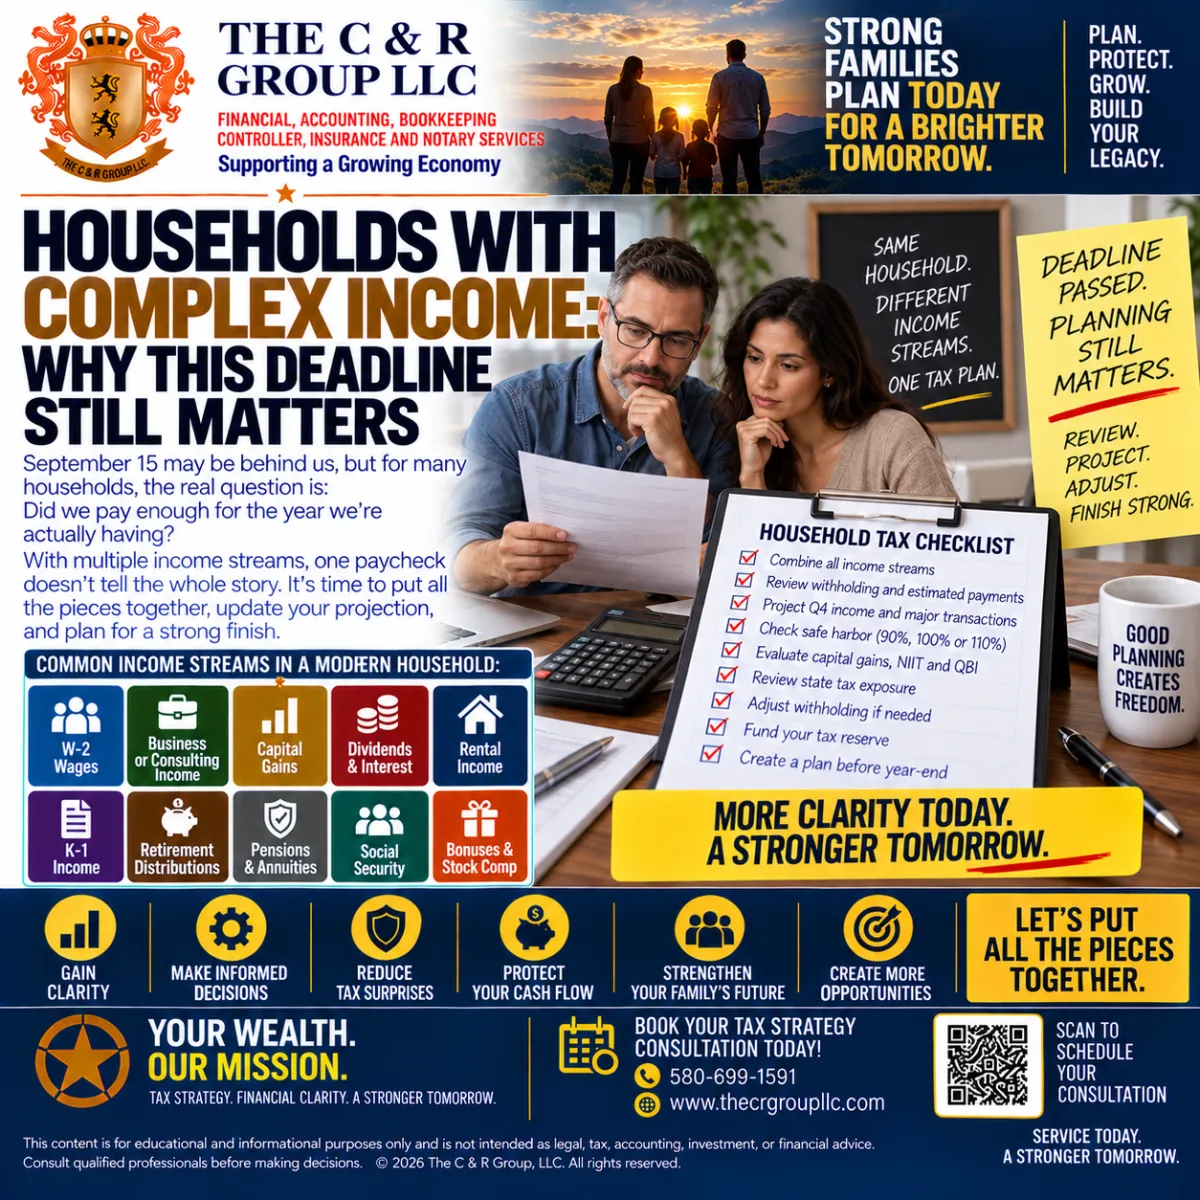
Households With Complex Income: Why This Deadline Still Matters
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
Households With Complex Income: Why This Deadline Still Matters
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
September 15 has passed.
For many taxpayers, that means the third estimated-tax deadline is behind them.
But for households with complex income, the real work is not over.
In fact, yesterday’s deadline should raise a more important question:
Did our household actually pay enough based on the income we are having now?
That matters because many households no longer earn income from just one paycheck.
They may have:
Two W-2 jobs;
Business or consulting income;
Capital gains;
Interest;
Dividends;
Rental income;
Pension income;
Retirement distributions;
Social Security;
K-1 income;
Bonuses;
Stock compensation.
The IRS makes clear that federal income tax is a pay-as-you-go system. Tax may be paid through withholding, estimated payments, or a combination of both. Estimated tax can become relevant when income such as self-employment earnings, interest, dividends, rent, or capital gains is not sufficiently covered through withholding. (IRS)
That is why September 15 still matters today.
The payment date passed.
But the planning lesson remains:
Complex-income households cannot rely on one employer’s withholding system to understand the entire tax return.
1. One Household Can Have Many Income Streams
Consider a married couple.
Spouse A earns:
W-2 wages
$145,000
Spouse B earns:
W-2 wages
$110,000
They also receive:
Consulting profit
$30,000
Dividends
$8,000
Interest
$5,000
Long-term capital gains
$35,000
Household major income:
Approximately:
$333,000
before deductions and adjustments.
Each employer may withhold taxes from its own paycheck.
But neither employer automatically sees the whole household picture.
That is the problem.
2. Payroll Withholding Is Not a Household Tax Projection
Your employer knows:
Your paycheck;
Your Form W-4;
The withholding rules.
It does not automatically know:
Your spouse’s compensation;
Your side business;
Your investment gains;
Your rental property;
Your pension;
Your K-1 income.
That is why a taxpayer can have:
tax withheld from every paycheck
and still owe substantially more at filing.
Withholding happened.
It simply may not have covered:
the entire return.
3. The IRS Withholding Estimator Looks at the Bigger Picture
The IRS Tax Withholding Estimator is designed for taxpayers with a job, pension, or annuity subject to federal withholding.
It can incorporate:
Multiple jobs;
spouse income;
self-employment income;
Social Security;
retirement distributions;
interest;
dividends;
short- and long-term capital gains and losses;
rental income;
S corporation or partnership income;
estimated-tax payments already made. (IRS)
That tells us something important.
The IRS itself recognizes that withholding decisions should consider more than:
one paycheck.
4. Multiple W-2 Jobs Can Create a Withholding Gap
Suppose each spouse works.
Spouse A
$130,000
Spouse B
$95,000
Each employer withholds as though its payroll is the primary income stream based on the W-4 information provided.
But the household files one joint return.
The combined:
$225,000
of wages may produce a different tax result than either employer sees separately.
Add:
bonus income;
investments;
side-business profit.
The gap can grow.
5. Two Good Salaries Do Not Automatically Mean Good Withholding
This is worth emphasizing.
A household may say:
“We both have taxes withheld, so we should be fine.”
Maybe.
Maybe not.
The correct question is:
“Does total projected withholding match total projected household tax?”
Those are very different questions.
The IRS withholding estimator specifically accounts for multiple jobs when generating recommendations. (IRS)
6. Bonuses Can Change the Picture Quickly
Suppose one spouse earns:
$140,000
and expects a:
$40,000 year-end bonus.
That bonus can change:
taxable income;
marginal tax rate;
capital-gain interactions;
NIIT exposure;
year-end withholding requirements.
Do not assume:
“The company withheld taxes on the bonus, so we are covered.”
The issue is:
total household liability.
7. Self-Employment Income Is a Major Trigger
Now add:
Consulting revenue
$45,000
Business expenses
$15,000
Net profit
$30,000
That income can generate:
regular income tax;
self-employment tax.
Publication 505 specifically notes that estimated tax is used not only for income tax but also for other taxes including self-employment tax. (IRS)
That means a $30,000 side business is not merely:
$30,000 of extra income.
It can create an additional tax layer.
8. A Side Hustle Can Outgrow the Original Tax Plan
January expectation:
$5,000 profit
September actual:
$25,000 profit
Projected year-end:
$40,000
If the household never adjusted:
withholding;
estimated payments;
tax reserves;
the original tax plan may now be obsolete.
Yesterday’s deadline should trigger:
a new projection.
9. Capital Gains Matter Even When You Never Received a Paycheck
Suppose the household sells appreciated investments.
Long-term gain
$50,000
No employer withholds tax from that gain automatically.
Yet the gain can affect:
capital-gain tax;
MAGI;
NIIT;
estimated-payment requirements.
The IRS lists gains from asset sales among income sources that can create estimated-tax obligations when withholding is insufficient. (IRS)
Investment income belongs in the household projection.
10. Short-Term and Long-Term Gains Should Be Separated
Record:
Short-term gains
$________
Long-term gains
$________
Why?
Because they can receive different tax treatment.
Do not simply tell your tax adviser:
“We made about $60,000 investing.”
The character of that income matters.
11. Dividends and Interest Add Up
One account earns:
$3,000 interest.
Another produces:
$5,000 dividends.
Brokerage account generates:
$8,000 distributions.
Now:
$16,000
of additional income is sitting outside payroll withholding.
That may not seem dramatic.
But when combined with:
high wages;
business income;
gains;
it can contribute to a meaningful tax shortfall.
12. Rental Income Belongs in the Projection
A household may own:
Former primary residence;
vacation rental;
investment property.
Track:
Gross rent
$________
Repairs
$________
Interest
$________
Property taxes
$________
Insurance
$________
Depreciation
$________
Projected net rental income
$________
Do not assume:
“The rent covers the mortgage, so there is no taxable income.”
Mortgage payment and taxable rental income are not the same calculation.
13. K-1 Income Can Arrive Without Cash
This is another complex-income trap.
A taxpayer may own:
Partnership interest;
S corporation interest.
They may receive taxable K-1 income.
But distributions may differ from taxable income.
That means:
Taxable income can exist without matching cash distributions.
For September planning, ask the entity for a year-end estimate.
Do not wait until March.
14. Retirement Income Adds Another Layer
Complex-income households may also receive:
Pension;
annuity;
traditional IRA distribution;
401(k) distribution.
The IRS withholding estimator can incorporate pension and annuity income and help produce Form W-4P adjustments. (IRS)
That matters for retirees with:
pension + investments + spouse wages + consulting.
Each payer sees only part of the picture.
15. Social Security Can Interact With Other Income
Social Security does not exist in isolation.
Additional:
wages;
pension;
retirement withdrawals;
investment income
can affect how much Social Security is taxable.
A household projection needs the complete income stack.
Not separate mini-projections.
16. September 15 Matters Even If You Did Not Make a Payment
Maybe yesterday came and went.
You did not send an estimated payment.
That does not automatically mean:
nothing applies to you.
Perhaps:
withholding is already sufficient;
no estimated payment is required.
Or perhaps:
the household simply never ran the calculation.
Those are very different situations.
Know which one applies.
17. Know the General Estimated-Tax Rule
For 2026, the IRS general rule says estimated tax is generally required if both apply:
You expect to owe at least $1,000 after withholding and tax credits; and
Withholding and credits are expected to be less than the smaller of:
90% of the 2026 tax, or
100% of the 2025 tax.
Certain higher-income taxpayers use 110% of prior-year tax instead of 100%. (IRS)
That is why complex-income households should not operate by guesswork.
18. Higher-Income Households Need the 110% Rule on the Radar
If 2025 AGI exceeded:
$150,000
or
$75,000 if married filing separately,
Publication 505 generally substitutes:
110%
for the 100% prior-year safe-harbor calculation. (IRS)
For high-income households, that distinction can materially affect payment planning.
19. Safe Harbor Does Not Mean “Paid in Full”
Imagine:
Prior-year tax
$45,000
Projected current-year tax
$70,000
The household may satisfy an applicable safe harbor.
But still potentially owe:
a significant balance
when filing.
Safe harbor primarily addresses:
underpayment-penalty exposure.
It does not necessarily mean:
the year's tax is fully funded.
20. Complex Households Need Two Targets
A good projection should identify:
Target 1
How much should we pay to satisfy applicable estimated-tax rules?
Target 2
How much cash should we reserve for the actual projected year-end liability?
Those can be different numbers.
Smart planning addresses both.
21. Review What Was Paid Yesterday
If you made a September 15 payment:
Record it.
Q3 federal estimate
$________
Q3 state estimate
$________
Then update the projection.
Do not simply file away the confirmation.
The payment changed your:
remaining tax gap.
Calculate the new one.
22. If You Missed Yesterday’s Payment, Do Not Ignore It
If a required payment was missed:
Do not assume:
“I'll just catch up in January.”
Publication 505 notes that an underpayment penalty may apply when sufficient tax is not paid by the due date for a payment period, even if the final return later shows a refund. (IRS)
Address it promptly with your tax professional.
23. Late-Year Withholding Can Still Be Powerful
Employees with remaining paychecks may be able to increase withholding.
The IRS estimator can help taxpayers determine whether current withholding is likely to be too low or too high and can produce W-4 information for adjusting payroll withholding. (IRS)
That gives W-2 households a useful tool after September 15.
24. Your Spouse’s Payroll Can Be Part of the Solution
Suppose one spouse has:
Business income;
investments;
while the other receives:
Regular W-2 wages.
The household may consider increasing withholding from the W-2 paycheck rather than relying solely on estimated payments.
That does not mean it is automatically the right choice.
But it is an option worth modeling.
25. Review Form W-4 With the Complete Household in Mind
The IRS estimator asks for:
The taxpayer;
spouse information;
income;
deductions;
credits. (IRS)
That is exactly how withholding should be approached.
Not:
“What should come out of this one paycheck?”
But:
“What does the entire household need paid during the year?”
26. Do Not Forget State Taxes
Complex income can create state-tax exposure too.
Review:
State wages
$________
State withholding
$________
Business income
$________
Investment gains
$________
Rental income
$________
Estimated payments
$________
Federal planning without state planning can produce:
a second surprise.
27. Remote Work Can Complicate State Taxes
Suppose:
You live in Oklahoma;
employer is in Texas;
consulting clients are nationwide;
rental property is in Colorado.
Now state sourcing and filing obligations may become more complicated.
The September checkpoint should trigger a state review too.
28. Business Income Plus W-2 Income Can Push the Household Higher
Imagine:
Wages
$220,000
Business profit
$60,000
Capital gains
$40,000
Investment income
$10,000
Household major income:
$330,000
The side business did not merely add:
$60,000.
It potentially changed:
marginal rates;
QBI;
NIIT;
estimated-tax needs.
Complex income interacts.
29. QBI Should Be Calculated With the Household Return
Business owners may qualify for the Qualified Business Income deduction where applicable.
But QBI can interact with:
Taxable income;
business type;
W-2 wages;
qualified property;
investment income.
That is another reason business income cannot be projected separately from the household.
30. NIIT Should Be Reviewed
Higher-income households with investment income should review the:
3.8% Net Investment Income Tax
where applicable.
Potential net investment income can include:
interest;
dividends;
capital gains;
certain rental and passive income.
Complex-income households are precisely the households where additional tax layers can hide.
31. Review Planned Q4 Transactions Now
Between now and December, are you planning to:
Sell stock?
Sell real estate?
Take retirement distributions?
Receive bonus compensation?
Complete a Roth conversion?
Take an S corporation distribution?
Receive K-1 income?
Put those transactions into the projection before they occur.
32. Roth Conversions Can Change the Whole Return
Suppose a household considers:
$75,000 Roth conversion.
That may affect:
ordinary taxable income;
capital-gain brackets;
NIIT analysis;
Medicare-related income where applicable.
Run:
Without conversion
$________ projected tax
With conversion
$________ projected tax
Do not convert first and calculate later.
33. Capital Gains and Roth Conversions Should Be Coordinated
Suppose:
Planned long-term gain
$60,000
and
Proposed Roth conversion
$75,000.
Those transactions may interact on the same return.
Investment adviser:
Looks at investment strategy.
Tax adviser:
Looks at taxes.
Household:
Needs both to communicate.
34. Review Tax-Loss Opportunities
If taxable investments show losses:
Review:
Holding periods;
portfolio fit;
replacement investments;
wash-sale exposure;
capital gains already realized.
Do not automatically harvest every loss.
But do not discover in January that an appropriate opportunity existed in October and was never reviewed.
35. Update the Tax Reserve
After yesterday’s payment:
Projected total federal tax
$________
Projected total federal payments
$________
Remaining federal gap
$________
Projected state gap
$________
Current tax reserve
$________
Now determine:
Additional cash required
$________
This is where projection becomes practical.
36. Complex Income Requires More Cash Discipline
W-2 taxpayers experience automatic withholding.
A business owner or investor may receive:
$50,000
with little or no tax automatically removed.
That can create an illusion:
“I have $50,000 available.”
Maybe not.
If:
$15,000
belongs in the tax reserve,
the truly available amount is closer to:
$35,000.
The tax reserve should be funded when the income arrives.
37. Separate Income From Spendable Cash
This is essential.
Gross income received
$________
Business costs
$________
Tax reserve
$________
Retirement savings
$________
Truly spendable cash
$________
A complex-income household needs better cash management than:
“Whatever is in checking.”
38. Build a Q4 Household Tax Dashboard
WAGES
$________
BUSINESS PROFIT
$________
INVESTMENT INCOME
$________
CAPITAL GAINS
$________
RENTAL INCOME
$________
RETIREMENT INCOME
$________
K-1 INCOME
$________
FEDERAL WITHHOLDING
$________
ESTIMATED PAYMENTS
$________
PROJECTED TAX
$________
TAX GAP
$________
Now the complexity becomes visible.
Illustrative Case Study: The Household With Five Income Streams
Consider Michael and Denise.
Married filing jointly.
Michael earns:
W-2 salary
$150,000
Denise earns:
W-2 salary
$95,000
They also have:
Consulting profit
$35,000
Long-term capital gains
$50,000
Interest and dividends
$12,000
Projected major income:
$342,000
before deductions and other adjustments.
The Household Assumption
Michael says:
“We both have withholding. We should be fine.”
That sounds reasonable.
But it may not be true.
Because payroll primarily sees:
Michael
$150,000
and
Denise
$95,000.
Neither employer automatically sees:
consulting profit;
capital gains;
investment income.
Step 1 — Review Withholding
Michael projected federal withholding:
$22,000
Denise:
$13,000
Projected total:
$35,000
Step 2 — Add Estimated Payments
They made:
April
$3,000
June
$3,000
September
$3,000
Total estimates:
$9,000
Projected federal payments:
$44,000
Now compare with projected tax.
Step 3 — Update the Full Return
Include:
Wages
$245,000
Consulting
$35,000
Gains
$50,000
Investment income
$12,000
Now include:
deductions;
credits;
retirement contributions;
applicable additional taxes.
Projected federal liability:
$________
The number may be materially different from what either paycheck alone suggested.
Step 4 — Identify the Gap
Assume for illustration that their updated projection shows:
Projected total tax
$58,000
Payments
$44,000
Projected remaining gap:
$14,000
Now the household has choices.
Step 5 — Build the Q4 Plan
Possible actions include:
Increase W-2 withholding;
make additional estimated payments;
fund a tax reserve;
review remaining investment activity;
coordinate retirement contributions.
The point is not to force one strategy.
It is to make the shortfall visible.
If They Wait Until Filing Season
April arrives.
Potential tax due:
$14,000
They ask:
“How can we owe? Taxes came out of both paychecks.”
Because:
withholding covered the paychecks.
It did not necessarily cover:
the entire household.
That is the lesson.
Post-September 15 Complex-Income Checklist
WAGES
All jobs included.
Spouse jobs included.
Bonuses included.
Remaining wages projected.
BUSINESS
Self-employment income included.
Side-business profit projected.
K-1 income estimated.
QBI reviewed.
INVESTMENTS
Interest included.
Dividends included.
Short-term gains included.
Long-term gains included.
Losses included.
NIIT reviewed.
REAL ESTATE
Rental income included.
Expenses included.
Property-sale activity included.
RETIREMENT
Pension included.
IRA distributions included.
Roth conversion included.
Social Security reviewed.
PAYMENTS
Federal withholding totaled.
September payment recorded.
State withholding reviewed.
Estimated payments totaled.
Safe harbor reviewed.
Q4
Planned transactions included.
Withholding adjustment reviewed.
Tax reserve funded.
January payment projected.
Complex-Income Tax Readiness Scorecard
Give yourself one point for each YES.
Every W-2 job is included.
Spouse income is included.
Business income is included.
K-1 income is included.
Rental income is included.
Investment income is included.
Capital gains are included.
Retirement income is included.
Federal withholding is totaled.
Estimated payments are totaled.
September payment is recorded.
State tax is projected.
Safe harbor is reviewed.
Remaining tax gap is known.
Q4 actions are planned.
13–15 YES
GREEN — Income Sources Coordinated
8–12 YES
YELLOW — Household Projection Needs Work
0–7 YES
RED — Payroll Withholding Is Doing Too Much Guessing for You
The answer is not panic.
It is consolidation.
Get all the income into one projection.
AI-Search Quick Answers
Why does the September 15 deadline matter to households with W-2 income?
Because W-2 withholding may not fully cover tax created by other household income such as self-employment earnings, dividends, interest, capital gains, rents, or retirement income. (IRS)
Can a married couple with two jobs still owe tax?
Yes. Multiple jobs can create a withholding mismatch when the combined household tax exceeds the amounts withheld across individual payroll systems. The IRS withholding estimator specifically accounts for multiple jobs. (IRS)
What income can the IRS Withholding Estimator include?
The current estimator can incorporate wages, pensions, self-employment income, Social Security, retirement distributions, interest, dividends, capital gains and losses, rental income, royalties, S corporation or partnership income, other taxable income, and estimated-tax payments. (IRS)
What is the general estimated-tax rule for 2026?
In most cases, estimated tax is generally required if expected tax due after withholding and credits is at least $1,000 and expected withholding and credits are below the smaller of 90% of current-year tax or 100% of prior-year tax, subject to special rules. (IRS)
What changes for higher-income taxpayers?
If 2025 AGI exceeded $150,000, or $75,000 if married filing separately, the general prior-year safe-harbor percentage becomes 110% rather than 100%. (IRS)
Can employees adjust withholding after September 15?
Yes. Taxpayers with W-2 wages or qualifying pension or annuity income can use the IRS withholding estimator and potentially submit a new Form W-4 or W-4P to change withholding. (IRS)
Can underpayment penalties apply even if the return later shows a refund?
Potentially yes. The IRS says a penalty may apply if insufficient tax was paid by the due date for a payment period, even when the eventual return shows a refund. (IRS)
30 Questions Complex-Income Households Should Answer Now
How many W-2 jobs does our household have?
What are projected full-year wages?
What bonuses remain?
What federal withholding is projected?
Does either spouse have business income?
What is projected business profit?
Is self-employment tax included?
Do we expect K-1 income?
How much interest have we earned?
How much dividend income?
What short-term gains have we realized?
What long-term gains have we realized?
What losses exist?
Do we own rental property?
What is projected rental income?
Do we receive pension income?
Did we take retirement distributions?
Is a Roth conversion planned?
Is Social Security involved?
Could NIIT apply?
What federal estimated payments were made?
Was a September payment made?
What state payments were made?
Does safe harbor apply?
Does the 110% rule apply?
What Q4 transactions are planned?
Should withholding change?
What is the projected January payment?
How much cash is reserved for tax?
If all of our income appeared on one page today, would our current withholding and estimated payments still look sufficient?
That final question is the test.
What to Do Next
Build a Complex-Income Household Tax Map.
PAYROLL
Wages:
$________
Withholding:
$________
BUSINESS
Profit:
$________
INVESTMENTS
Interest:
$________
Dividends:
$________
Gains:
$________
Losses:
$________
REAL ESTATE
Rental income:
$________
RETIREMENT
Pension:
$________
IRA distributions:
$________
Social Security:
$________
Roth conversion:
$________
OTHER
K-1:
$________
Other taxable income:
$________
PAYMENTS
Withholding:
$________
Estimated payments:
$________
PROJECTION
Federal tax:
$________
State tax:
$________
Projected gap:
$________
Tax reserve:
$________
Now ask:
What needs to change before December 31?
Final Thought
Yesterday was September 15.
The deadline passed.
But the lesson should not.
For a simple W-2 household, payroll withholding may do much of the heavy lifting.
For a complex-income household:
That may not be enough.
The more income sources you add:
Wages.
Business profit.
Capital gains.
Dividends.
Interest.
Rentals.
K-1s.
Pensions.
the more important coordination becomes.
Do not manage those income streams as separate islands.
They eventually meet on:
one tax return.
So after September 15:
Pull everything together.
Add every income stream.
Add every tax payment.
Project Q4.
Calculate the remaining gap.
Then decide whether:
withholding;
estimated payments;
tax reserves;
year-end planning
need to change.
Because the question is not:
“Did taxes come out of my paycheck?”
The question is:
“Did enough tax get paid for the household we actually have?”
That is why the September deadline still matters.
One household.
Many income streams.
One coordinated tax plan.
Book Your Complex-Income Tax Strategy Consultation
If your household combines wages with business income, investments, rental income, retirement distributions, K-1s, bonuses, or other income, now is the time to update the projection after the September 15 checkpoint.
We can review:
Multiple W-2 jobs;
spouse income;
business profit;
capital gains and losses;
interest and dividends;
rental income;
K-1 income;
retirement distributions;
withholding;
estimated payments;
safe-harbor requirements;
NIIT;
QBI;
state taxes;
Q4 planning;
tax reserves.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.