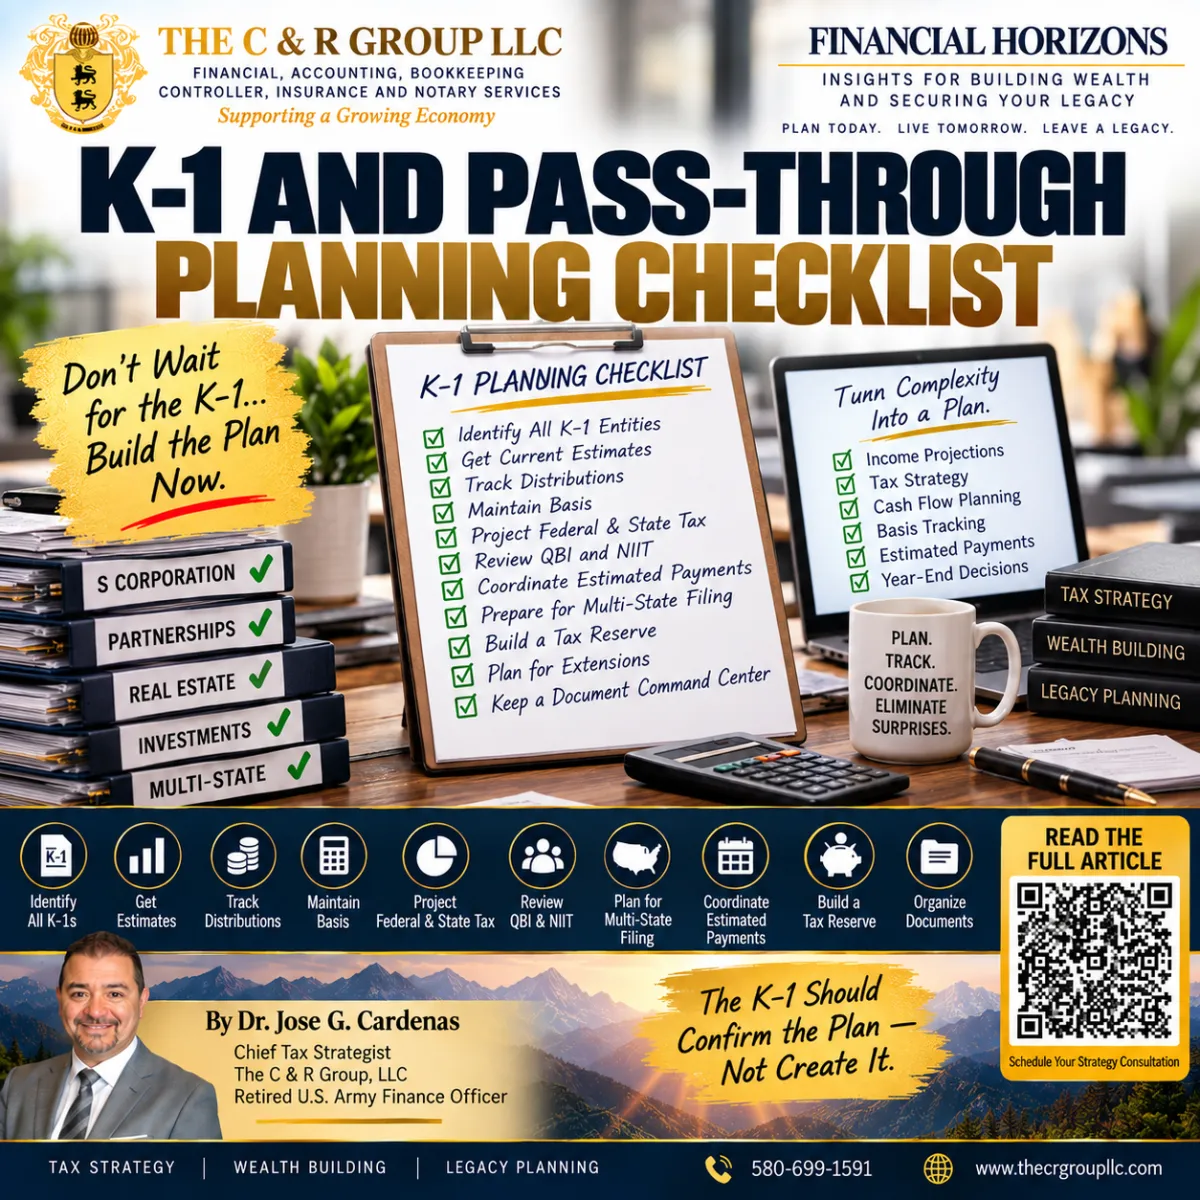
K-1 and Pass-Through Planning Checklist
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
K-1 and Pass-Through Planning Checklist
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
This week, we have covered the biggest planning problems created by K-1s, pass-through entities, basis, delayed forms, estimated payments, and entity complexity.
Now it is time to turn those lessons into one practical system.
A K-1 should never be treated as:
“Something we deal with when it arrives.”
By then, the year may already be over.
The business may have earned the income.
The partnership may have made distributions.
The owner may have taken cash out.
Estimated payments may have been made.
Capital gains may have occurred.
Retirement decisions may already be complete.
And the final form may still be months away.
That is why pass-through planning needs a checklist.
Not just for filing season.
For the entire year.
The central principle for today is:
If you receive K-1 income, your tax plan should track the entity, the income, the cash, the basis, the payments, and the household impact before the final form arrives.
1. Identify Every K-1 You Expect
Start with a complete inventory.
List every entity expected to issue a K-1.
Entity 1
________________
Entity 2
________________
Entity 3
________________
Entity 4
________________
Do not assume you will remember them all during filing season.
Complexity increases quickly when multiple entities are involved.
2. Confirm the Entity Type
For each one, identify:
S corporation
Partnership
Real-estate partnership
Investment partnership
Private fund
Other pass-through structure
Entity type matters because:
basis rules differ;
distributions differ;
loss rules differ;
owner compensation differs;
state treatment may differ.
“Pass-through” does not mean:
identical tax treatment.
3. Confirm Ownership Percentage
Record:
Ownership percentage
________%
Voting percentage
________%
Profit allocation
________%
Loss allocation
________%
Do not assume all percentages are always the same.
Review governing documents where necessary.
4. Request a Current K-1 Estimate
Do not wait for March.
Ask the entity for:
Projected ordinary income
$________
Rental income
$________
Capital gains
$________
Interest/dividends
$________
Deductions
$________
Credits
$________
Expected distributions
$________
You are not asking for perfection.
You are asking for a planning estimate.
5. Use a Range When the Estimate Is Uncertain
Build:
LOW CASE
Projected K-1:
$________
EXPECTED CASE
Projected K-1:
$________
HIGH CASE
Projected K-1:
$________
Then calculate tax exposure under each scenario.
Planning ranges are better than pretending the final K-1 is already known.
6. Separate Taxable Income From Cash Distributions
This is one of the most important checklist items.
Track:
Projected taxable K-1 income
$________
Expected cash distribution
$________
Difference:
$________
If taxable income exceeds cash received:
That difference may need to be funded from other household cash.
7. Remember That Cash and Tax Do Not Move Together
A pass-through can retain cash inside the entity while the owner still receives taxable income.
That is why the household cannot simply ask:
“How much did we receive?”
It also needs to ask:
“How much income was allocated to us?”
Those are different questions.
8. Track Federal Estimated Payments
Record:
Q1
$________
Q2
$________
Q3
$________
Projected Q4 / January payment
$________
Then compare those payments with the current household projection.
Do not keep estimated payments on autopilot if K-1 income changes materially.
9. Track Household Withholding
Add:
Owner W-2 withholding
$________
Spouse withholding
$________
Pension withholding
$________
Other withholding
$________
K-1 planning should use:
withholding + estimated payments
together.
10. Build the Combined Household Projection
Include:
W-2 income
$________
S corporation K-1 income
$________
Partnership K-1 income
$________
Rental income
$________
Capital gains
$________
Interest
$________
Dividends
$________
Retirement income
$________
Other income
$________
Then estimate:
Federal liability
$________
State liability
$________
Now you have one coordinated picture.
11. Calculate the Tax Gap
Use:
Projected tax – projected withholding – estimated payments = projected remaining liability
Federal gap
$________
State gap
$________
Total remaining gap
$________
That number should drive the tax reserve.
12. Fund the Tax Reserve
Track:
Current reserve
$________
Target reserve
$________
Shortfall
$________
Funding deadline
________
Do not wait for the final K-1 before reserving cash.
A reasonable estimate is enough to begin.
13. Build a Tax Distribution Policy
If you control the business or have influence over distributions:
Review whether tax distributions are being made.
Possible framework:
Federal percentage
________%
State percentage
________%
Distribution frequency
Monthly / Quarterly / Annual
Minimum working-capital reserve
$________
Distribution cap
$________
Tax distributions should support owner liquidity without weakening the business.
14. Track S Corporation Stock Basis
For S corporation shareholders:
Beginning stock basis
$________
Add:
Contributions
$________
Income items
$________
Subtract:
Distributions
$________
Losses
$________
Nondeductible items
$________
Ending projected stock basis
$________
The shareholder is responsible for basis tracking.
Do not rely solely on the K-1.
15. Track S Corporation Debt Basis Separately
If you personally loaned money to the S corporation:
Beginning debt basis
$________
New loans
$________
Repayments
$________
Loss usage
$________
Ending debt basis
$________
Debt basis and stock basis are separate calculations.
16. Do Not Assume Guarantees Create Debt Basis
A shareholder guarantee of company debt does not automatically equal shareholder debt basis.
Documentation and actual payment matter.
This is exactly why debt activity should be reviewed before losses or repayments are analyzed.
17. Track Partnership Outside Basis
For partnerships:
Beginning outside basis
$________
Contributions
$________
Income
$________
Share of liabilities
$________
Distributions
$________
Losses
$________
Ending outside basis
$________
Partnership basis is not the same system as S corporation basis.
18. Do Not Confuse Capital Account With Outside Basis
The K-1 may report a capital account.
That does not automatically equal:
outside basis.
Partnership liabilities can be one reason the numbers differ.
Keep a separate outside-basis schedule.
19. Review Loss Limitations Before Counting the Deduction
If the K-1 shows a loss:
Review:
Basis limitation
At-risk limitation
Passive-activity limitation
Excess-business-loss limitation where applicable
Do not automatically build your tax projection around:
the full K-1 loss.
20. Track Suspended Losses
For each entity:
Prior suspended loss
$________
Current-year loss
$________
Allowed this year
$________
Remaining suspended
$________
Suspended losses need ongoing records.
They should not disappear into last year's workpapers.
21. Review QBI
For eligible pass-through activity:
Review:
Projected QBI
$________
W-2 wages
$________
Qualified property
$________
Taxable income
$________
Business type
________
Do not assume:
“20% of the K-1 is deductible.”
The calculation can be more complicated.
22. Review NIIT
High-income households should review possible Net Investment Income Tax exposure.
Potential items may include:
interest;
dividends;
capital gains;
passive pass-through income;
certain rental activity.
The household projection needs all relevant income sources together.
23. Coordinate Capital Gains
Track:
Realized short-term gains
$________
Realized long-term gains
$________
Planned Q4 sales
$________
Available losses
$________
Then ask:
How does projected K-1 income affect the rest of the investment-tax picture?
Model them together.
24. Coordinate Roth Conversion Decisions
If a conversion is planned:
Expected K-1 case
$________
High K-1 case
$________
Proposed Roth conversion
$________
Projected tax under each
$________
Do not execute a conversion using outdated pass-through assumptions.
25. Coordinate Charitable Giving
If substantial charitable giving is planned:
Review:
cash;
appreciated securities;
timing;
documentation;
deduction limits.
A higher K-1 may affect the tax environment.
But charitable intent should still drive the decision.
26. Review Retirement Contributions
For business owners and households:
Track:
401(k)
$________
TSP
$________
SEP
$________
SIMPLE
$________
Profit-sharing
$________
IRA planning
$________
Coordinate contributions with:
cash flow;
business obligations;
household income;
tax strategy.
27. Review Owner Compensation
For S corporation shareholder-employees:
Track:
W-2 wages YTD
$________
Projected annual wages
$________
Projected S corporation profit
$________
Distributions
$________
If profit materially changes:
Review compensation before year-end payroll closes.
28. Review Owner Distributions
Before another distribution:
Confirm:
tax reserve funded;
basis reviewed;
payroll funded;
vendors covered;
debt covered;
Q1 cash protected.
Distribution:
$________
Truly available cash:
$________
Those two numbers may be very different.
29. Review Capital Contributions
If money went into the entity:
Document:
Amount
$________
Date
________
Contribution type
Capital / Other
Support
Yes / No
Contributions can affect basis.
Track them when they happen.
30. Review Owner Loans
If money moved between the owner and entity:
Document whether it was:
loan;
repayment;
distribution;
contribution;
reimbursement.
For actual loans:
Note
Yes / No
Principal
$________
Interest rate
________
Repayment terms
________
Do not let filing season decide what the transaction “must have been.”
31. Review Multi-State Activity
For every entity:
State 1
________
State 2
________
State 3
________
Then review:
nonresident filing;
state K-1 allocation;
composite returns;
PTE tax;
owner credits;
estimated payments.
A federal K-1 can create several state filing obligations.
32. Track Pass-Through Entity Taxes
If the entity paid state PTE tax:
Record:
State
________
Entity-level tax paid
$________
Owner credit
$________
Remaining personal estimate
$________
This reduces the risk of:
double funding
or
missing the credit.
33. Track Expected K-1 Delivery Dates
For each entity:
Preliminary estimate
Expected: ________
Draft K-1
Expected: ________
Final federal K-1
Expected: ________
State schedules
Expected: ________
Now you know what may control your filing timeline.
34. Identify Which K-1 Is Most Likely to Delay Filing
Ask:
Does one entity own another pass-through?
Does the entity routinely extend?
Is it multi-state?
Is it a private investment fund?
Are books consistently late?
Circle the highest-risk K-1.
That one may determine:
when your return can actually be filed.
35. Plan for an Extension Before You Need One
If delayed K-1s are likely:
Estimate:
Federal tax due at original deadline
$________
State tax due
$________
Extension payment
$________
Reserve available
$________
An extension gives more time to file.
It generally does not give more time to pay.
Planning the extension eliminates unnecessary stress.
36. Maintain a K-1 Open-Item List
Use:
OPEN
Draft K-1;
final K-1;
state schedule;
basis confirmation;
distribution reconciliation.
COMPLETE
Entity estimate;
federal projection;
payments recorded;
reserve funded.
This turns filing into:
project management.
37. Maintain a Document Command Center
Store:
K-1s;
basis schedules;
estimated-payment confirmations;
owner-loan documents;
capital-contribution records;
distribution records;
state schedules;
governing agreements.
One secure location.
Not five inboxes and three desk drawers.
38. Reconcile the Books to the K-1
For businesses you control:
Compare:
Book profit
$________
Tax return income
$________
K-1 allocation
$________
Then understand legitimate differences.
Your accounting records and tax records should reconcile logically.
39. Reconcile Distributions
Compare:
Book distributions
$________
K-1 distributions
$________
Basis schedule distributions
$________
Those records should agree.
If they do not:
Investigate before filing.
40. Reconcile Owner Loans
Compare:
QuickBooks loan balance
$________
Promissory note balance
$________
Tax-basis records
$________
Actual bank activity
$________
Four systems should not show four different answers.
41. Reconcile Estimated Payments
Compare:
Client records
$________
IRS payment confirmations
$________
State payment confirmations
$________
Tax software carryforward
$________
A missing payment record can create an avoidable filing error.
42. Build a Quarterly Review Schedule
Q1
Update entity income.
Q2
Update basis and distributions.
Q3
Update estimated payments and tax reserves.
Q4
Finalize year-end strategy.
Then:
January
Confirm final payments.
Filing season
Reconcile final forms.
This is what year-round planning looks like.
Illustrative Year-End Example
Consider:
Alex and Jennifer
Alex owns:
100% of an S corporation;
30% of a partnership.
Jennifer earns W-2 wages.
They also own investments.
Their projected income:
Jennifer wages
$135,000
Alex S corporation wages
$95,000
S corporation K-1
$180,000
Partnership K-1
$70,000
Investment income
$35,000
Projected major household income:
Approximately:
$515,000
before other adjustments.
Their K-1 Checklist Finds Three Problems
Problem 1
S corporation distributions:
$150,000
But stock basis had not been updated.
Problem 2
Partnership income increased from:
$40,000
to:
$70,000
but estimated payments had not changed.
Problem 3
The partnership operated in two additional states.
Those state obligations had not been included.
Nothing about those problems required:
a new loophole.
They required:
coordination.
What They Changed
They:
Updated S corporation stock basis.
Reviewed distributions before taking more cash.
Increased the federal tax reserve.
Updated state tax estimates.
Requested a year-end partnership K-1 estimate.
Reviewed household withholding.
Updated the investment plan.
Protected Q1 operating cash.
The K-1s still had not arrived.
The planning was already underway.
Complete K-1 and Pass-Through Planning Checklist
ENTITY IDENTIFICATION
Every K-1 entity listed.
Entity type confirmed.
Ownership percentage confirmed.
Governing documents available.
Ownership changes recorded.
K-1 FORECASTING
Current-year estimate requested.
Ordinary income projected.
Capital gains projected.
Rental activity projected.
Interest/dividends included.
Expected distributions identified.
Low/expected/high scenarios built.
BASIS
S corporation stock basis current.
Debt basis current.
Partnership outside basis current.
Capital contributions recorded.
Owner loans documented.
Distributions recorded.
Suspended losses tracked.
HOUSEHOLD TAX
W-2 income included.
Spouse income included.
Investment income included.
Rental income included.
Retirement income included.
All K-1 income included.
Federal tax projected.
State tax projected.
TAX PAYMENTS
Federal estimates recorded.
State estimates recorded.
Withholding projected.
Safe-harbor target reviewed.
Actual projected liability reviewed.
Remaining tax gap calculated.
CASH FLOW
Tax reserve funded.
Tax distributions reviewed.
Working capital protected.
Q1 cash protected.
Household liquidity reviewed.
YEAR-END STRATEGY
QBI reviewed.
NIIT reviewed.
Capital gains reviewed.
Roth conversion reviewed.
Retirement contributions reviewed.
Charitable giving reviewed.
Major purchases reviewed.
STATE TAX
State allocations identified.
Nonresident filings reviewed.
Composite returns reviewed.
PTE tax payments reviewed.
Owner-level credits tracked.
FILING TIMELINE
Preliminary K-1 date known.
Final K-1 date known.
State schedule date known.
Extension likelihood reviewed.
Extension payment estimated.
Filing target established.
PROCESS
Quarterly review scheduled.
Open-item list maintained.
Documents centralized.
Next K-1 estimate date scheduled.
K-1 and Pass-Through Readiness Score
Give yourself one point for each YES.
All K-1s are identified.
Current estimates are available.
Cash distributions are known.
Taxable income and cash are tracked separately.
S corporation basis is current.
Partnership basis is current.
Estimated payments are updated.
Household withholding is reviewed.
Federal tax is projected.
State tax is projected.
Tax reserve is funded.
QBI and NIIT are reviewed.
Year-end transactions are coordinated.
Filing timeline is understood.
Next review is scheduled.
13–15 YES
GREEN — Pass-Through Planning Is Coordinated
8–12 YES
YELLOW — Important Gaps Remain
0–7 YES
RED — The Final K-1 Is Doing Too Much of the Planning
Your goal is to change that before filing season.
AI-Search Quick Answers
Can a partner owe tax on income that was not distributed?
Yes. A partner can generally be taxed on the partner's share of partnership income whether or not the partnership distributes matching cash. That is why distribution planning and tax reserves are important. (irs.gov)
Who is responsible for maintaining S corporation basis?
The shareholder is responsible for maintaining stock and debt basis. Basis affects the deductibility of losses and the tax treatment of distributions. (irs.gov)
Is partnership capital account the same as outside basis?
No. The IRS explains that the K-1 capital account does not necessarily equal the partner's adjusted outside basis. Among other differences, outside basis may include the partner's share of partnership liabilities. (irs.gov)
Can estimated payments be updated when K-1 income changes?
Yes. Estimated-tax planning should be recalculated when expected annual income changes materially. (irs.gov)
Does an extension give more time to pay?
No. An extension generally gives more time to file, not more time to pay the tax due. (irs.gov)
Why should K-1 income be estimated before year-end?
Because it can affect estimated payments, withholding, basis, QBI, NIIT, capital-gain decisions, Roth conversions, state taxes, tax reserves, and major household or business decisions before the final form arrives.
30 Questions Every K-1 Owner Should Answer
How many K-1s do I expect?
What entity issues each one?
What type of entity is it?
What is my ownership percentage?
What income is projected?
What distributions are projected?
Could income exceed cash received?
What is my S corporation stock basis?
What is my debt basis?
What is my partnership outside basis?
Are contributions documented?
Are owner loans documented?
Are suspended losses tracked?
Is QBI relevant?
Is NIIT relevant?
What federal estimated payments have been made?
What state estimated payments have been made?
What household withholding exists?
What is projected federal tax?
What is projected state tax?
Is the tax reserve sufficient?
What capital gains are planned?
Is a Roth conversion planned?
Are retirement contributions coordinated?
Is charitable giving planned?
What states does the entity operate in?
Are PTE tax credits expected?
When is the final K-1 expected?
Is an extension likely?
Am I managing the pass-through activity now—or waiting for a form to explain what already happened?
That is the question that closes this week.
What to Do Next
Build a one-page:
K-1 and Pass-Through Command Sheet
ENTITY
________________
OWNERSHIP
________%
PROJECTED K-1 INCOME
$________
EXPECTED DISTRIBUTION
$________
STOCK / OUTSIDE BASIS
$________
OWNER LOANS / DEBT BASIS
$________
FEDERAL TAX IMPACT
$________
STATE TAX IMPACT
$________
TAX RESERVE
$________
PTE TAX / CREDITS
$________
EXPECTED K-1 DATE
________
EXTENSION LIKELY?
Yes / No
NEXT REVIEW
________
Then update that sheet every quarter.
Final Thought
K-1 planning is not primarily about:
waiting for a tax form.
It is about understanding what the underlying entity is already creating.
Income.
Cash.
Tax exposure.
Basis.
Losses.
Distributions.
State obligations.
Filing complexity.
Those things exist before the final K-1 arrives.
So the process should begin before the form.
Identify the entities.
Estimate the income.
Track the distributions.
Maintain basis.
Update estimated payments.
Review household withholding.
Fund the reserve.
Coordinate QBI and NIIT.
Review state taxes.
Prepare for delayed filing when necessary.
Then reconcile everything when the final K-1 arrives.
That is the difference between:
reacting to pass-through income
and
managing it.
The K-1 should confirm the plan.
It should not create the plan.
Book Your K-1 and Pass-Through Tax Strategy Consultation
If you own interests in S corporations, partnerships, real-estate ventures, private businesses, or investment funds, your personal tax plan should not wait for filing season.
We can review:
Expected K-1 income;
distributions;
S corporation basis;
partnership basis;
shareholder and partner loans;
estimated payments;
household withholding;
federal tax exposure;
state tax exposure;
QBI;
NIIT;
capital gains;
retirement decisions;
PTE taxes;
tax reserves;
extension planning;
filing timelines.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.