Military Transition Tax Summary: What to Fix Now if Last Filing Season Was Messy
Financial Horizons: Military Transition Tax Series
Military Transition Tax Summary: What to Fix Now if Last Filing Season Was Messy
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
A messy filing season after military transition can feel like proof that civilian taxes are simply harder.
Sometimes they are.
Your financial life may now include:
military retired pay,
VA benefits,
civilian wages,
TSP or a civilian retirement plan,
business income,
rental property,
investments,
and perhaps more than one state.
That is more complicated than a military W-2 and an LES.
But complexity should not become an excuse for repeating the same problems.
If last filing season was difficult, use it as an after-action review.
Different mission. Same discipline. Identify what failed, fix the process, and do not repeat preventable problems.
Start With the Transition Problem That Hurt Most
Ask what made filing season harder than it should have been.
Was civilian withholding too low?
Were military retired pay and civilian wages never combined into one household projection?
Did you start consulting or a business without setting aside money for taxes?
Were rental-property records scattered across old duty-station files?
Did you have trouble finding TSP, brokerage, or military records?
Did a state-residency change create an unexpected filing requirement?
Do not try to fix everything at once.
Find the biggest problem first.
That is the one most likely to cause another surprise if nothing changes.
For service members and veterans, IRS Publication 3 remains the primary IRS guide to military-specific tax situations, including special filing rules for active and reserve members. IRS
Coordinate the New Income Picture
One of the biggest changes after separation or retirement is that income stops coming from one primary system.
You may now receive money from several places that do not coordinate with one another.
For example:
DFAS retired pay.
A civilian employer.
A spouse’s employer.
A consulting business.
Investments.
Rental property.
Each payer sees only its piece of your financial picture.
That is why your first post-military tax surprise may come from fragmentation rather than from any one income source.
The answer is to build one household projection.
Bring military retired pay, civilian wages, spouse income, business profit, investment income, and rental activity into the same conversation.
VA disability compensation generally is excluded from federal taxable income, while military retired pay based on age or length of service is generally taxable. The IRS also notes that eligible veterans can use MilTax through Military OneSource for free federal and up to five state returns for up to 365 days after separation or retirement. IRS
Fix Withholding and Tax Reserves Before the Next Surprise
A civilian employer generally does not know that you also receive military retired pay.
DFAS does not know what your civilian employer is withholding.
Neither necessarily knows about consulting income or capital gains.
That means your household may look fine when each paycheck is viewed separately but still be underfunded when everything is combined.
Review what has already been withheld and what has been paid through estimated taxes.
Then compare that with projected 2026 tax.
If a gap exists, build a reserve now.
That may be one of the most important habits to develop after leaving active duty.
Military life taught many of us to assign resources to the mission.
Tax cash should be treated the same way.
If it belongs to the future tax bill, it is not available for discretionary spending today.
A Quick Example
Consider Sergeant Major Allen, who retired and began working for a defense contractor.
His household now receives:
military retired pay,
civilian wages,
his spouse’s wages,
and occasional consulting income.
His first post-military return was messy.
The household withholding looked reasonable when each paycheck was viewed separately, but no one had combined all the income into one tax projection.
He also treated consulting deposits like ordinary take-home pay.
The final return showed a larger balance than expected.
Instead of blaming the tax code, he changed the process.
He reviewed withholding from both DFAS and his civilian employer.
He began reserving part of consulting income for taxes.
He created one folder for retirement, VA, business, and investment records.
And he scheduled a year-end projection before December.
The tax liability did not disappear.
The surprise did.
That is progress.
Do Not Forget Military-Specific Rules
Military taxpayers can also have filing rules that differ from the normal civilian timeline.
For qualifying combat-zone or contingency-operation service, the IRS can postpone filing, payment, and certain other deadlines. Publication 3 explains that the extension generally includes at least 180 days after qualifying service ends, plus additional time based on the period that remained when the qualifying service began. IRS
Certain military members serving outside the United States and Puerto Rico may also qualify for an automatic two-month extension to file and pay, subject to the IRS rules for taxpayers abroad. IRS
The important point is not to assume that every military taxpayer follows exactly the same deadline.
Document your service dates and confirm which rules apply.
Your Five Military Transition Fixes
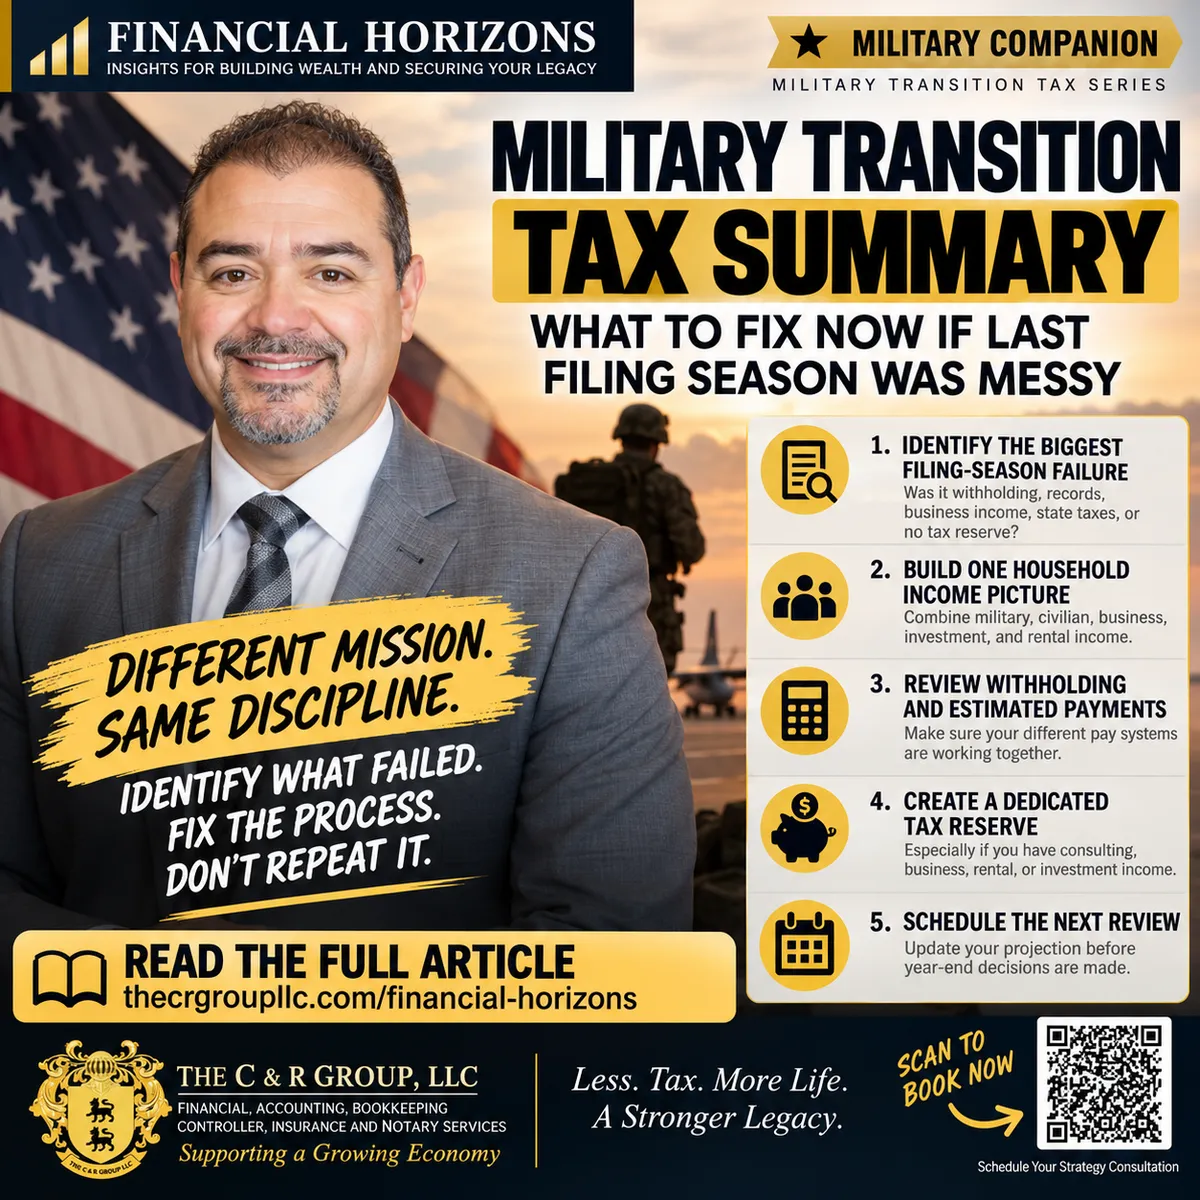
Identify the biggest filing-season failure. Was it withholding, records, business income, state residency, or tax reserves?
Build one household income picture. Combine military, civilian, business, investment, and rental income.
Review withholding and estimated payments. Make sure the different pay systems are working together.
Create a dedicated tax reserve. Especially if you have consulting, business, rental, or investment income.
Schedule the next review now. Use November to update the projection before year-end decisions are made.
That is enough to make the next filing season materially better.
Final Thought
Military transition changes the financial system around you.
For years, much of your pay, benefits, retirement contributions, and administrative information moved through structured military channels.
After retirement or separation, you become the system integrator.
That means coordinating:
DFAS,
VA,
civilian payroll,
retirement accounts,
business income,
investments,
rentals,
and state taxes.
If last filing season was messy, do not treat that as normal.
Use it as an AAR.
Identify what failed.
Fix the process.
Assign the money.
Schedule the next review.
Different mission. Same discipline. Build a civilian tax system that works before the next filing season arrives.
Book Your Military Transition Tax Strategy Consultation
If your last filing season exposed weak withholding, unplanned business income, retirement-tax issues, rental-property problems, state-residency questions, or an underfunded tax reserve, now is the time to clean up the process.
We can review your military retired pay, civilian income, VA benefits, TSP and retirement accounts, business or consulting income, estimated payments, state exposure, and year-end tax reserve.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.