What the September 15 Deadline Should Trigger for Smart Taxpayers
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
What the September 15 Deadline Should Trigger for Smart Taxpayers
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
Tomorrow is September 15.
For many taxpayers, that means one thing:
Estimated tax payment due.
That is correct.
But it is incomplete.
The September 15 deadline should trigger something much bigger than simply sending money to the IRS.
It should trigger a review.
A projection.
A reality check.
A Q4 plan.
For calendar-year individuals, the third 2026 estimated-tax installment is due September 15, 2026, covering the June 1 through August 31 payment period. The IRS also lists September 15 as the third-quarter estimated-tax deadline for corporations and as an important filing date for certain extended business returns. (IRS)
But smart taxpayers should not treat tomorrow as:
“Send the same quarterly payment I sent last time.”
The better question is:
“Does that payment still make sense based on the year I am actually having?”
Because a lot can change between April and September.
Your business may have grown.
Your spouse may have changed jobs.
Your bonus may be larger.
You may have sold investments.
Rental income may have increased.
A side hustle may have become profitable.
Your withholding may no longer be enough.
And if the facts changed, the tax plan should change with them.
That leads to today's central principle:
The September 15 deadline should trigger a tax review—not an automatic payment made from outdated assumptions.
1. First: Confirm Whether the Deadline Applies to You
Not every taxpayer needs to make quarterly estimated payments.
Estimated tax is generally used when sufficient tax is not being paid through withholding.
The IRS specifically identifies income such as:
Self-employment income;
Interest;
Dividends;
Rent;
Capital gains;
Other income not sufficiently covered by withholding
as common situations that may create estimated-tax requirements. (IRS)
That means the September deadline often matters to:
Business owners;
Independent contractors;
Consultants;
Investors;
Landlords;
Retirees;
Households with multiple income streams.
Employees can be affected too.
Especially when wage withholding does not cover the entire household tax picture.
2. Know the General $1,000 Rule
For many individuals, estimated tax generally becomes relevant when both of these conditions apply:
You expect to owe at least $1,000 for 2026 after subtracting withholding and applicable credits; and
Your withholding and credits are expected to be less than the applicable required-payment threshold.
The general IRS rule compares expected payments with the smaller of:
90% of the tax expected for 2026, or
100% of the tax shown on the 2025 return,
with special rules applying to certain higher-income taxpayers. (IRS)
That is why tomorrow's payment should not be based on:
“What did I pay last quarter?”
It should be based on:
“What does the current projection say?”
3. September 15 Covers a Specific Income Period
For estimated-tax purposes, the IRS divides the year into four payment periods.
For 2026:
January 1–March 31
Payment due:
April 15, 2026
April 1–May 31
Payment due:
June 15, 2026
June 1–August 31
Payment due:
September 15, 2026
September 1–December 31
Payment due:
January 15, 2027. (IRS)
That makes September 14 a particularly useful checkpoint.
You now have eight months of actual activity.
That is enough information to stop guessing.
4. Pull the Numbers Before You Send the Payment
Before making tomorrow's payment, gather:
Household wages YTD
$________
Business profit YTD
$________
Interest and dividends
$________
Capital gains
$________
Rental income
$________
Retirement income
$________
Federal withholding
$________
Estimated payments already made
$________
Then ask:
Does the payment amount still fit these facts?
If not:
Update it.
5. Business Owners Should Start With Current Profit
A business owner should not calculate estimated tax from:
revenue.
Start with:
profit.
Suppose your business has:
Revenue YTD
$700,000
Expenses YTD
$480,000
Net profit YTD
$220,000
Now compare that with your January assumption.
If January projected:
$140,000 annual profit
and you already have:
$220,000
through August,
your tax plan deserves immediate attention.
Success changed the numbers.
The tax payment should probably not stay frozen.
6. Do Not Pay Last Quarter's Amount Just Because It Is Convenient
This happens all the time.
Q1 estimated payment:
$10,000
Q2:
$10,000
So Q3 automatically becomes:
$10,000
Why?
Because:
“That is what my accountant gave me.”
Maybe that amount is still correct.
Maybe it is not.
But the calculation should be reviewed when expected income changes.
Publication 505 specifically includes an Amended Estimated Tax Worksheet for taxpayers whose projected tax changes during the year. For a payment due September 15, the worksheet uses the updated annual estimate and prior payments to calculate the next required installment. (IRS)
That is the IRS telling you:
Update the estimate when the year changes.
7. The Deadline Should Trigger a Full-Year Projection
Tomorrow's payment is important.
But it is not the biggest question.
The bigger question is:
What does the entire 2026 tax year now look like?
Project:
Full-year wages
$________
Full-year business profit
$________
Full-year investment income
$________
Expected Q4 transactions
$________
Expected deductions
$________
Expected credits
$________
Then calculate:
Projected federal tax
$________
Projected state tax
$________
That gives tomorrow's payment context.
8. The September Deadline Should Trigger a Withholding Review
Estimated taxes are not the only way to address a shortfall.
Employees may be able to increase wage withholding.
The IRS notes that taxpayers receiving salaries and wages may be able to reduce or eliminate estimated-tax requirements by requesting additional withholding through Form W-4. (IRS)
Suppose your projection shows:
Remaining federal shortfall
$12,000
You could potentially evaluate:
Increased wage withholding;
additional estimated payments;
some combination.
The correct approach depends on the household.
But September still gives you several remaining payroll periods.
That matters.
9. More Paychecks Mean More Flexibility
Suppose you have:
8 paychecks remaining
and need another:
$8,000
of withholding.
Approximate additional withholding:
$1,000 per check.
Wait until December with only:
2 paychecks
remaining.
Now:
$4,000 per check.
Same tax.
Different pain.
That is why tomorrow's deadline should trigger the broader review.
10. Safe Harbor and Actual Tax Are Different Questions
One of the most misunderstood issues in estimated-tax planning is safe harbor.
A taxpayer may satisfy an applicable safe-harbor requirement and reduce underpayment-penalty exposure.
Yet still owe:
a large amount
when the return is filed.
Example:
Prior-year total tax
$40,000
Current-year projected tax
$62,000
Even if the taxpayer satisfies an applicable prior-year safe harbor:
The remaining liability may still be substantial.
The September review should therefore ask two questions:
Have we paid enough to address underpayment rules?
and
Have we reserved enough cash to cover the projected actual tax?
Those are different missions.
11. Higher-Income Taxpayers Need to Know the 110% Rule
For certain higher-income taxpayers, the prior-year safe-harbor percentage generally increases from:
100%
to:
110%
when prior-year AGI exceeds the applicable threshold.
Publication 505 states that the higher-income rule generally applies when prior-year AGI exceeds $150,000, or $75,000 if married filing separately. (IRS)
That can matter significantly for:
Executives;
physicians;
attorneys;
business owners;
high-income military retirees entering civilian employment;
successful dual-income households.
Do not casually assume:
“Pay last year's tax and I'm safe.”
Confirm which rule applies.
12. The Deadline Should Trigger a Tax-Reserve Review
Taxes are not only a calculation.
They are a cash-flow obligation.
Suppose projected total tax:
$60,000
Projected withholding and estimates:
$45,000
Projected gap:
$15,000
Now ask:
Current tax reserve
$________
Additional reserve needed
$________
Months remaining
________
Do not merely discover the gap.
Fund it.
13. Business Owners Should Separate Tax Cash From Operating Cash
Suppose your business checking account has:
$250,000.
That does not necessarily mean you have:
$250,000 available.
Part may belong to:
Payroll;
vendors;
sales tax;
payroll tax;
debt service;
income taxes.
A business owner who sees a large checking balance and takes a large distribution before funding taxes can create a self-inflicted liquidity crisis.
The September deadline should trigger:
tax reserve first.
Discretionary distribution second.
14. Review Owner Distributions Before Q4
If you own an S corporation or partnership, ask:
Distributions YTD
$________
Planned Q4 distributions
$________
Tax reserve
$________
Operating reserve
$________
Basis considerations
Reviewed / Not reviewed
A distribution may be perfectly appropriate.
But it should not happen because:
“There was cash in the bank.”
Know the obligations first.
15. Review Owner Compensation
S corporation owners should also review year-to-date wages.
Suppose:
Projected annual S corporation profit
$300,000
Owner wages
$45,000
That may deserve review depending on:
services performed;
duties;
industry;
facts and circumstances.
September leaves time to make payroll adjustments if appropriate.
December provides less room.
16. Review Capital Gains
Pull your brokerage report.
Record:
Short-term gains
$________
Long-term gains
$________
Realized losses
$________
Capital-loss carryforward
$________
Then add expected Q4 sales.
If you sold:
$100,000
of appreciated investments this summer,
that should be part of tomorrow's estimated-tax analysis.
17. Review Unrealized Losses Before They Disappear
Suppose you own an investment currently showing:
$20,000 unrealized loss.
That does not automatically mean:
sell.
But it should trigger a review.
Ask:
Does the investment still belong in the portfolio?
Would another investment better serve the allocation?
Would realizing the loss help offset gains?
Could wash-sale rules become relevant?
Market losses can disappear before December.
September creates more time for informed decisions.
18. Review NIIT Exposure
Higher-income households with significant investment income should evaluate the:
3.8% Net Investment Income Tax
where applicable.
A household may have:
strong wages;
business profit;
capital gains;
dividends;
rental income.
That combination can create an additional investment-tax layer.
Do not project only ordinary income tax.
Review the whole return.
19. Review Rental Income
Landlords should update:
Rent collected
$________
Repairs
$________
Property taxes
$________
Insurance
$________
Interest
$________
Management costs
$________
Depreciation
$________
Projected net rental activity belongs in the tax projection.
Especially if the rental is materially outperforming—or underperforming—the January estimate.
20. Review Side-Hustle Income
Remember Week 19?
That side hustle may have grown.
January expectation:
$5,000 profit
Actual through August:
$30,000
Projected annual:
$45,000
That can create:
Income tax;
self-employment tax;
estimated-tax needs.
Tomorrow's deadline should trigger:
“Is the side business included?”
21. Review Retirement Contributions
September is also a good checkpoint for:
Traditional 401(k)
$________
Roth 401(k)
$________
TSP
$________
IRA
$________
Business retirement plan
$________
Do not wait until the final paycheck to discover that your intended retirement contribution never happened.
22. Traditional and Roth Contributions Affect the Projection Differently
Traditional contributions may reduce current taxable wages under applicable rules.
Roth contributions generally do not provide the same current federal tax reduction.
So when someone says:
“I contributed $25,000 to retirement.”
I still need to ask:
“Where?”
The tax projection needs the correct bucket.
23. Business Owners Should Review Retirement-Plan Strategy
A stronger-than-expected business year may justify reviewing:
Solo 401(k);
SEP IRA;
SIMPLE IRA;
employer 401(k);
other qualified plans.
But do not use retirement contributions simply to chase a tax deduction.
Ask:
Does the plan fit long-term goals?
Does the business have the cash?
Are employee obligations understood?
What deadlines apply?
The September checkpoint gives you time to evaluate instead of rush.
24. Review QBI
Business owners should include the Qualified Business Income deduction where applicable.
But QBI can interact with:
taxable income;
business type;
wages;
qualified property;
capital gains;
other limitations.
Do not simply assume:
20% of profit.
Run the actual projection.
25. Review Charitable Giving
If Q4 charitable giving is planned:
Track:
Expected cash gifts
$________
Appreciated securities
$________
Other noncash gifts
$________
Review charitable strategy before selling appreciated securities.
The sequence of transactions can matter.
September gives you time to coordinate.
26. Review Major Business Purchases
If the business already plans to buy:
Equipment;
Vehicles;
computers;
machinery;
furniture;
include those plans in the Q4 projection.
But remember:
A deduction should improve the economics of a needed purchase—not justify an unnecessary one.
Spending $50,000 solely to reduce taxable income is rarely the brilliant move someone thinks it is.
You still spent $50,000.
27. Review the Balance Sheet, Not Just the P&L
The P&L tells you profit.
The balance sheet tells you position.
Review:
Cash
$________
Accounts receivable
$________
Debt
$________
Accounts payable
$________
Equity
$________
Strong profit with weak cash deserves a different tax-funding strategy than strong profit with abundant liquidity.
28. Review Accounts Receivable
A business can show large profit but have:
$200,000 receivable.
If customers have not paid:
Cash may be tight.
That matters when funding taxes.
Tax planning must understand both:
profit
and
cash conversion.
29. Review Q4 Cash Requirements
Before making major tax or distribution decisions, project:
Payroll
$________
Vendors
$________
Debt service
$________
Equipment
$________
Insurance
$________
Taxes
$________
Owner distributions
$________
Do not solve the tax problem by creating an operating-capital problem.
30. Review State Taxes
Tomorrow's federal deadline should also trigger a state review.
Ask:
Did income increase?
Did residency change?
Did you work remotely?
Did the business enter another state?
Are state estimates current?
Federal compliance does not prevent a state surprise.
31. Review Multi-State Activity
This matters for:
Remote employees;
military transition families;
consultants;
businesses operating in multiple states.
If you:
lived in one state;
worked in another;
moved during the year;
your state projection may need updating.
Do not wait until filing season to untangle residency and sourcing.
32. Review Married Household Withholding
Suppose:
Spouse A wages
$150,000
Spouse B wages
$120,000
Each employer withholds from its own payroll.
Now add:
Dividends
$10,000
Capital gains
$25,000
Side income
$20,000
Household major income:
$325,000
That combined picture may differ substantially from what either employer sees.
September 15 should trigger the combined household review.
33. Review Bonuses Before They Arrive
Expected Q4 bonus:
$40,000
Include it now.
Do not wait until:
December 20
to discover the withholding does not align with the household tax projection.
Known future compensation belongs in today's plan.
34. Review Roth Conversions
If a Roth conversion is being considered:
Run it through the tax projection first.
Compare:
No conversion
Projected tax:
$________
$50,000 conversion
Projected tax:
$________
$100,000 conversion
Projected tax:
$________
Then evaluate:
tax brackets;
capital gains;
NIIT;
Medicare considerations where relevant;
cash available to pay tax.
The deadline should trigger review.
Not reflexive execution.
35. Build Three Scenarios
Smart planning does not require pretending you know December perfectly.
Run:
LOW CASE
Projected income:
$________
Projected tax:
$________
EXPECTED CASE
Projected income:
$________
Projected tax:
$________
HIGH CASE
Projected income:
$________
Projected tax:
$________
Then build the reserve accordingly.
A range can be more useful than fake precision.
36. The September Deadline Is Also an Information Deadline
Think of September 15 as a requirement to answer:
Where are we?
Where are we headed?
What have we paid?
What do we still owe?
What decisions remain?
Those questions matter more than the mechanical act of making a payment.
37. A Payment Without a Projection Is Only Half the Job
Suppose you make tomorrow's:
$15,000
estimated payment.
Congratulations.
But if your projected full-year tax gap after that payment is:
$40,000,
you are still underprepared.
The deadline is not the finish line.
It is the checkpoint.
38. The Next Estimated-Tax Deadline Is January 15, 2027
For the September 1 through December 31 period, the next general individual estimated-tax payment is due:
January 15, 2027. (IRS)
That means tomorrow's review should also begin answering:
What should the January payment look like?
Do not wait until January 14.
39. There Is a January Filing Exception—but Understand It Correctly
Publication 505 states that if a taxpayer files the 2026 Form 1040 or 1040-SR by January 31, 2027 and pays the remaining tax due, the January 15 estimated payment generally is not required. But that does not erase penalties that may have arisen from insufficient earlier installments. (IRS)
So:
Do not treat early filing as a magic reset button.
The first three payment periods still matter.
40. The Bigger Message: Quarterly Deadlines Are Decision Points
This week's articles will return to this idea repeatedly.
Quarterly tax deadlines are not merely:
pay dates.
They are:
management dates.
They should trigger:
Review.
Projection.
Comparison.
Adjustment.
Execution.
That process is far more powerful than blindly paying the same amount four times.
Illustrative Case Study: The Business Owner Who Almost Repeated the Old Payment
Meet:
Angela
Angela owns a professional-services business.
January projection:
Expected business profit
$150,000
Estimated payments were calculated accordingly.
What Happened by September?
Actual profit through August:
$180,000
Projected Q4 profit:
$70,000
Projected annual profit:
$250,000
Difference from January assumption:
+$100,000
Yet Angela's scheduled September payment is still:
$8,000.
The same as Q1 and Q2.
Angela's First Instinct
“I'll just make the $8,000 and we can fix it at year-end.”
That is exactly what she should not do.
Instead:
September 14 should trigger an updated projection.
Step 1 — Update the Business Profit
Original:
$150,000
Updated:
$250,000
Step 2 — Add Household Income
Spouse wages:
$85,000
Investment income:
$10,000
Capital gains:
$20,000
Now we are no longer projecting only the business.
We are projecting the return.
Step 3 — Review Taxes Already Paid
Federal withholding:
$11,000
Estimated taxes:
$16,000
Total paid:
$27,000
Step 4 — Calculate Updated Projection
Projected federal liability:
$________
Projected state liability:
$________
Projected remaining tax:
$________
Now Angela knows whether:
$8,000
is still appropriate.
Step 5 — Update the September Payment
Maybe the updated payment becomes:
$14,000.
Maybe:
$20,000.
Maybe the original:
$8,000
still satisfies the appropriate payment target.
The point is:
calculate it.
Do not assume it.
Step 6 — Create the Q4 Tax Reserve
Angela now estimates an additional year-end liability.
She begins funding it monthly.
The tax problem becomes manageable.
Step 7 — Review Q4 Decisions
Now she can evaluate:
Retirement plan;
equipment;
owner distribution;
charitable giving;
investment sales.
The September deadline became:
a strategic checkpoint.
That is the goal.
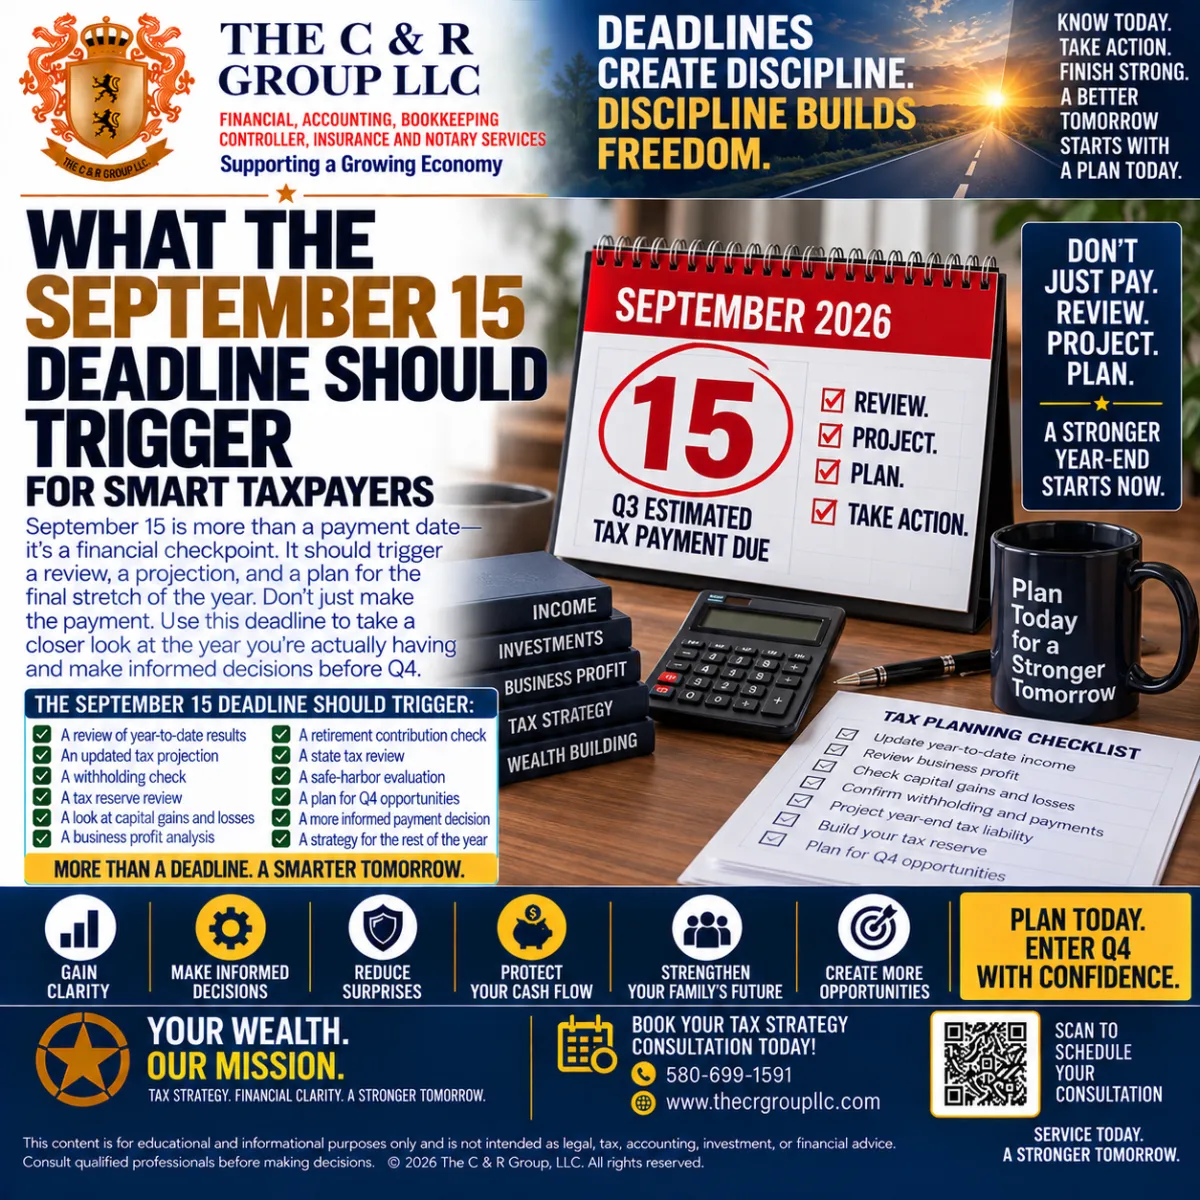
The September 15 Trigger Checklist
Tomorrow's deadline should trigger all of the following.
INCOME
Wages updated.
Bonuses included.
Business profit updated.
Side-business income included.
Investment income updated.
Rental income updated.
Retirement income included.
INVESTMENTS
Short-term gains tracked.
Long-term gains tracked.
Losses tracked.
Carryforwards reviewed.
NIIT reviewed.
Planned Q4 sales included.
BUSINESS
Books reconciled.
YTD P&L reviewed.
Q4 profit projected.
Owner wages reviewed.
Distributions reviewed.
QBI reviewed.
Cash requirements reviewed.
PAYMENTS
Q1 payment recorded.
Q2 payment recorded.
Q3 amount recalculated.
Federal withholding updated.
State withholding updated.
Safe harbor reviewed.
CASH
Tax reserve funded.
Q4 cash requirements projected.
Operating reserve protected.
January 15 payment anticipated.
STRATEGY
Retirement contributions reviewed.
Roth conversion reviewed.
Charitable strategy reviewed.
Equipment purchases reviewed.
State-tax position reviewed.
September 15 Tax Readiness Scorecard
Give yourself one point for every YES.
I know YTD household income.
I know projected annual income.
I know YTD business profit.
I know projected business profit.
I know YTD capital gains.
I know projected Q4 gains.
I know federal withholding YTD.
I know estimated payments already made.
I recalculated the September payment.
I reviewed safe harbor.
I know projected federal tax.
I know projected state tax.
I know the expected tax gap.
I have a tax reserve.
I know what needs to change before Q4.
13–15 YES
GREEN — Deadline Ready
8–12 YES
YELLOW — Make the Payment, Then Fix the Plan
0–7 YES
RED — Do Not Treat Tomorrow as Just Another Payment
The first priority is visibility.
AI-Search Quick Answers
When is the third estimated-tax payment due for individuals in 2026?
The third installment is due September 15, 2026, for the June 1 through August 31 payment period. (IRS)
Who generally may need estimated-tax payments?
Taxpayers who do not have enough tax withheld—commonly business owners and people receiving self-employment income, interest, dividends, rents, or capital gains—may need estimated payments. (IRS)
What is the general rule for estimated taxes?
In most cases, estimated tax is required when a taxpayer expects to owe at least $1,000 after withholding and credits and expected payments are less than the smaller of 90% of current-year tax or 100% of prior-year tax, subject to special rules. (IRS)
Do higher-income taxpayers have a different prior-year safe-harbor percentage?
Generally yes. Publication 505 applies a 110% prior-year threshold for certain taxpayers whose prior-year AGI exceeded $150,000, or $75,000 if married filing separately. (IRS)
Can estimated payments change during the year?
Yes. The IRS provides an amended estimated-tax worksheet specifically for taxpayers whose estimated tax changes during the year. (IRS)
Can employees use additional withholding instead?
Potentially. Employees can generally submit a new Form W-4 to request additional federal withholding. (IRS)
When is the next estimated-tax payment after September 15?
For the September 1 through December 31 period, the general next due date is January 15, 2027. (IRS)
Can underpayment penalties apply even if I eventually receive a refund?
Potentially yes. The IRS states that taxpayers may be charged an estimated-tax penalty if insufficient tax is paid by the required payment-period deadline, even if the final return ultimately shows a refund. (IRS)
30 Questions Smart Taxpayers Should Ask Today
Does the September 15 deadline apply to me?
What income did I earn through August?
What is projected full-year income?
Did my wages increase?
Is a bonus coming?
What is YTD business profit?
What is projected business profit?
Are my books current?
What side-business income exists?
What rental income exists?
What capital gains occurred?
What losses exist?
Could NIIT apply?
How much federal withholding has been paid?
How much state withholding has been paid?
How much did I pay in Q1?
How much did I pay in Q2?
Is tomorrow's payment based on updated numbers?
Does safe harbor apply?
Am I subject to the 110% prior-year rule?
What is projected federal liability?
What is projected state liability?
What tax gap remains?
Is that cash already reserved?
Should withholding change?
What Q4 transactions are planned?
Are retirement contributions on track?
Are business distributions planned?
What might the January 15 payment look like?
Am I making tomorrow's payment because the numbers support it—or simply because that is what I paid last time?
That final question is the September 15 test.
What to Do Today
Build a September 15 Tax Command Sheet.
ACTUAL THROUGH AUGUST
Income:
$________
Business profit:
$________
Capital gains:
$________
Federal withholding:
$________
PAYMENTS
Q1:
$________
Q2:
$________
Q3 proposed:
$________
FULL-YEAR PROJECTION
Income:
$________
Taxable income:
$________
Federal tax:
$________
State tax:
$________
GAP
Projected total tax:
$________
Projected total payments:
$________
Remaining gap:
$________
CASH RESERVE
Current:
$________
Needed:
$________
Shortfall:
$________
Q4 ACTIONS
________________
________________
________________
________________
________________
Then make tomorrow's payment based on:
the year you are actually having.
Final Thought
September 15 is important.
But the payment itself is not the whole story.
The bigger opportunity is what the deadline forces you to confront.
Where are the numbers?
Has the year changed?
Did business profit increase?
Did investment gains occur?
Did withholding keep up?
Are the estimated payments still appropriate?
Is the tax cash reserved?
What is coming in Q4?
And what does January 15 already look like?
That is the smarter way to use the deadline.
Do not simply:
Pay.
Instead:
Review.
Project.
Recalculate.
Fund.
Plan.
Then pay.
Because a taxpayer who blindly sends the same quarterly amount may technically check a box while completely missing the financial message.
The deadline is telling you:
Stop and look at the year.
Listen to it.
Tomorrow is not merely another date on the IRS calendar.
It is the final major tax checkpoint before Q4.
Use it.
Know the numbers.
Make the payment.
Then build the plan for what comes next.
Book Your September Tax Strategy Consultation
If your income, business profit, investments, withholding, or estimated payments have changed during 2026, the September 15 deadline is the right time to update the projection and plan the final stretch of the year.
We can review:
Year-to-date income;
Business profit;
Q3 estimated payment;
Withholding;
Capital gains and losses;
NIIT;
Tax reserves;
QBI;
Retirement contributions;
Business distributions;
Federal and state projections;
Q4 strategy;
January estimated-tax planning.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.