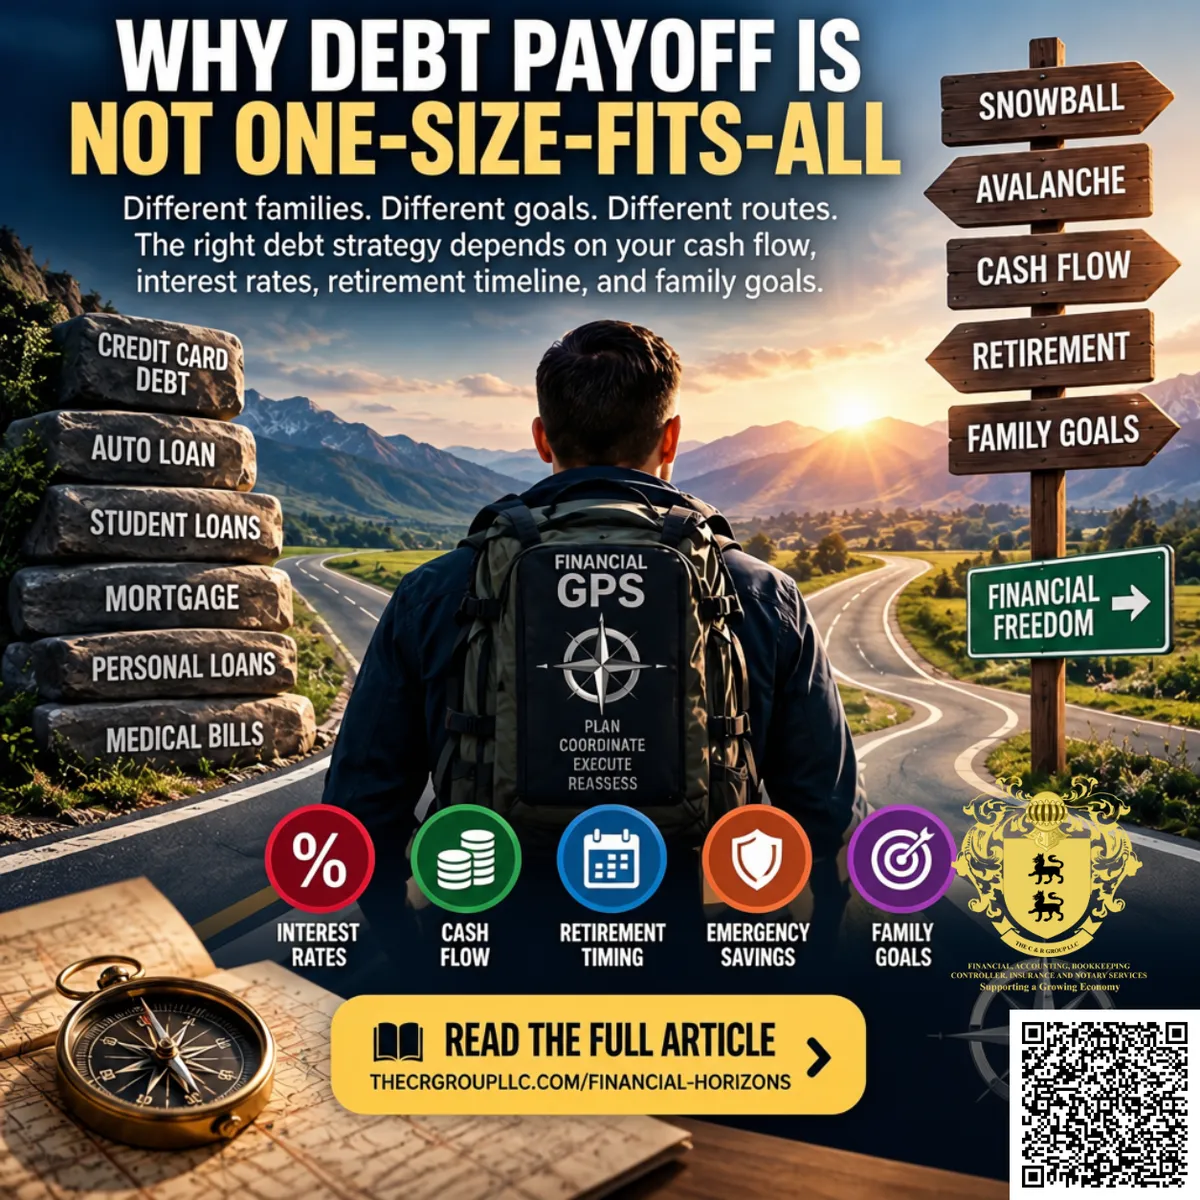
Why Debt Payoff Is Not One-Size-Fits-All
Financial Horizons: Insights for Building Wealth and Securing Your Legacy
Why Debt Payoff Is Not One-Size-Fits-All
By Dr. Jose G. Cardenas | Chief Tax Strategist, The C & R Group, LLC
There is no shortage of advice about how to pay off debt.
Use the snowball.
Use the avalanche.
Pay the mortgage first.
Pay the credit cards first.
Stop investing until everything is gone.
Never stop investing.
The problem is that families are not identical.
A 32-year-old couple with stable jobs, no children, and $15,000 in credit-card debt does not have the same financial mission as a 58-year-old military retiree with a pension, TSP, a mortgage, and five years until full retirement.
Yet too many people are handed the same debt-payoff formula.
That is why I believe debt payoff should begin with a Financial GPS, not a slogan.
The real question is not simply:
“What debt should I pay first?”
The better question is:
“What debt strategy best supports my family's cash flow, retirement, protection, and long-term goals?”
Debt Has Different Costs
Two debts with the same balance can create completely different financial problems.
A $20,000 credit-card balance at a high interest rate may be draining cash flow aggressively.
A $20,000 vehicle loan with a lower rate may have a large monthly payment but a much shorter remaining term.
A mortgage may carry a relatively low rate but continue for decades.
Those differences matter.
That is why I want families to look at more than the balance.
Review:
interest rate;
minimum payment;
remaining term;
total monthly cash-flow impact;
whether the debt is secured or unsecured;
and what happens when that payment disappears.
Debt payoff is not simply mathematics.
It is also about timing and flexibility.
The Snowball and Avalanche Both Have Strengths
The debt snowball focuses on paying off the smallest balance first.
That can create early wins.
A family may eliminate one balance quickly, build confidence, and redirect the former payment toward the next debt.
The debt avalanche focuses on the highest interest rate first.
That may reduce interest costs more efficiently.
Both methods can work.
But neither automatically considers everything else happening in the family's financial life.
What if the highest-interest debt has a relatively small monthly payment, while another debt consumes $900 every month?
What if the family has no emergency savings?
What if retirement is only five years away?
What if a bonus is coming?
What if one spouse may stop working?
Those are Financial GPS questions.
The debt method should support the larger mission.
Cash Flow Can Matter as Much as Interest
Sometimes the most powerful debt to eliminate is not the one with the highest rate.
It may be the one that releases the most cash flow.
Suppose a family has:
a $5,000 credit card requiring $150 per month;
a $12,000 vehicle loan requiring $650 per month; and
a $200,000 mortgage requiring $1,700 per month.
The credit card may have the highest interest rate.
Mathematically, paying it first may make sense.
But the vehicle loan may be close enough to payoff that eliminating it quickly could release $650 per month.
That newly available cash flow could then attack the credit card aggressively.
There is no universal answer.
The point is to understand the tradeoff.
A good debt strategy does not simply reduce balances.
It improves the family's entire financial position.
A Simple Family Example
Imagine a military retiree and spouse in their mid-50s.
They have a mortgage, one vehicle payment, credit-card debt, and strong retirement savings.
Their first instinct is to attack the mortgage because they want the house paid off before retirement.
But after reviewing the full Financial GPS, they discover the credit card is costing far more in interest and the vehicle payment is consuming significant monthly cash flow.
They decide to target the credit card first.
Once that is gone, they redirect the freed payment toward the vehicle.
When the vehicle disappears, that payment is redirected toward the mortgage and retirement.
Their final mission did not change.
They still wanted the mortgage gone before retirement.
What changed was the route.
That is the difference between having a debt goal and having a debt strategy.
Retirement Changes the Debt Conversation
Age and time horizon matter.
A 30-year-old may have decades to accumulate retirement assets.
A 60-year-old may have a very different set of priorities.
If retirement is approaching, the family needs to understand which debts will still exist when employment income declines.
A mortgage payment that feels manageable during peak earning years may feel very different when retirement income begins.
That is why debt payoff should connect to retirement planning.
Know your target retirement date.
Know your target debt-free date.
Then compare them.
If the two timelines do not work together, something needs to change.
Emergency Savings Still Matters
Another mistake is becoming so aggressive with debt payoff that the family eliminates all liquidity.
That can backfire.
If every available dollar goes toward debt and the family has no emergency reserve, one large repair or medical expense may go right back onto a credit card.
Then the debt cycle starts again.
A strong strategy balances progress with resilience.
For some families, building a modest emergency reserve before accelerating debt may be the smarter first move.
That may not feel as exciting as watching a balance drop.
But it can keep the plan from collapsing at the first unexpected expense.
Where IUL May Fit
For some families, permanent life insurance such as indexed universal life insurance may eventually become part of the broader wealth strategy.
An IUL can provide a death benefit and may build cash value over time.
When properly structured and sufficiently funded, policy value may later be accessed through policy loans or withdrawals, subject to the policy's terms.
That may create another source of long-term flexibility.
But IUL should not be used to force every household into the same strategy either.
A family buried in expensive revolving debt with no emergency fund probably has more urgent priorities.
A family with strong cash flow, manageable debt, long-term insurance needs, and sufficient time may be in a very different position.
Again:
One size does not fit all.
Five Questions Before Choosing a Debt Strategy
Before deciding which balance to attack first:
Which debt costs the most in interest?
Which payment consumes the most monthly cash flow?
How much emergency savings do we have?
What debts will still exist when we retire?
What will we do with each payment after that debt is eliminated?
Those five questions are more useful than blindly following a debt method because they connect payoff decisions to the entire financial mission.
Final Thought
Debt payoff should not be treated like a contest to see who can eliminate balances fastest.
The purpose is bigger than that.
The purpose is to create:
More cash flow.
More flexibility.
More retirement readiness.
More family security.
More control.
The snowball may be right for one family.
The avalanche may be right for another.
A hybrid approach may make more sense for someone else.
The right debt strategy is the one that supports your actual Financial GPS.
Do not ask which debt method is best. Ask which route is best for your family.
That is how you turn debt payoff from a generic formula into a real financial strategy.
Protect, Grow, and Transfer Wealth — The Right Way.
Book Your Strategy Consultation
If you are making debt payments every month but are not sure whether you are attacking the right balances in the right order, it may be time to build a clearer route.
Schedule a strategy consultation to review your debt, cash flow, retirement timeline, family protection, and long-term Financial GPS.
Booking link:
https://api.leadconnectorhq.com/widget/booking/T4UHUjCijCtIB3rwoTDI
Phone: 580-699-1591
Booking your appointment now:
ABOUT THE AUTHOR
Dr. Jose G. Cardenas is a retired U.S. Army Finance Officer and the Chief Tax Strategist at The C & R Group, LLC. With a Doctorate in Business Administration and over 20 years of experience in tax planning and financial strategy, Dr. Cardenas helps individuals and business owners legally reduce taxes, strengthen cash flow, and build lasting wealth and legacy. Learn more at www.thecrgroupllc.com
DISCLOSURE
This article is for educational and informational purposes only and is not intended to serve as personalized legal, tax, or investment advice. Tax laws and regulations change over time and may vary by jurisdiction. You should consult with a qualified tax professional regarding your specific circumstances before implementing any strategy discussed here. Dr. Jose G. Cardenas, DBA, provides tax advisory services through The C & R Group, LLC. Insurance and investment strategies may be offered through his role as a licensed financial professional affiliated with Experior Financial Group.